Strategy vault / Trend following
Dual EMA Crossover Trend Tracking Strategy
The Dual EMA Crossover Trend Tracking strategy is a quantitative trading strategy that uses dual EMA indicators to determine the price trend direction. This strategy calculates two EMA indicators with different…
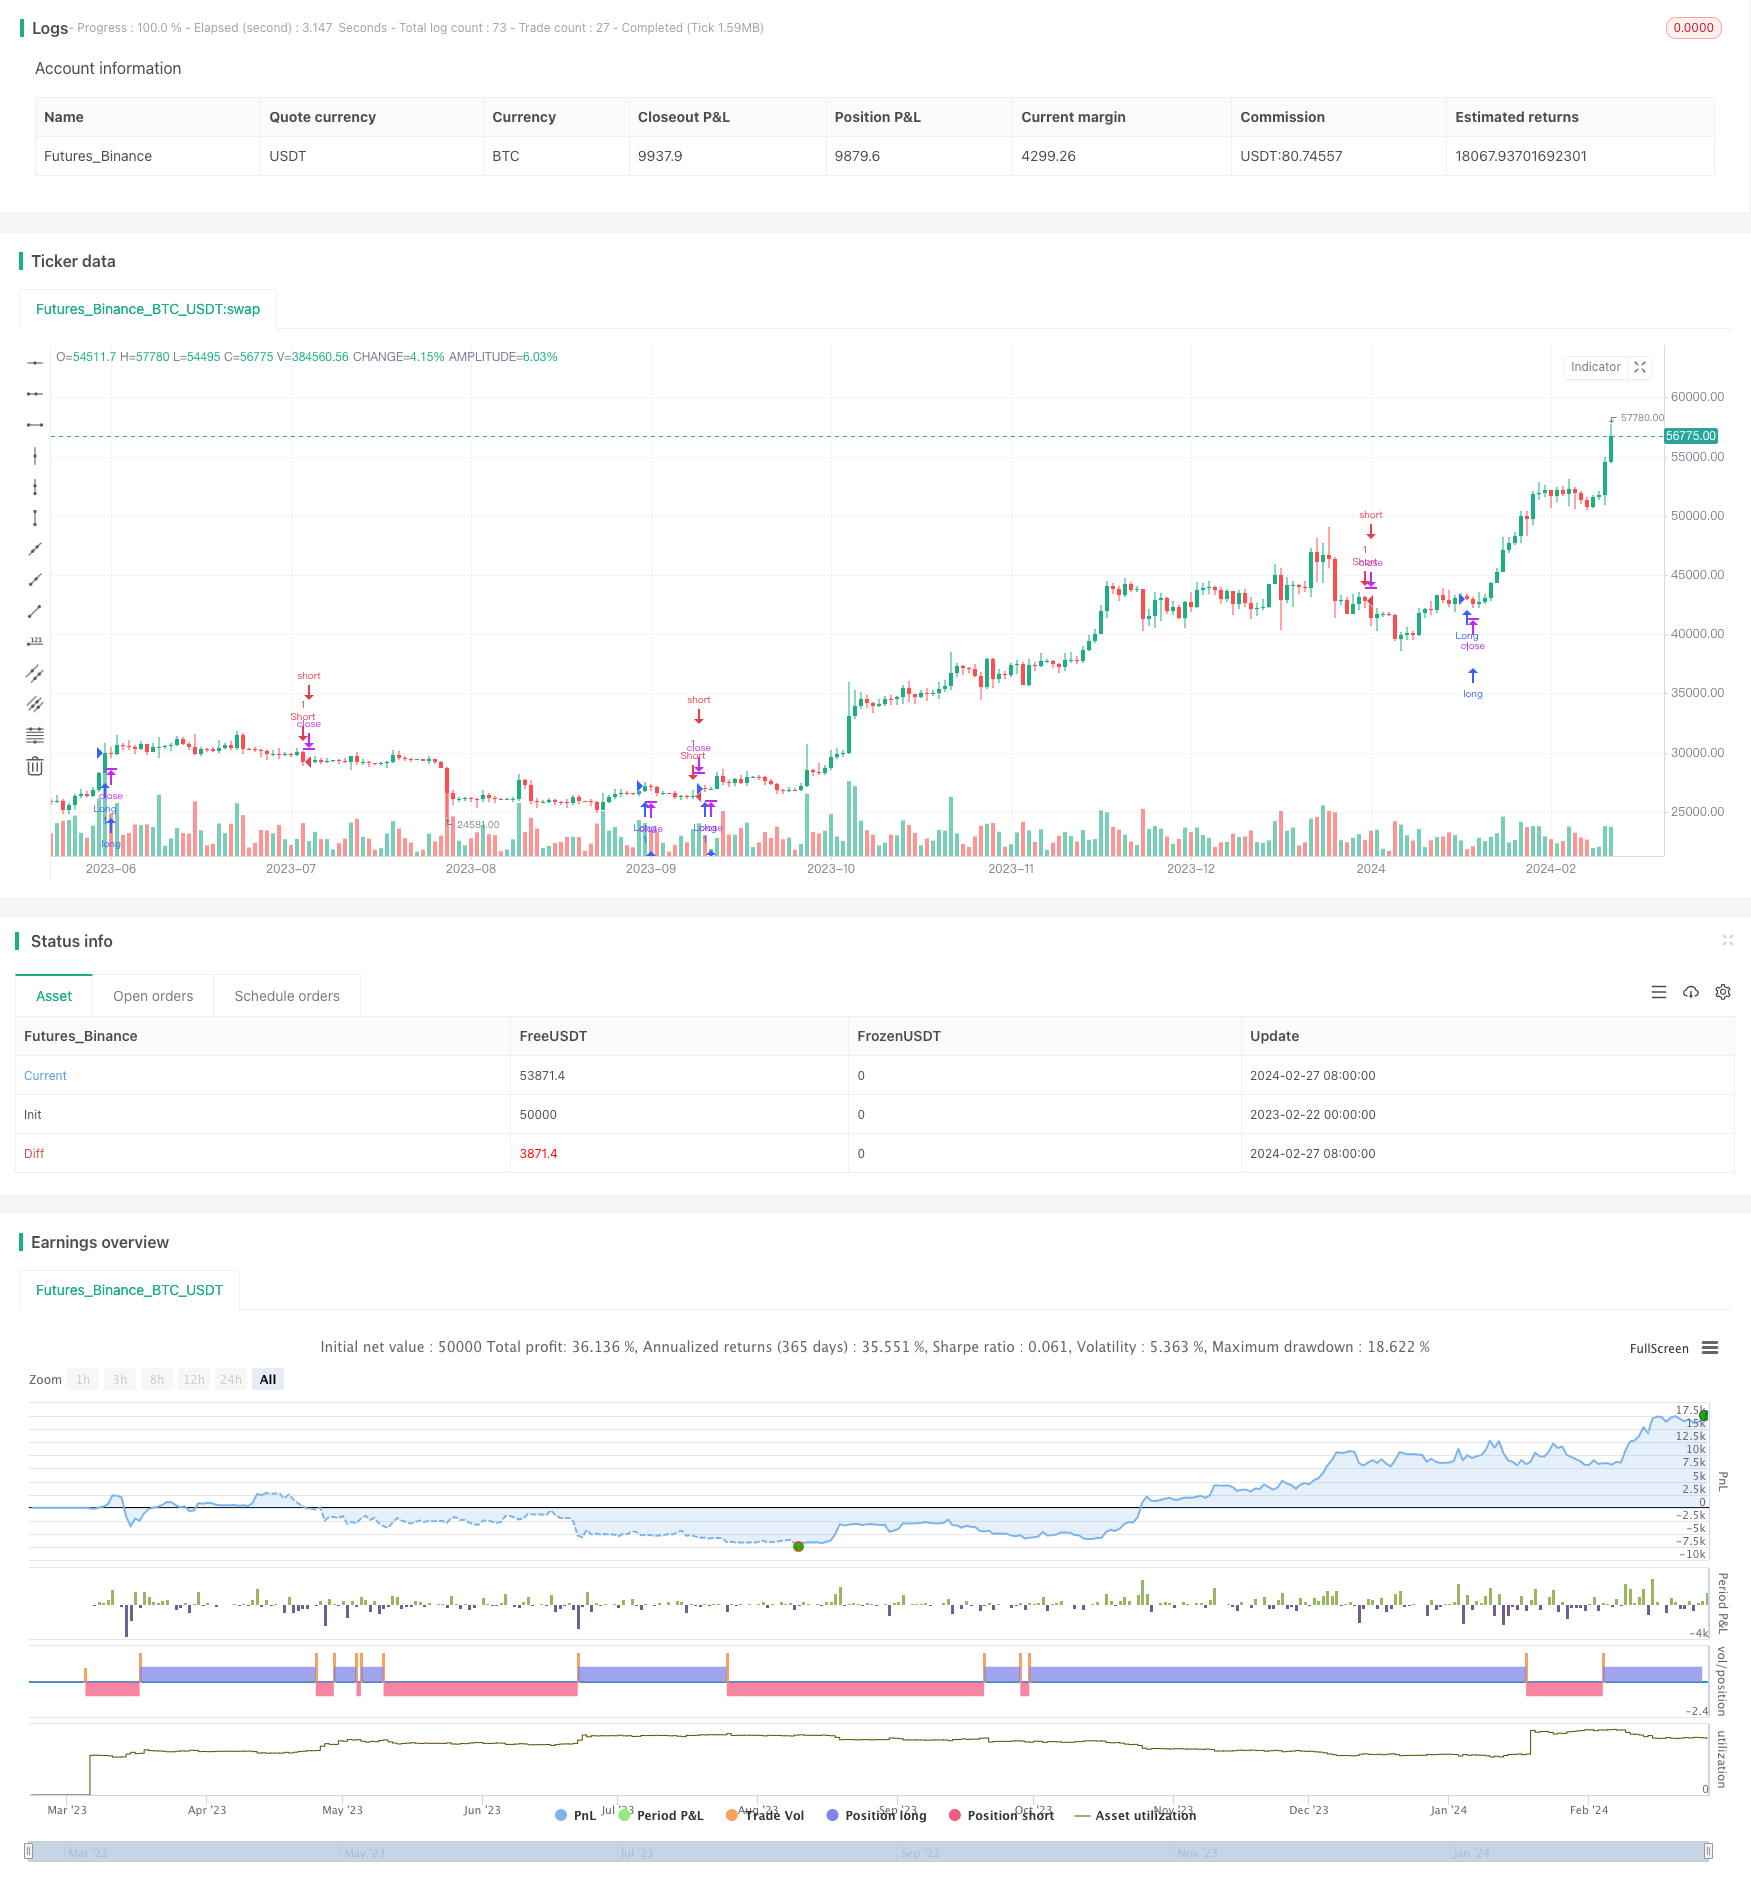
Overview
The Dual EMA Crossover Trend Tracking strategy is a quantitative trading strategy that uses dual EMA indicators to determine the price trend direction. This strategy calculates two EMA indicators with different parameters and combines golden cross and dead cross signals to judge the price trend. It generates a buy signal when the shorter period EMA crosses above the longer period EMA, and a sell signal when the shorter period EMA crosses below the longer period EMA.
Strategy Logic
The core indicators of this strategy are two sets of EMAs, including a longer cycle EMA1 and a shorter cycle EMA2. The EMA1 parameter is 21 and the EMA2 parameter is 10. The strategy calculates these two EMAs based on the 4-hour cycle.
When the shorter cycle EMA2 crosses above the longer cycle EMA1, a buy signal is generated. This indicates that the short-term trend of prices has strengthened and an upward trend has begun. When the shorter cycle EMA2 crosses below the longer cycle EMA1, a sell signal is generated. This indicates that the short-term upward trend of prices has been interrupted and a downward trend has begun.
To filter erroneous signals, the strategy sets two sets of golden cross and dead cross indicators. Signals are only triggered when both sets of indicators give out the same signal, which can effectively reduce errors caused by price fluctuations.
Advantage Analysis
The dual EMA structure can effectively capture changes in short and medium-term trends to determine trends.
The additional filtering of two sets of golden cross and dead cross indicators can reduce erroneous signals and avoid unnecessary transactions caused by price fluctuations.
The use of 4-hour levels to calculate indicators can cope with high-frequency price fluctuations.
The strategy structure is simple and clear, easy to understand and implement, and suitable for quantitative trading applications.
Risk Analysis
The dual EMA structure is less effective in judging consolidation markets. Long periods of consolidation can generate false signals.
The 4-hour level indicators are not sensitive enough to respond to sudden events. Major sudden news may cause big moves within 4 hours that cannot be effectively risk-controlled.
The strategy relies solely on technical indicators without combining fundamental analysis. If major changes occur in company fundamentals, technical indicators may fail.
These risks can be controlled by:
Add more time-cycle EMA indicators to establish model combinations.
Use text sentiment analysis to determine major sudden events and dynamically adjust positions.
Associate changes in economic environment, policies and company fundamentals to dynamically adjust parameters.
Optimization
The strategy can be further optimized:
Add model combinations. More indicator combinations with different parameters can be established to improve strategy stability.
Add stop loss mechanisms. Reasonable stop loss points can effectively control single losses.
Dynamic parameter optimization. EMA parameters can be automatically optimized based on different market environments.
Incorporate machine learning techniques. Models such as Tensorflow can be trained to categorize price trends in real time.
Conclusion
The dual EMA golden cross dead cross trend tracking strategy is a simple and practical trend trading strategy. It uses dual EMA indicators to determine short and medium-term price trends in order to capture directional market opportunities. At the same time, combining two sets of golden cross and dead cross filtering indicators can reduce erroneous trades. The strategy has a simple structure and is easy to implement, making it suitable for quantitative trading applications. Through continuous optimization and improvement, it has the potential to further expand the advantages of the strategy and improve stable profitability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2017 | Backtest Start Year |
| v_input_2 | true | Backtest Start Month |
| v_input_3 | true | Backtest Start Day |
| v_input_4 | 2020 | Backtest Stop Year |
| v_input_5 | true | Backtest Stop Month |
| v_input_6 | true | Backtest Stop Day |
| v_input_7 | false | Color Background? |
| v_input_8 | true | Margin? |
| v_input_9 | 240 | EMA Timeframe |
| v_input_10 | 21 | EMA1 |
| v_input_11 | 10 | EMA2 |
Source Pine Script
/*backtest
start: 2023-02-22 00:00:00
end: 2024-02-28 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3


/// Component Code Startt
testStartYear = input(2017, "Backtest Start Year")
testStartMonth = input(01, "Backtest Start Month")
testStartDay = input(1, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,0,0)

testStopYear = input(2020, "Backtest Stop Year")
testStopMonth = input(1, "Backtest Stop Month")
testStopDay = input(1, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay,0,0)

// A switch to control background coloring of the test period
testPeriodBackground = input(title="Color Background?", type=bool, defval=false)
testPeriodBackgroundColor = testPeriodBackground and (time >= testPeriodStart) and (time <= testPeriodStop) ? #00FF00 : na
bgcolor(testPeriodBackgroundColor, transp=97)

testPeriod() => true
// Component Code Stop

strategy(title="Ema cross strat", overlay=true)
margin = input(true, title="Margin?")
Margin = margin  ? margin : false
resCustom = input(title="EMA Timeframe", defval="240" )
source = close,
len2 = input(21, minval=1, title="EMA1")
len3 = input(10, minval=1, title="EMA2")
ema2 = request.security(syminfo.tickerid,resCustom,ema(source,len2), lookahead=barmerge.lookahead_off)
ema3 = request.security(syminfo.tickerid,resCustom,ema(source,len3), lookahead=barmerge.lookahead_off)


mylong = crossover(ema3, ema2)
myshort = crossunder(ema3,ema2)

last_long = na
last_short = na
last_long := mylong ? time : nz(last_long[1])
last_short := myshort ? time : nz(last_short[1])

in_long = last_long > last_short ? 2 : 0
in_short = last_short > last_long ? 2 : 0

mylong2 = crossover(ema3, ema2)
myshort2 = crossunder(ema3, ema2)

last_long2 = na
last_short2 = na
last_long2 := mylong2 ? time : nz(last_long2[1])
last_short2 := myshort2 ? time : nz(last_short2[1])

in_long2 = last_long2 > last_short2 ? 0 : 0
in_short2 = last_short2 > last_long2 ? 0 : 0

condlongx =   in_long + in_long2
condlong = crossover(condlongx, 1.9)
condlongclose = crossunder(condlongx, 1.9)

condshortx =  in_short + in_short2
condshort = crossover(condshortx, 1.9)
condshortclose = crossover(condshortx, 1.9)


if crossover(condlongx, 1.9) and testPeriod() and strategy.position_size <= 0
    strategy.entry("Long", strategy.long, comment="Long")

if crossover(condshortx, 1.9) and testPeriod() and strategy.position_size > 0
    strategy.close("Long",when = not Margin)

if crossover(condshortx, 1.9) and testPeriod() and strategy.position_size >= 0
strategy.entry("Short", strategy.short, comment="Short", when = Margin)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-EMA-Crossover-Trend-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- ATR and T3 Moving Average StrategyPine Script · Trend following · 5m