Dual EMA Golden Cross Breakthrough Strategy
This strategy is a trend following strategy based on golden cross and death cross operations of the 5-minute and 34-minute exponential moving averages (EMA) lines. It goes long when the fast EMA crosses over the slow…
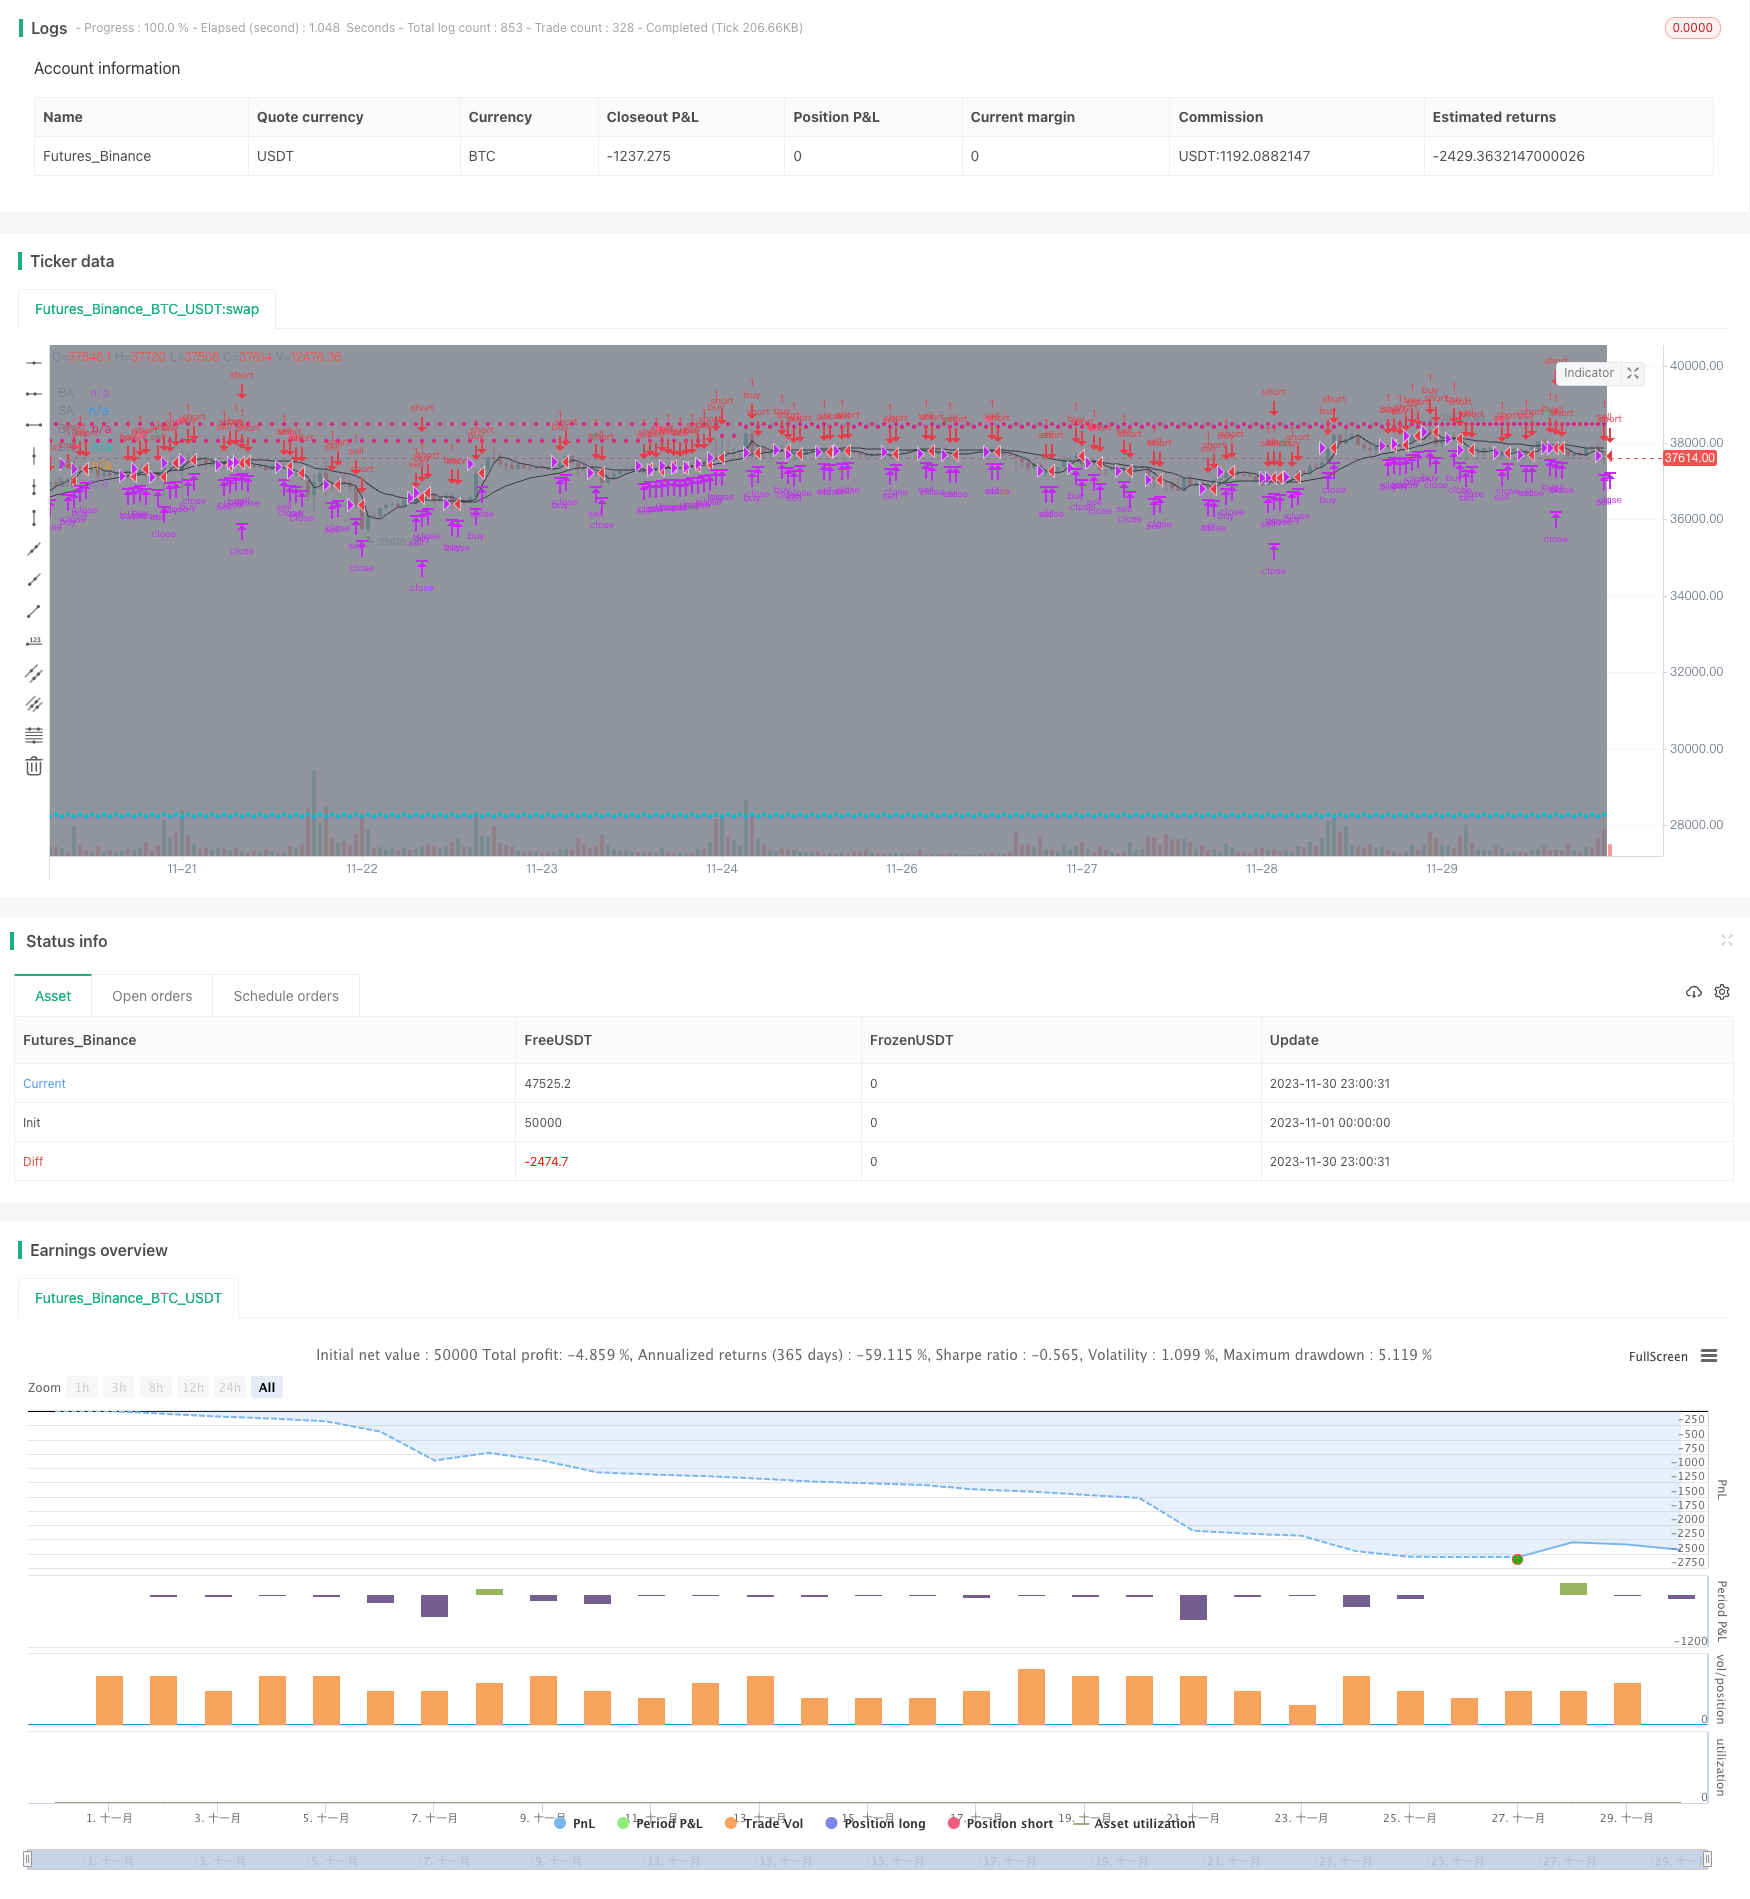
Overview
This strategy is a trend following strategy based on golden cross and death cross operations of the 5-minute and 34-minute exponential moving averages (EMA) lines. It goes long when the fast EMA crosses over the slow EMA from below, and goes short when the fast EMA crosses below the slow EMA from above. It also sets stop profit and stop loss to control risks.
Strategy Principle
- The fast EMA5 and slow EMA34 form trading signals. EMA5 reflects recent Price changes and EMA34 reflects mid-term Price changes.
- When EMA5 crosses over EMA34, it's a golden cross, indicating the short-term trend is better than the mid-term trend, so hold long position.
- When EMA5 crosses below EMA34, it's a death cross, indicating the short-term trend is worse than the mid-term trend, so hold short position.
- Set stop profit and stop loss to lock in profits and control risks.
Advantage Analysis
- Using dual EMA filters false breakouts and avoids being trapped.
- Following mid-term trends enhances profit opportunities.
- Setting stop profit and stop loss effectively controls risks.
Risk Analysis
- Dual EMA has lagging effect and may miss short-term trading opportunities.
- Stop loss set too wide enlarges loss risks.
- Stop profit set too tight loses opportunities to maximize profits.
Optimization Directions
- Optimize EMA parameters to find the best parameter combination.
- Optimize stop profit and stop loss points to lock in greater profits.
- Add other indicators like MACD, KDJ to filter signals and improve accuracy.
Summary
This strategy generates trading signals from golden crosses and death crosses of the dual EMA lines, and sets stop profit and stop loss to control risks. It is a simple and effective mid-term trend following strategy. Further enhancing stable profitability can be achieved by optimizing stop profit/loss parameters and introducing other indicators to filter signals.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Use Trading Session? |
| v_input_2 | true | Use Trailing Stop? |
| v_input_3 | 0400-1500 | Trade Session: |
| v_input_4 | true | Trade Size: |
| v_input_5 | 55 | Take profit in pips: |
| v_input_6 | 22 | Stop loss in pips: |
| v_input_7 | 5 | EMA length: |
| v_input_8 | 34 | DEMA length: |
| v_input_9_open | 0 | Price source:: open | high | low | close | hl2 | hlc3 | hlcc4 | ohlc4 |
Source Pine Script
/*backtest
start: 2023-11-01 00:00:00
end: 2023-11-30 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy(title='[STRATEGY][RS]MicuRobert EMA cross V2', shorttitle='S', overlay=true, pyramiding=0, initial_capital=100000)
USE_TRADESESSION = input(title='Use Trading Session?', type=bool, defval=true)
USE_TRAILINGSTOP = input(title='Use Trailing Stop?', type=bool, defval=true)
trade_session = input(title='Trade Session:',defval='0400-1500', confirm=false)
istradingsession = not USE_TRADESESSION ? false : not na(time('1', trade_session))
bgcolor(istradingsession?gray:na)
trade_size = input(title='Trade Size:', type=float, defval=1)
tp = input(title='Take profit in pips:', type=float, defval=55.0) * (syminfo.mintick*10)
sl = input(title='Stop loss in pips:', type=float, defval=22.0) * (syminfo.mintick*10)
ma_length00 = input(title='EMA length:',  defval=5)
ma_length01 = input(title='DEMA length:',  defval=34)
price = input(title='Price source:',  defval=open)

//  ||--- NO LAG EMA, Credit LazyBear:  ---||
f_LB_zlema(_src, _length)=>
    _ema1=ema(_src, _length)
    _ema2=ema(_ema1, _length)
    _d=_ema1-_ema2
    _zlema=_ema1+_d
//  ||-------------------------------------||

ma00 = f_LB_zlema(price, ma_length00)
ma01 = f_LB_zlema(price, ma_length01)
plot(title='M0', series=ma00, color=black)
plot(title='M1', series=ma01, color=black)

isnewbuy = change(strategy.position_size)>0 and change(strategy.opentrades)>0
isnewsel = change(strategy.position_size)<0 and change(strategy.opentrades)>0

buy_entry_price = isnewbuy ? price : buy_entry_price[1]
sel_entry_price = isnewsel ? price : sel_entry_price[1]
plot(title='BE', series=buy_entry_price, style=circles, color=strategy.position_size <= 0 ? na : aqua)
plot(title='SE', series=sel_entry_price, style=circles, color=strategy.position_size >= 0 ? na : aqua)
buy_appex = na(buy_appex[1]) ? price : isnewbuy ? high : high >= buy_appex[1] ? high : buy_appex[1]
sel_appex = na(sel_appex[1]) ? price : isnewsel ? low : low <= sel_appex[1] ? low : sel_appex[1]
plot(title='BA', series=buy_appex, style=circles, color=strategy.position_size <= 0 ? na : teal)
plot(title='SA', series=sel_appex, style=circles, color=strategy.position_size >= 0 ? na : teal)
buy_ts = buy_appex - sl
sel_ts = sel_appex + sl
plot(title='Bts', series=buy_ts, style=circles, color=strategy.position_size <= 0 ? na : red)
plot(title='Sts', series=sel_ts, style=circles, color=strategy.position_size >= 0 ? na : red)

buy_cond1 = crossover(ma00, ma01) and (USE_TRADESESSION ? istradingsession : true)
buy_cond0 = crossover(price, ma00) and ma00 > ma01 and (USE_TRADESESSION ? istradingsession : true)
buy_entry = buy_cond1 or buy_cond0
buy_close = (not USE_TRAILINGSTOP ? low <= buy_entry_price - sl: low <= buy_ts) or high>=buy_entry_price+tp//high>=last_traded_price + tp or low<=last_traded_price - sl //high >= hh or
sel_cond1 = crossunder(ma00, ma01) and (USE_TRADESESSION ? istradingsession : true)
sel_cond0 = crossunder(price, ma00) and ma00 < ma01 and (USE_TRADESESSION ? istradingsession : true)
sel_entry = sel_cond1 or sel_cond0
sel_close = (not USE_TRAILINGSTOP ? high >= sel_entry_price + sl : high >= sel_ts) or low<=sel_entry_price-tp//low<=last_traded_price - tp or high>=last_traded_price + sl //low <= ll or

strategy.entry('buy', long=strategy.long, qty=trade_size, comment='buy', when=buy_entry)
strategy.close('buy', when=buy_close)
strategy.entry('sell', long=strategy.short, qty=trade_size, comment='sell', when=sel_entry)
strategy.close('sell', when=sel_close)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-EMA-Golden-Cross-Breakthrough-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bull Market Tracking SystemPine Script · Breakout · 1h
- Dual Breakout Volatility Channel StrategyPine Script · Breakout · 1h
- Dual Moving Average Breakthrough StrategyPine Script · Breakout · 1d
- EMA MACD Quantitative Strategy With Dual Track Running and Leading the Market IndexPine Script · Breakout · 1d
- Kana Candle Breakout Strategy Based on Moving Average and Support ResistancePine Script · Breakout · 1h
- MA Trendline Breakthrough StrategyPine Script · Breakout · 1d