Strategy vault / Mean reversion
Dual Indicator Slight Reversal Trading Strategy
The Dual Indicator Slight Reversal Trading Strategy combines momentum and trend-following indicators for short-term trading. The strategy first generates trading signals using a reversal indicator, then combines it…
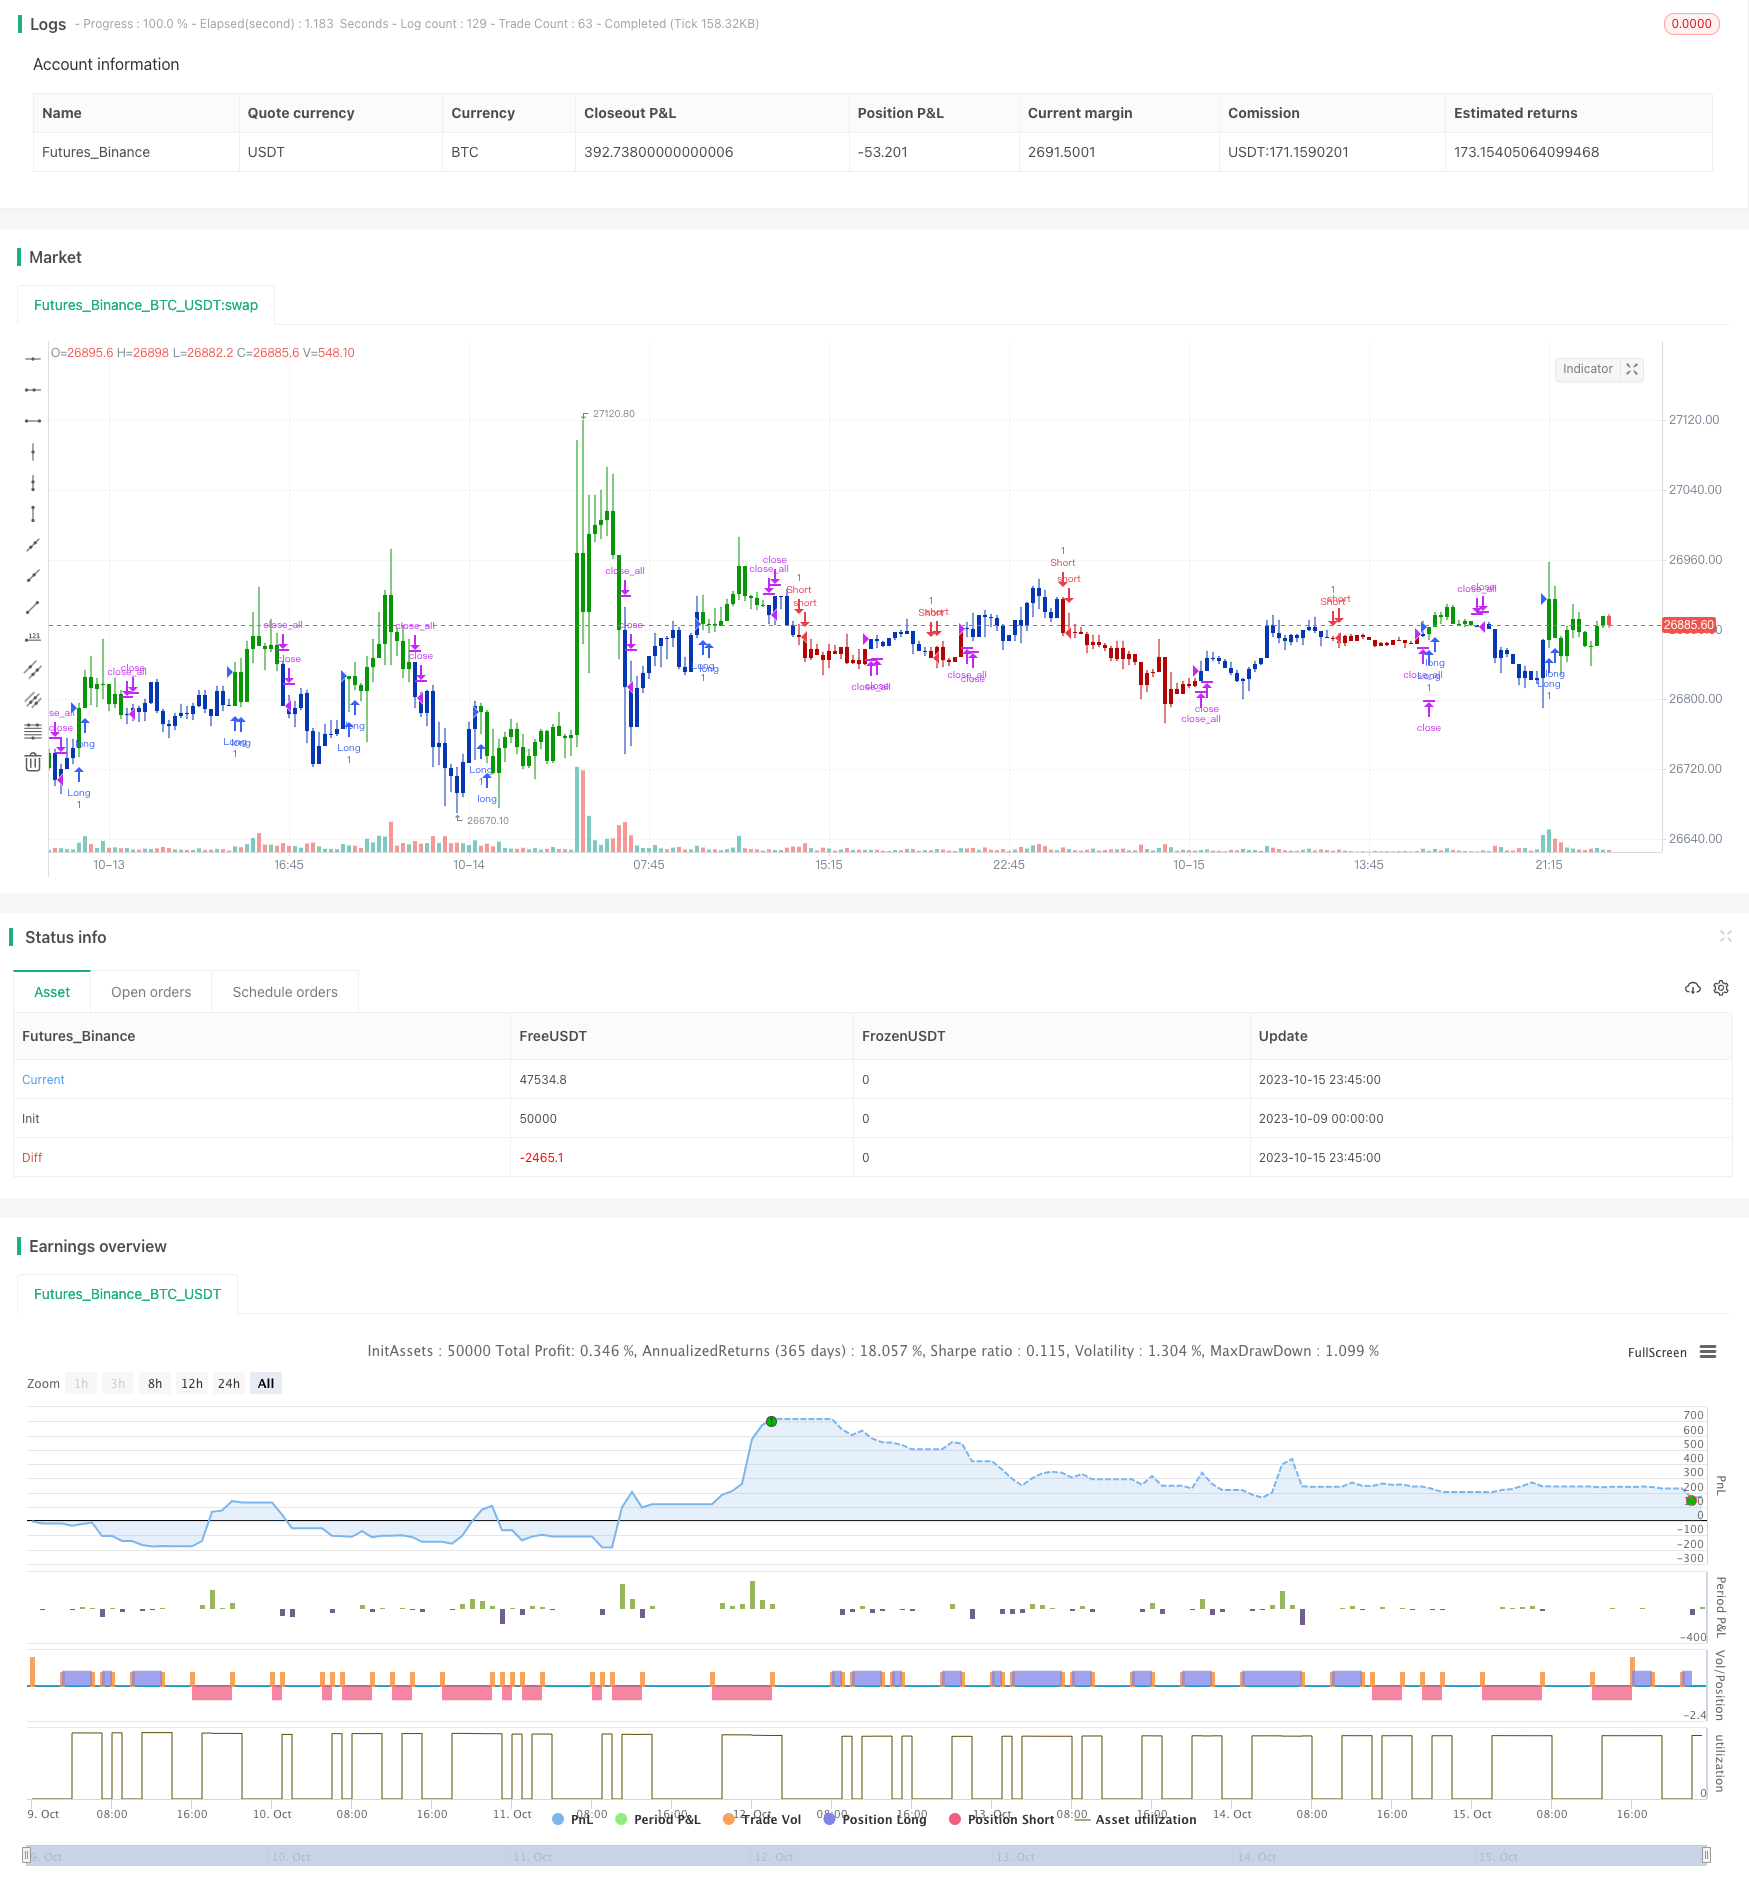
Overview
The Dual Indicator Slight Reversal Trading Strategy combines momentum and trend-following indicators for short-term trading. The strategy first generates trading signals using a reversal indicator, then combines it with a trend-following indicator to produce more reliable signals. It aims to capture short-term price reversals within the context of medium-term trends.
Principle
The strategy consists of two sub-strategies.
The first is the 123 Reversal strategy. It monitors if a peak reversal pattern occurs. Specifically, it will generate a long signal if the closing price of the prior two days drops and the current closing price is higher than the previous closing price, with the Stochastic slow line below 50. It will generate a short signal if the closing prices of the prior two days rise and the current closing price is lower than the previous closing price, with the Stochastic fast line above 50.
The second is the Ergodic indicator, which is a trend-following indicator identifying the direction of medium to long term trends. It incorporates the ideas of moving averages and MACD, using single exponential smoothed moving averages and MACD's fast and slow lines crossovers to generate trading signals.
The strategy combines the signals from the two sub-strategies. It will only open a position when the two sub-strategies generate consistent signals. That is, it only trades when there is a short-term slight reversal along with a strong medium to long term trend.
Advantages
Combining multiple indicators can effectively filter false signals and improve reliability.
Combining reversal and trend-following provides both short-term opportunities and avoids counter-trend trades.
The Stochastic parameter settings are quite robust to reduce whipsaws.
The smoothing parameters of the Ergodic indicator are reasonably set to better identify trends.
The trading frequency is appropriate, capturing adequate opportunities without overtrading.
Suitable for medium-term trading with flexible timeframes.
Risks
Reversal signals may produce false signals and need validation from trend indicators.
The low trading frequency may miss some short-term opportunities.
There could be reversals after reversals, requiring timely stop loss.
Inappropriate parameter settings may significantly impact results.
Relying too much on technical indicators risks overfitting.
Enhancement
Test different parameter settings to optimize sub-strategies.
Introduce more indicators to build multi-factor models.
Apply machine learning for dynamic parameter optimization.
Research different stop loss methods to control risks.
Study opportunity costs and adjust strategy trading frequency.
Test strategy robustness across different market regimes.
Conclusion
The Dual Indicator Slight Reversal Trading Strategy attempts to capture short-term reversal opportunities on medium-term timeframes using combinations of reversal and trend-following indicators. It can effectively filter false signals and control risks to some extent. However, issues like missing short-term opportunities, parameter sensitivity, and overfitting risks remain. Further enhancing stability and profitability can be achieved by incorporating more indicators, optimizing parameters, adjusting trading frequency, and testing across markets. Overall, the strategy represents a simple and practical quantitative approach worth exploring and applying.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | Length |
| v_input_2 | true | KSmoothing |
| v_input_3 | 3 | DLength |
| v_input_4 | 50 | Level |
| v_input_5 | 32 | r |
| v_input_6 | 5 | s |
| v_input_7 | 5 | u |
| v_input_8 | 3 | SmthLen |
| v_input_9 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2023-10-09 00:00:00
end: 2023-10-16 00:00:00
period: 15m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 28/07/2020
// This is combo strategies for get a cumulative signal.
//
// First strategy
// This System was created from the Book "How I Tripled My Money In The
// Futures Market" by Ulf Jensen, Page 183. This is reverse type of strategies.
// The strategy buys at market, if close price is higher than the previous close
// during 2 days and the meaning of 9-days Stochastic Slow Oscillator is lower than 50.
// The strategy sells at market, if close price is lower than the previous close price
// during 2 days and the meaning of 9-days Stochastic Fast Oscillator is higher than 50.
//
// Second strategy
// This is one of the techniques described by William Blau in his book "Momentum,
// Direction and Divergence" (1995). If you like to learn more, we advise you to
// read this book. His book focuses on three key aspects of trading: momentum,
// direction and divergence. Blau, who was an electrical engineer before becoming
// a trader, thoroughly examines the relationship between price and momentum in
// step-by-step examples. From this grounding, he then looks at the deficiencies
// in other oscillators and introduces some innovative techniques, including a
// fresh twist on Stochastics. On directional issues, he analyzes the intricacies
// of ADX and offers a unique approach to help define trending and non-trending periods.
//
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
Reversal123(Length, KSmoothing, DLength, Level) =>
    vFast = sma(stoch(close, high, low, Length), KSmoothing)
    vSlow = sma(vFast, DLength)
    pos = 0.0
    pos := iff(close[2] < close[1] and close > close[1] and vFast < vSlow and vFast > Level, 1,
	         iff(close[2] > close[1] and close < close[1] and vFast > vSlow and vFast < Level, -1, nz(pos[1], 0)))
	pos


EMDI(r,s,u,SmthLen) =>
    pos = 0
    xEMA = ema(close, r)
    xEMA_S = close - xEMA
    xEMA_U = ema(ema(xEMA_S, s), u)
    xSignal = ema(xEMA_U, u)
    pos := iff(xEMA_U > xSignal, 1,
    	     iff(xEMA_U < xSignal, -1, nz(pos[1], 0)))
    pos

strategy(title="Combo Backtest 123 Reversal & Ergodic MDI", shorttitle="Combo", overlay = true)
Length = input(14, minval=1)
KSmoothing = input(1, minval=1)
DLength = input(3, minval=1)
Level = input(50, minval=1)
//-------------------------
r = input(32, minval=1)
s = input(5, minval=1)
u = input(5, minval=1)
SmthLen = input(3, minval=1)
reverse = input(false, title="Trade reverse")
posReversal123 = Reversal123(Length, KSmoothing, DLength, Level)
posEMDI = EMDI(r,s,u,SmthLen)
pos = iff(posReversal123 == 1 and posEMDI == 1 , 1,
	   iff(posReversal123 == -1 and posEMDI == -1, -1, 0))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1 , 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close_all()
barcolor(possig == -1 ? #b50404: possig == 1 ? #079605 : #0536b3 )Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Indicator-Slight-Reversal-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Combo Trading Strategy Based on 123 Reversal and MACDPine Script · Mean reversion · 30m
- Intraday Single Candle Indicator Combo Short Term Trading StrategyPine Script · Mean reversion · 1d
- 15 MIN BTCUSDTPERP BOTPine Script · Mean reversion · 45m
- Hourly Fluctuation Trading StrategyPine Script · Mean reversion
- Multi factor Quantitative Trading Strategy 440526Pine Script · Mean reversion · 4h
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h