Dual Momentum Squeeze Trading System SMIUBS Indicator Combination Strategy
This strategy is a short-term trading system that combines the Squeeze Momentum Indicator (SMI) and Ultimate Buy/Sell (UBS) indicator. The strategy primarily captures short-selling opportunities by monitoring…
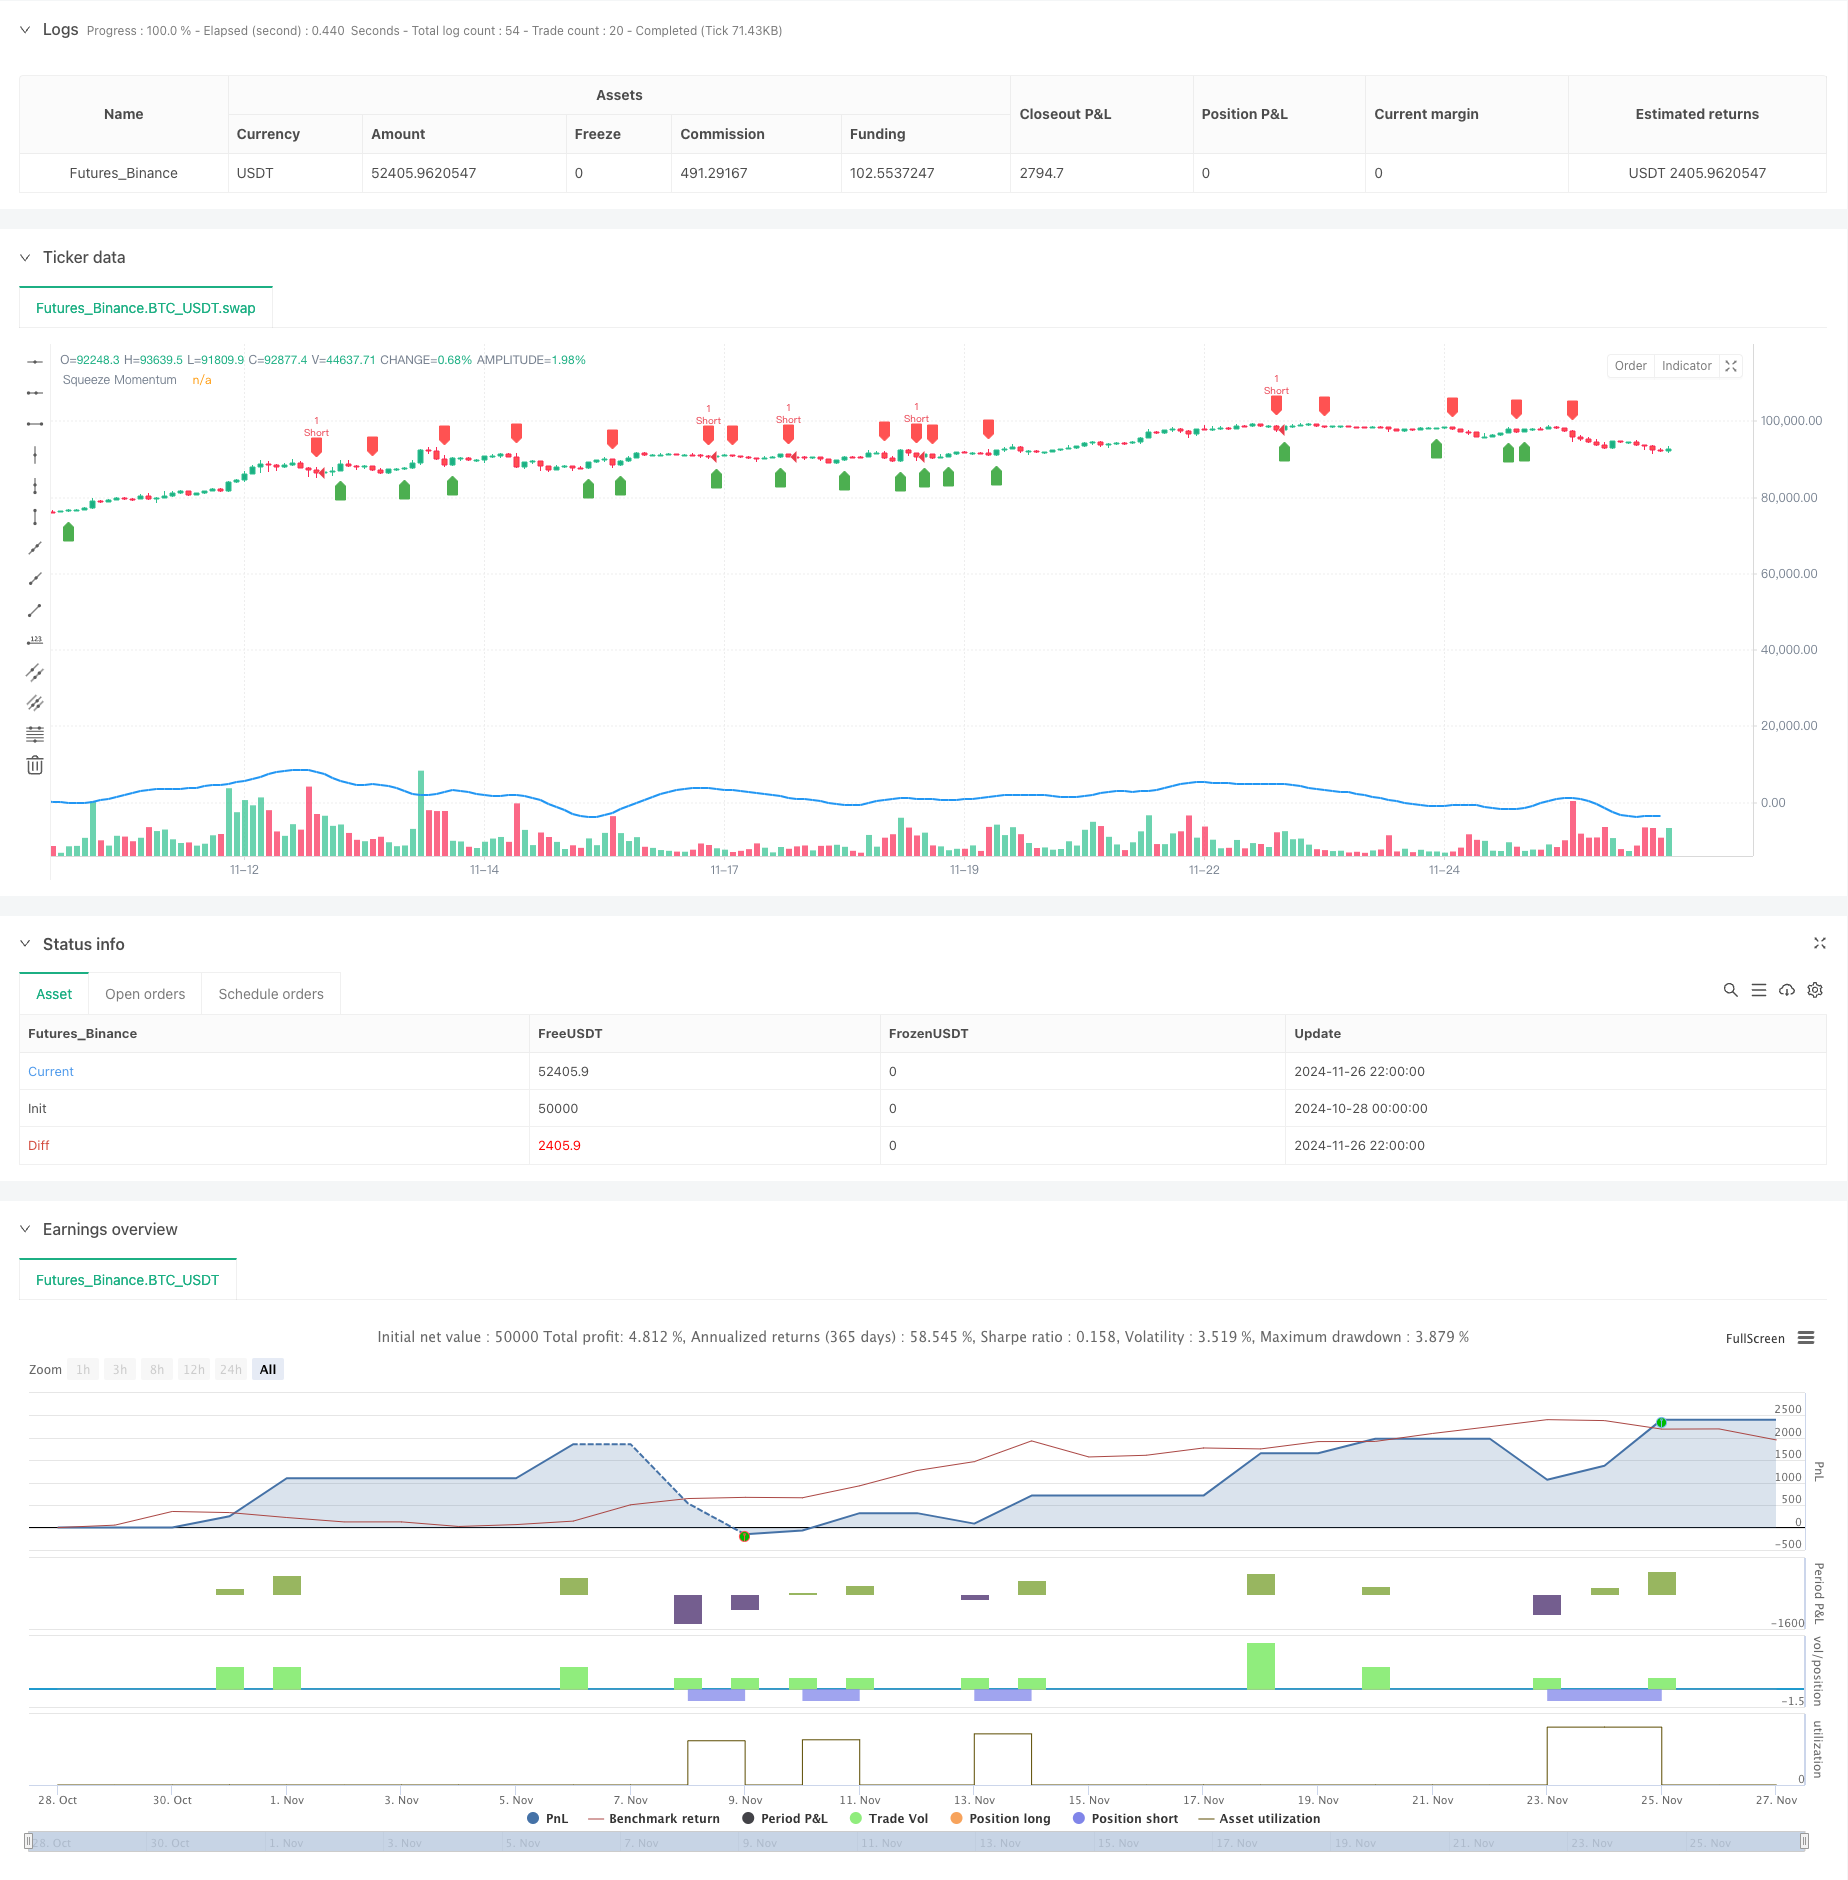
Overview
This strategy is a short-term trading system that combines the Squeeze Momentum Indicator (SMI) and Ultimate Buy/Sell (UBS) indicator. The strategy primarily captures short-selling opportunities by monitoring momentum changes and moving average crossover signals. The system incorporates a percentage-based stop-loss mechanism to protect capital while pursuing stable returns.
Strategy Principles
The core logic is based on the combination of two main indicators:
- Squeeze Momentum Indicator (SMI): Generates momentum signals by calculating the relationship between closing prices and high/low prices, smoothed with moving averages. When SMI turns from ascending to descending, it indicates weakening upward momentum and potential short opportunities.
- Ultimate Buy/Sell Indicator (UBS): Determines entry timing based on price crossovers with moving averages. A short signal is confirmed when price crosses below the moving average.
- The system automatically enters short positions upon signal confirmation, setting a 0.4% profit target and 2.5% stop-loss level for effective risk control.
Strategy Advantages
- Dual Signal Confirmation: Enhances signal reliability through the resonance of two independent indicators.
- Comprehensive Risk Management: Clear profit-taking and stop-loss conditions effectively control risk per trade.
- Adjustable Parameters: Key parameters like SMI length, smoothing period, and UBS period can be optimized for different market conditions.
- High Automation: Clear strategy logic facilitates automated trading implementation.
Strategy Risks
- False Breakout Risk: Frequent false signals may occur in ranging markets.
- Trend Dependency: Strategy performs better in trending markets but may face frequent stops in sideways markets.
- Parameter Sensitivity: Different parameter settings can lead to significant performance variations.
- Slippage Impact: Actual execution prices may deviate significantly from signal prices during high volatility.
Optimization Directions
- Add Market Environment Filters: Incorporate volatility or trend strength indicators to adjust strategy parameters in different market conditions.
- Optimize Stop-Loss Mechanism: Consider implementing dynamic stops, such as trailing stops or ATR-based stops.
- Add Time Filters: Avoid high volatility periods and major news release times.
- Implement Position Sizing: Dynamically adjust position size based on signal strength and market volatility.
Summary
The strategy constructs a relatively complete short-selling system by combining squeeze momentum and ultimate buy/sell technical indicators. Its strengths lie in high signal reliability and clear risk control, though it shows strong dependence on market conditions. Through improvements in market environment filtering and stop-loss optimization, the strategy's stability and profitability can be further enhanced.
Source Pine Script
/*backtest
start: 2024-10-28 00:00:00
end: 2024-11-27 00:00:00
period: 2h
basePeriod: 2h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © algostudio
// Code Generated using PineGPT - www.marketcalls.in

//@version=5
strategy("Squeeze Momentum and Ultimate Buy/Sell with Stop Loss", overlay=true, process_orders_on_close = false)

// Input settings
smiLength = input.int(20, title="SMI Length")
smiSmoothing = input.int(5, title="SMI Smoothing")
ultBuyLength = input.int(14, title="Ultimate Buy/Sell Length")
stopLossPerc = input.float(2.5, title="Stop Loss Percentage", step=0.1) / 100

// Define Squeeze Momentum logic
smi = ta.sma(close - ta.lowest(low, smiLength), smiSmoothing) - ta.sma(ta.highest(high, smiLength) - close, smiSmoothing)
squeezeMomentum = ta.sma(smi, smiSmoothing)
smiUp = squeezeMomentum > squeezeMomentum[1]
smiDown = squeezeMomentum < squeezeMomentum[1]

// Define Ultimate Buy/Sell Indicator logic (you can customize the conditions)
ultimateBuy = ta.crossover(close, ta.sma(close, ultBuyLength))
ultimateSell = ta.crossunder(close, ta.sma(close, ultBuyLength))


// Trading logic: Short entry (Squeeze Momentum from green to red and Ultimate Sell signal)
shortCondition = smiDown and ultimateSell
if (shortCondition)
    strategy.entry("Short", strategy.short)

//Set short target (exit when price decreases by 0.2%)
shortTarget = strategy.position_avg_price * 0.996

// Set stop loss for short (5% above the entry price)
shortStop = strategy.position_avg_price * (1 + stopLossPerc)

// Exit logic for short
if (strategy.position_size < 0)
    strategy.exit("Exit Short", "Short", limit=shortTarget, stop=shortStop)

// Plot the Squeeze Momentum for reference
plot(squeezeMomentum, color=color.blue, linewidth=2, title="Squeeze Momentum")

// Optional: Plot signals on the chart
plotshape(series=ultimateBuy, location=location.belowbar, color=color.green, style=shape.labelup, title="Ultimate Buy Signal")
plotshape(series=ultimateSell, location=location.abovebar, color=color.red, style=shape.labeldown, title="Ultimate Sell Signal")

// For more tutorials on Tradingview Pinescript visit https://www.marketcalls.in/category/tradingview
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Momentum-Squeeze-Trading-System-SMIUBS-Indicator-Combination-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- Momentum Strategy Based on DEMA and EMA Crossover with ATR Volatility FilterPine Script · Momentum · 1h
- Momentum Trend Following SuperTrend and Stochastic Crossover StrategyPine Script · Momentum · 2d
- Momentum Trend Optimization Combination StrategyPine Script · Momentum · 1h
- Moving Average Candle Regression StrategyPine Script · Momentum · 15m
- Multi EMA Trend Momentum Trading Strategy with Risk Management SystemPine Script · Momentum · 1h