Strategy vault / Trend following
Dual Moving Average Bollinger Band Trend Tracking Strategy 436249
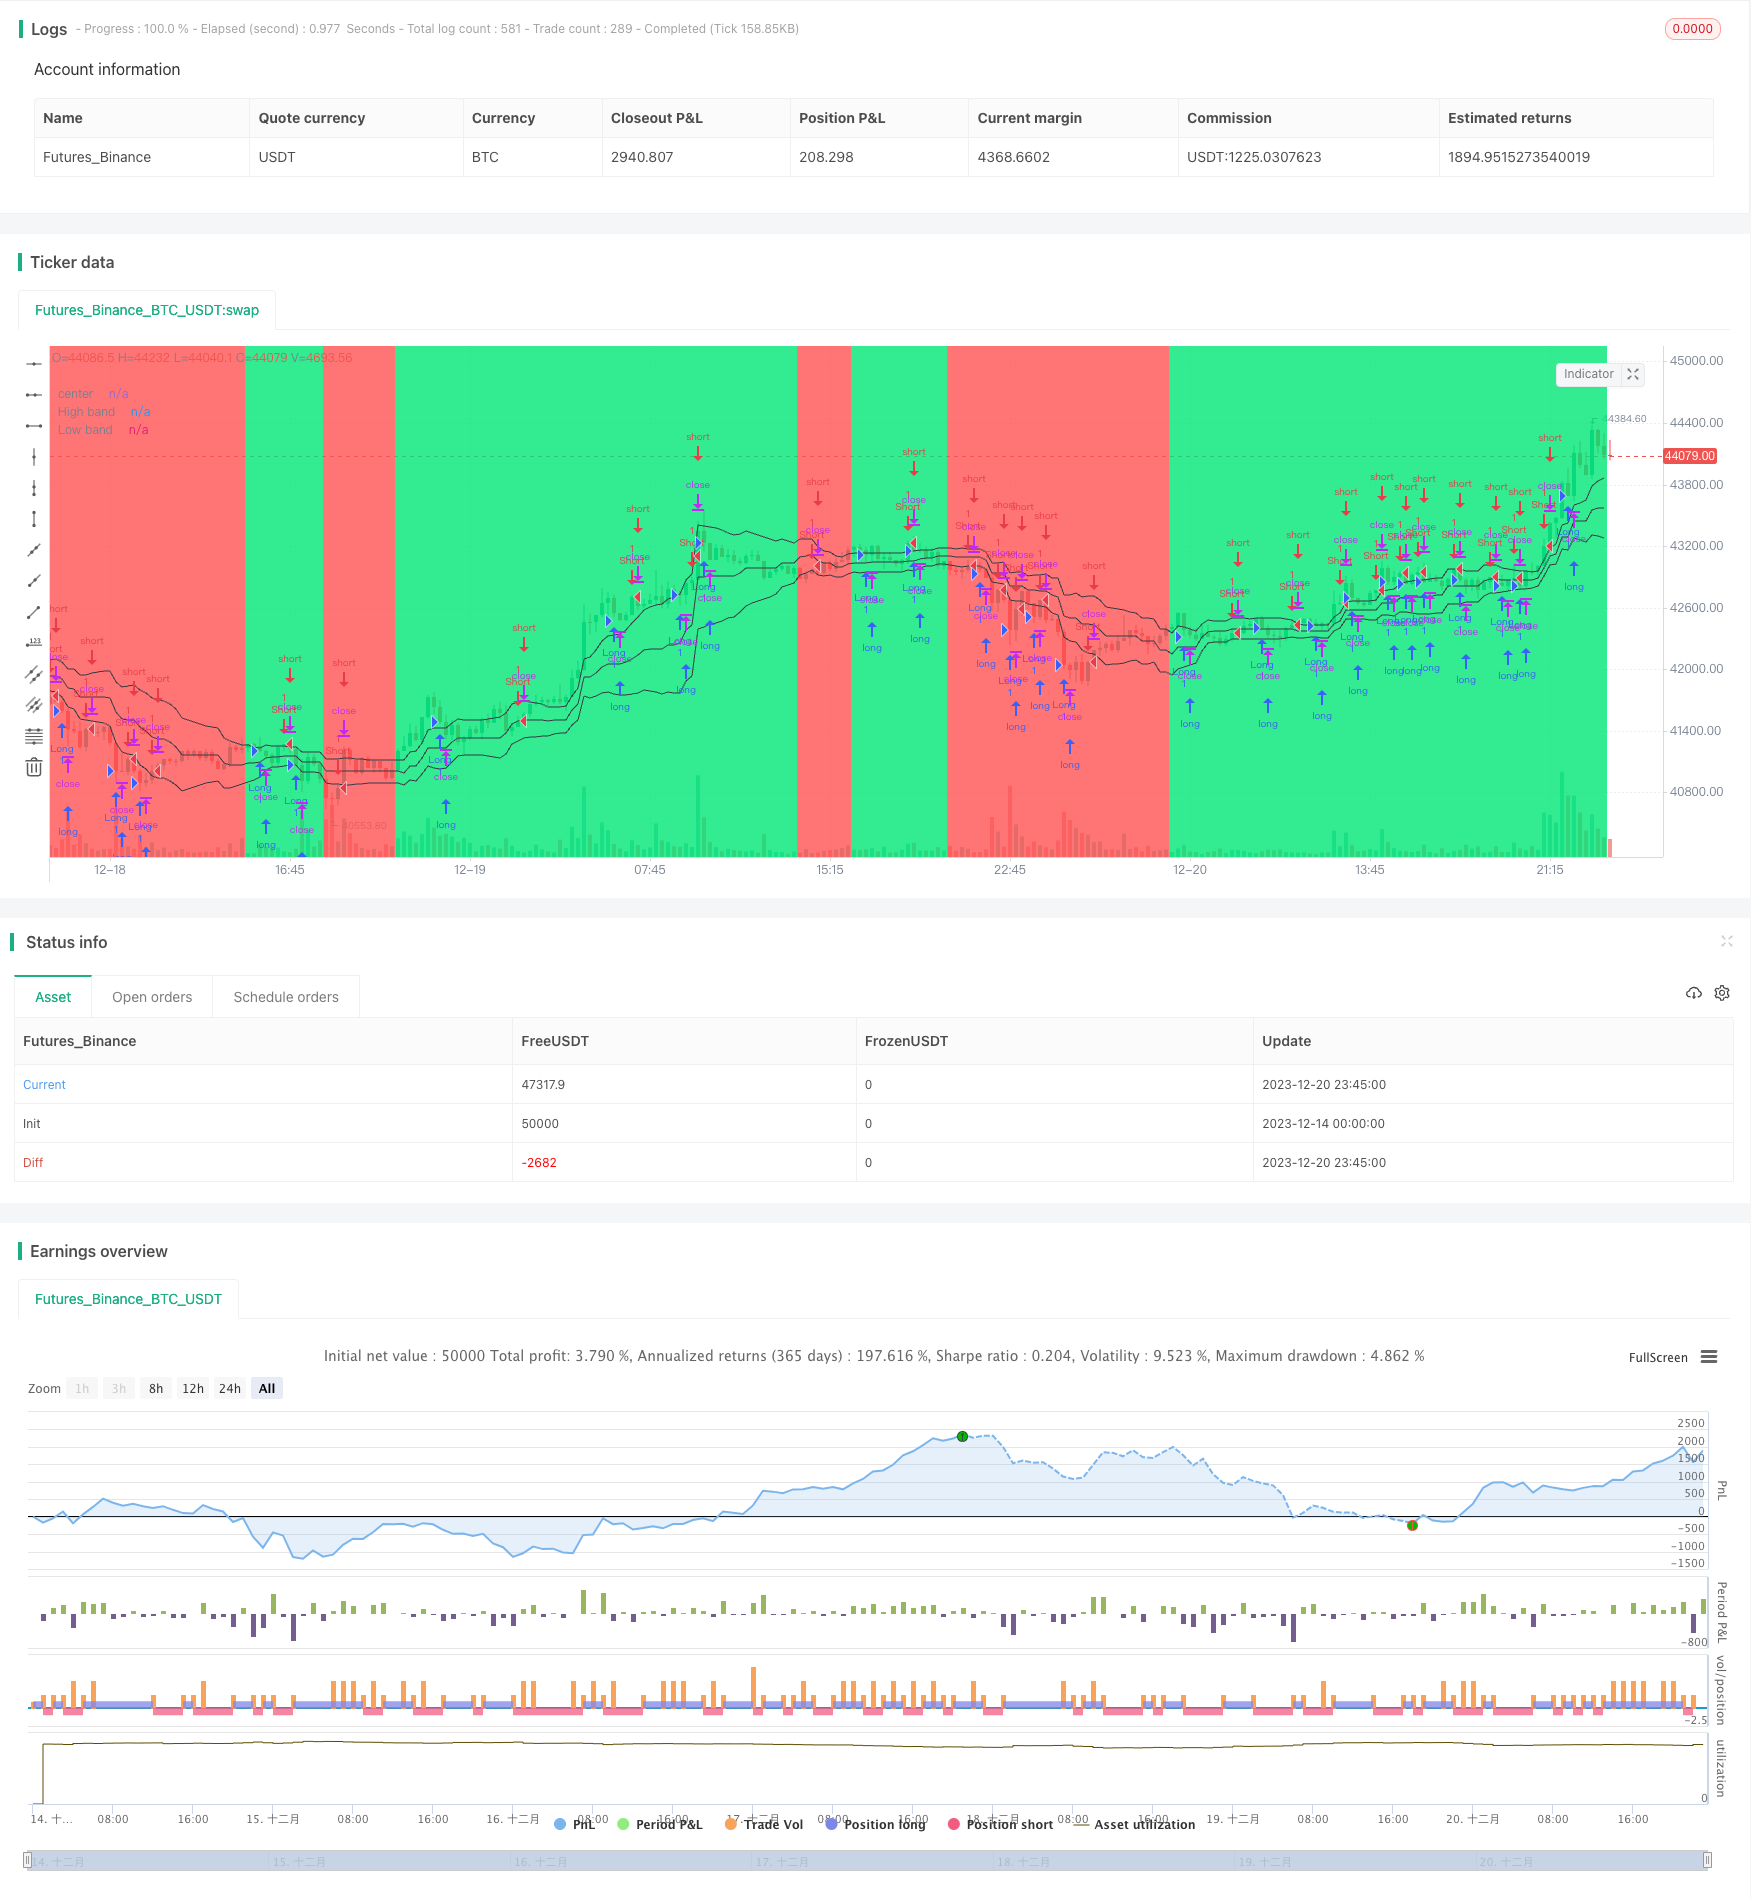
This strategy utilizes a combination of Bollinger Bands and moving averages for trend identification and entry. It leverages the trend recognition capability of Bollinger Bands and the filtering effect of moving…
Overview
This strategy utilizes a combination of Bollinger Bands and moving averages for trend identification and entry. It leverages the trend recognition capability of Bollinger Bands and the filtering effect of moving averages to effectively identify market trend directions for entry in trending markets.
Strategy Logic
Calculate Bollinger Channel to determine market trend direction
- Use highest high and lowest low to calculate channel bands
- Channel middle band is average of high and low
- Determine trend direction based on price location within channel
Compute bullish candle body size for stop loss and reversal signals
- Bullish candle body is absolute value of close minus open
- Compute N-period average of candle bodies, compare to current body for stop loss and reversal
Enter trades in channel direction upon trend confirmation
- Long entries near lower band in uptrends
- Short entries near upper band in downtrends
Utilize moving averages for filtration to avoid false signals
- Compute N-period moving average of closing price
- Generate signals only on moving average breakthroughs
Advantages
Systematic trend identification combining bands and moving averages
Bands clearly identify price channels and trend direction. Moving averages filter noise. Combination enables robust trend detection immune to sporadic market shocks.
Effective risk control via candle body stop loss
Comparing current candle body to historical average detects trend reversal for stop loss and position reduction. Effectively controls strategy risk.
Clear quantitative entry and stop loss rules
Strict moving average and channel direction requirements for entry. Candle body size stop loss rule. Makes entire system entry and exits clear and systematic.
Risk Analysis
Potential losses in range-bound markets
Whip-sawing price oscillating around bands can cause repeated minor losses. Position sizing should be reduced to limit loss impact.
Premature stop loss in strong trends
Short-term retracements can trigger stops in strong uptrends/downtrends. Stop loss width should be relaxed to ride trends.
Erroneous signals from poor parameter tuning
Suboptimal moving average and bands parameters can cause spurious signals. Parameters should be optimized for signal reliability.
Enhancement Opportunities
Optimize moving average lookback period
Adjust period to reduce smoothing for quicker trend change detection.
Test alternative stop loss mechanisms
Evaluate trailing stops, ATR stops etc. to find optimal system.
Incorporate machine learning models
Train models on extensive historical data to augment trend and signal prediction.
Conclusion
This strategy balances trend identification and risk control using Bollinger Bands and moving averages. The systematic quantitative approach with clear entry/exit rules enables effective reward capture with controlled risk. Further improvements via parameter tuning and machine learning integration will enhance robustness.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Long |
| v_input_2 | true | Short |
| v_input_3 | false | take, % |
| v_input_4 | false | Counter-trend entry |
| v_input_5 | 20 | Period |
| v_input_6 | true | Show Bands |
| v_input_7 | true | Show Background |
Source Pine Script
/*backtest
start: 2023-12-14 00:00:00
end: 2023-12-21 00:00:00
period: 15m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/


//@version=2
strategy("Noro's Bands Scalper Strategy v1.3", shorttitle = "Scalper str 1.3", overlay=true, default_qty_type = strategy.percent_of_equity, default_qty_value=100.0, pyramiding=0)

//Settings
needlong = input(true, defval = true, title = "Long")
needshort = input(true, defval = true, title = "Short")
takepercent = input(0, defval = 0, minval = 0, maxval = 1000, title = "take, %")
needct = input(false, defval = false, title = "Counter-trend entry")
len = input(20, defval = 20, minval = 2, maxval = 200, title = "Period")
needbb = input(true, defval = true, title = "Show Bands")
needbg = input(true, defval = true, title = "Show Background")
src = close

//PriceChannel 1
lasthigh = highest(src, len)
lastlow = lowest(src, len)
center = (lasthigh + lastlow) / 2

//Distance
dist = abs(src - center)
distsma = sma(dist, len)
hd = center + distsma
ld = center - distsma
hd1 = center + distsma / 2
ld1 = center - distsma / 2

//Trend
trend = close < ld and high < center ? -1 : close > hd and low > center ? 1 : trend[1]

//Lines
colo = needbb == false ? na : black
plot(hd, color = colo, linewidth = 1, transp = 0, title = "High band")
plot(center, color = colo, linewidth = 1, transp = 0, title = "center")
plot(ld, color = colo, linewidth = 1, transp = 0, title = "Low band")

//Background
col = needbg == false ? na : trend == 1 ? lime : red
bgcolor(col, transp = 80)

//Body
body = abs(close - open)
smabody = ema(body, 30)
candle = high - low

//Engulfing
min = min(open, close)
max = max(open, close)
bar = close > open ? 1 : close < open ? -1 : 0
upeng = bar == 1 and bar[1] == -1 and min >= min[1] and max <= max[1] ? 1 : 0
dneng = bar == -1 and bar[1] == 1 and min >= min[1] and max <= max[1] ? 1 : 0

//Signals
up7 = trend == 1 and ((bar == -1 and bar[1] == -1) or (body > smabody and close < open)) ? 1 : 0
dn7 = trend == 1 and bar == 1 and bar[1] == 1 and close > strategy.position_avg_price * (100 + takepercent) / 100 ? 1 : 0
up8 = trend == -1 and bar == -1 and bar[1] == -1 and close < strategy.position_avg_price * (100 - takepercent) / 100 ? 1 : 0
dn8 = trend == -1 and ((bar == 1 and bar[1] == 1) or (body > smabody and close > open)) ? 1 : 0

if up7 == 1 or up8 == 1
    strategy.entry("Long", strategy.long, needlong == false ? 0 : trend == -1 and needct == false ? 0 : na)

if dn7 == 1 or dn8 == 1
strategy.entry("Short", strategy.short, needshort == false ? 0 : trend == 1 and needct == false ? 0 : na)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Bollinger-Band-Trend-Tracking-Strategy-436249.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual Moving Average Crossover Dynamic Position Optimization Strategy with EMA Cross Signal SystemPine Script · Trend following · 1h
- EMA Cross Trend Following Strategy with SMA Stop Loss and Re Entry MechanismPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- Adaptive Trend Following StrategyPine Script · Trend following · 4h