Strategy vault / Trend following
Dual Moving Average Channel Trend Following Strategy
This strategy is a trend-following system based on dual moving averages and channels. It utilizes crossover signals from short-term and long-term moving averages, combined with channels formed by exponential moving…
Overview
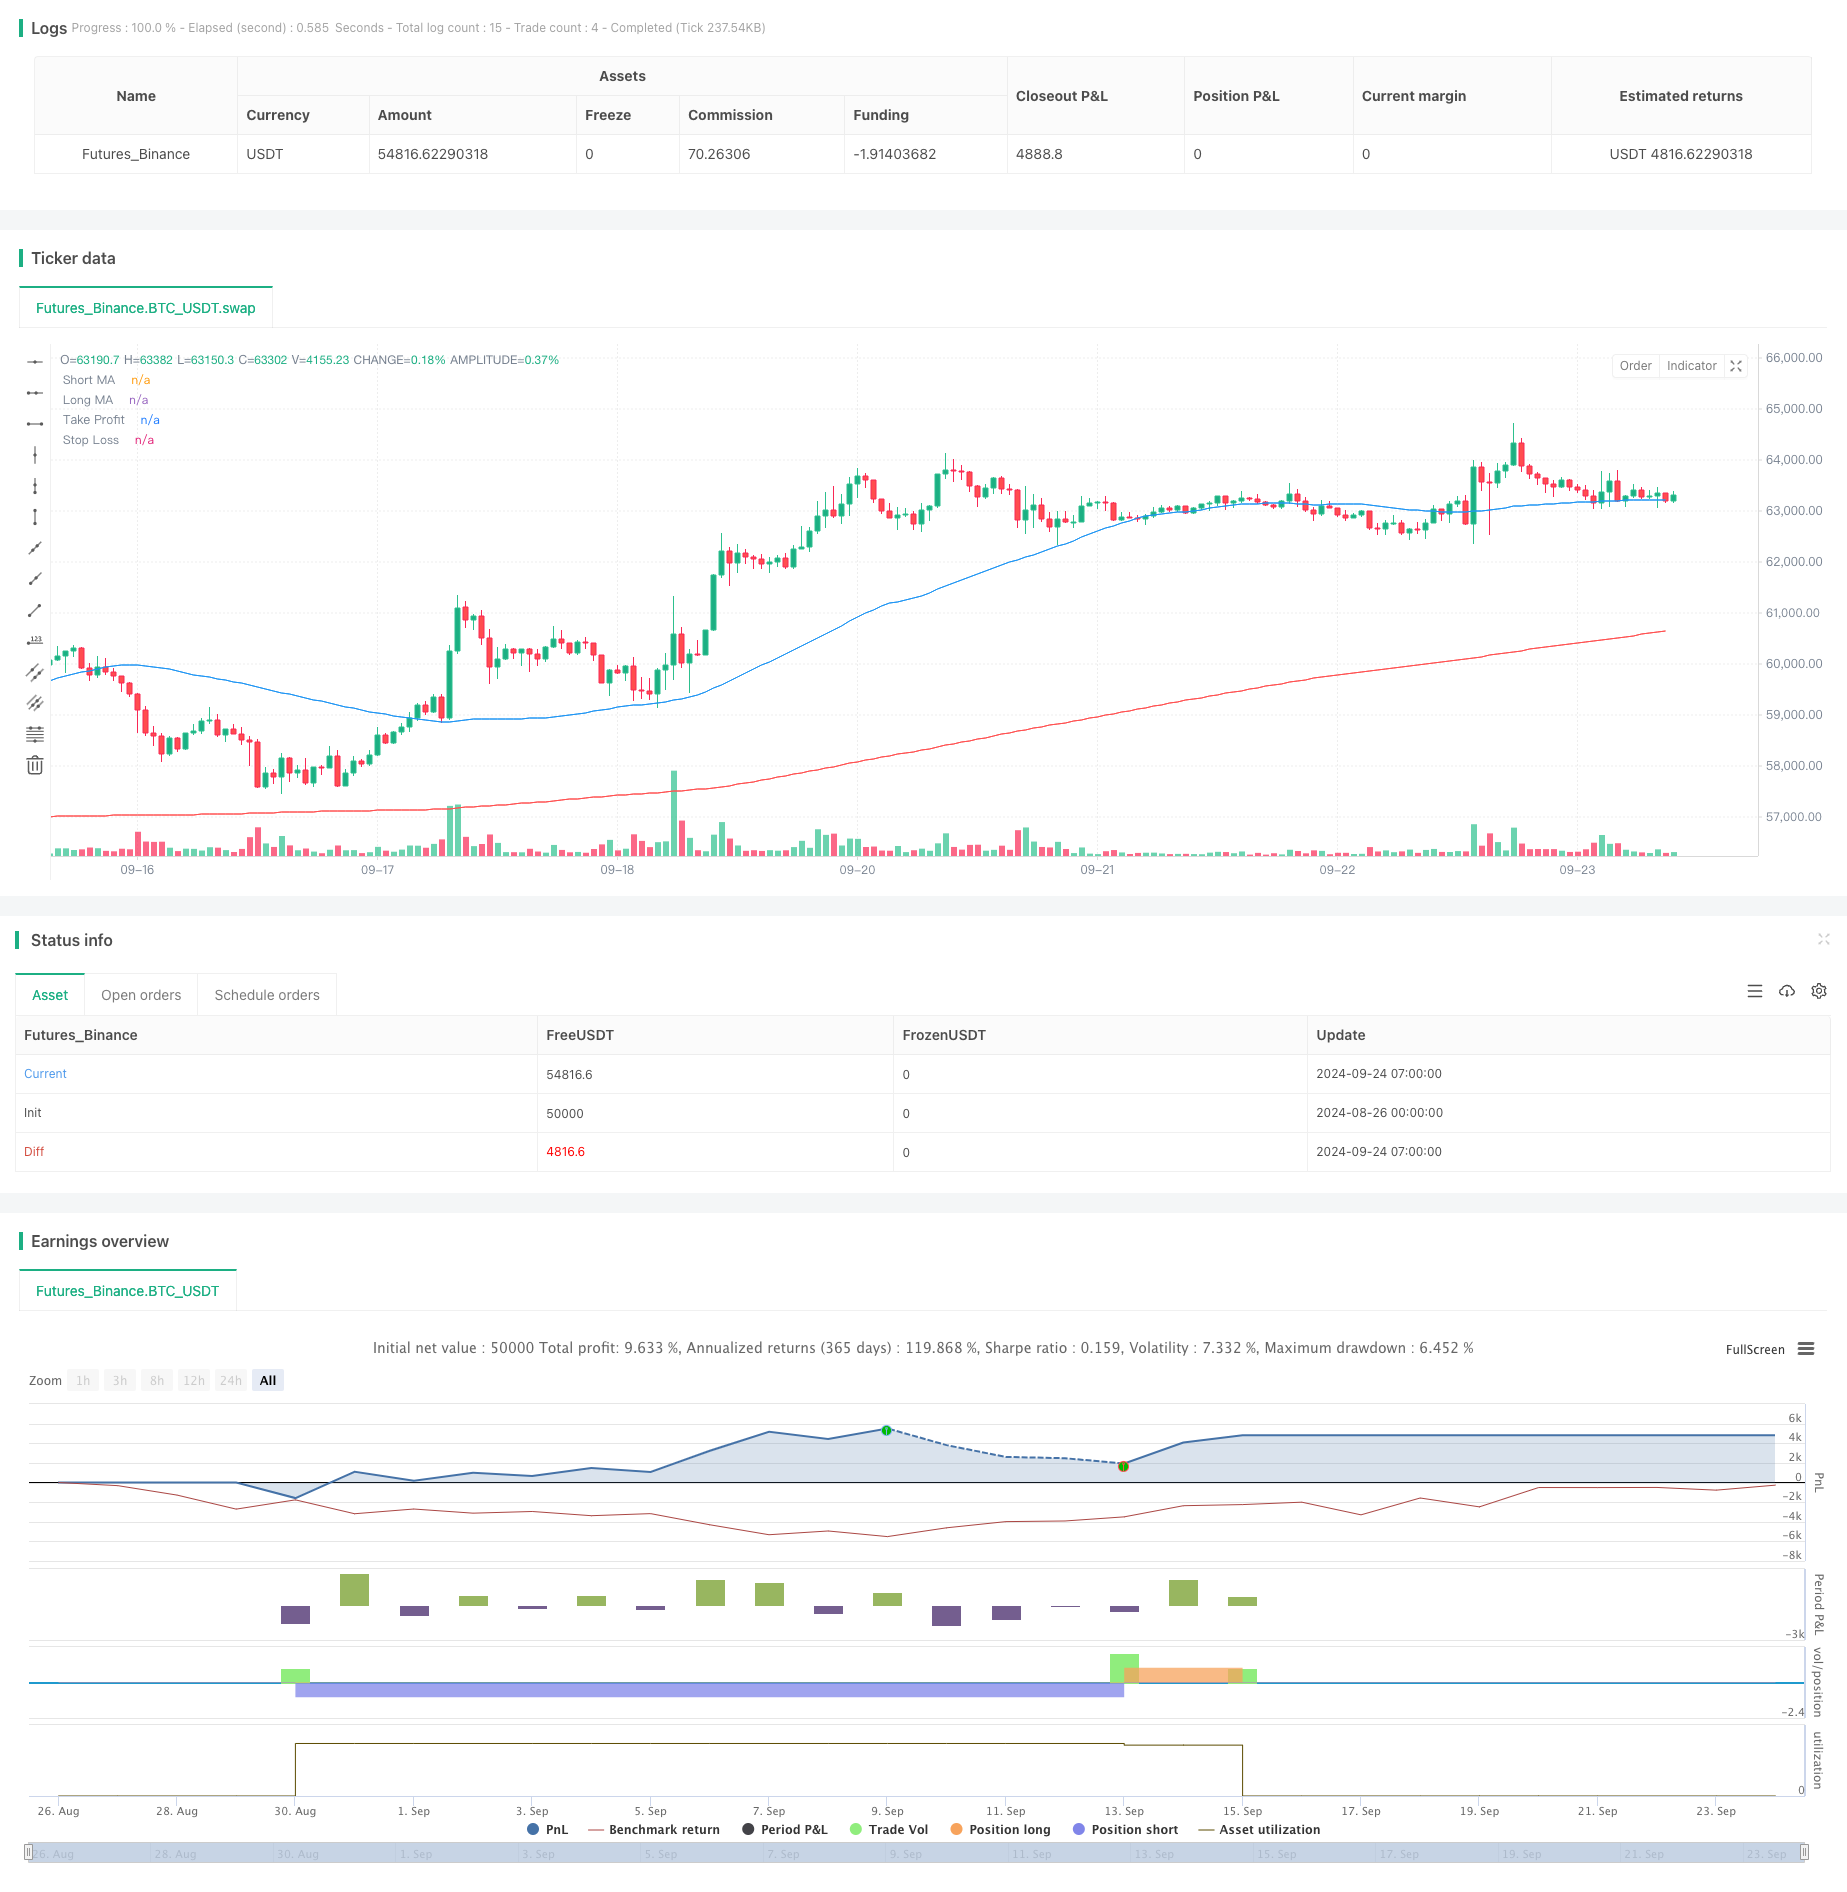
This strategy is a trend-following system based on dual moving averages and channels. It utilizes crossover signals from short-term and long-term moving averages, combined with channels formed by exponential moving averages (EMAs), to capture market trends and execute trades. The strategy is applicable to both long and short positions, employing stop-loss and take-profit mechanisms for risk and profit management.
Strategy Principle
The core logic of the strategy includes the following key components:
- Two Simple Moving Averages (SMAs) as primary trend indicators: 55-period and 300-period SMAs.
- Two Exponential Moving Averages (EMAs) forming a trading channel: 576-period and 676-period EMAs.
- Long entry signals are triggered when the short-term SMA crosses above the long-term SMA or EMA; short entry signals occur when the short-term SMA crosses below the long-term SMA or EMA.
- Fixed-point stop-loss and take-profit strategy, with stop-loss set at 1/70 of the entry price and take-profit at 1/140 of the entry price.
- A trailing stop mechanism is activated when profit reaches 300 points to protect accumulated gains.
- The strategy includes exit conditions, such as automatic position closure when price hits stop-loss or take-profit levels.
Strategy Advantages
- Multi-indicator integration: Combining multiple moving averages and EMA channels enhances trend identification accuracy.
- Bidirectional trading: The strategy can profit in both bullish and bearish markets, improving capital efficiency.
- Risk management: Employs fixed-point stop-loss and take-profit, effectively controlling risk for each trade.
- Profit protection: Utilizes trailing stop mechanism to lock in partial profits during sustained trends.
- Flexibility: Strategy parameters are adjustable to adapt to different market conditions.
Strategy Risks
- Ranging market risk: In sideways markets, frequent false signals may lead to consecutive losses.
- Slippage risk: In highly volatile markets, actual execution prices may significantly deviate from ideal prices.
- Overtrading: Frequent trading signals may result in excessive transaction costs.
- Parameter sensitivity: Strategy performance may be highly sensitive to parameter settings, potentially requiring frequent adjustments for different market environments.
Strategy Optimization Directions
- Incorporate volatility indicators: Consider adding ATR (Average True Range) to dynamically adjust stop-loss and take-profit levels, adapting to varying market volatility.
- Enhance trend strength filtering: Introduce ADX (Average Directional Index) to filter out weak trend signals, reducing losses from false breakouts.
- Optimize entry timing: Consider combining RSI (Relative Strength Index) or MACD (Moving Average Convergence Divergence) to improve entry timing and increase win rate.
- Refine money management: Implement dynamic position sizing, adjusting trade sizes based on account equity and market volatility.
- Extend backtesting period: Conduct longer-term backtests to verify strategy stability across different market environments.
Conclusion
This dual moving average channel trend-following strategy provides a comprehensive trading system by combining multiple technical indicators. It not only captures major trends but also incorporates risk management and profit protection mechanisms. While some potential risks exist, through continuous optimization and parameter adjustment, the strategy has the potential to perform well under various market conditions. Future optimization should focus on improving signal quality, enhancing risk management, and increasing strategy adaptability.
Source Pine Script
/*backtest
start: 2024-08-26 00:00:00
end: 2024-09-24 08:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("RC BTC Vegas 5min free ", overlay=true )

// Define input parameters
short_ma_length = input.int(55, title="Short MA Length")
long_ma_length = input.int(300, title="Long MA Length")

ema1_length = input.int(576, title="EMA 1 Length")
ema2_length = input.int(676, title="EMA 2 Length")
// Calculate moving average
short_ma = ta.sma(close, short_ma_length)
long_ma = ta.sma(close, long_ma_length)
ema1 = ta.ema(close, ema1_length)
ema2 = ta.ema(close, ema2_length)
// Identify buy and sell signals
enter_long = ta.crossover(short_ma +5 , ema1)
enter_long2 = ta.crossover(short_ma +5 , long_ma)
enter_long3 =ta.crossover(long_ma+5  , ema1)

exit_long = ta.crossunder(short_ma -5, ema1)
exit_long2 = ta.crossunder(short_ma -5, long_ma)
exit_long3 = ta.crossunder(long_ma-5 , ema1)

// Record entry price
var float long_stop_loss = na
var float long_take_profit = na

if (enter_long or exit_long  )
    long_stop_loss := close

if (enter_long or exit_long)
    long_take_profit := close

// Calculate stop-loss and take-profit points based on entry price
stop_loss_points = long_stop_loss /70
take_profit_points  = long_take_profit /140
// Set stop loss and stop loss of fixed points
Along_stop_loss = close - stop_loss_points
Along_take_profit = close + take_profit_points
short_stop_loss = close + stop_loss_points
short_take_profit = close - take_profit_points

// Check whether the position profit has reached300o'clock/point
long_profit_target_reached = (strategy.position_size > 0 and (close - strategy.position_avg_price) >= take_profit_points)
short_profit_target_reached = (strategy.position_size < 0 and (strategy.position_avg_price - close) >= take_profit_points)

// Instant stop loss and take profit check
long_stop_loss_hit = (strategy.position_size > 0 and close <= strategy.position_avg_price - stop_loss_points)
long_take_profit_hit = (strategy.position_size > 0 and close >= strategy.position_avg_price + take_profit_points)
short_stop_loss_hit = (strategy.position_size < 0 and close >= strategy.position_avg_price + stop_loss_points)
short_take_profit_hit = (strategy.position_size < 0 and close <= strategy.position_avg_price - take_profit_points)
// Previous candleKCheck take profit and stop loss of the bar
long_stop_loss_hit_prev = (strategy.position_size > 0 and low[1] <= strategy.position_avg_price - stop_loss_points)
long_take_profit_hit_prev = (strategy.position_size > 0 and high[1]>= strategy.position_avg_price + take_profit_points)
short_stop_loss_hit_prev = (strategy.position_size < 0 and high[1] >= strategy.position_avg_price + stop_loss_points)
short_take_profit_hit_prev = (strategy.position_size < 0 and low[1] <= strategy.position_avg_price - take_profit_points)

// Create alert conditions
alertcondition(long_stop_loss_hit, title="Long Stop Loss Hit", message="Long position stop loss hit")
alertcondition(long_take_profit_hit, title="Long Take Profit Hit", message="Long position take profit hit")
alertcondition(short_stop_loss_hit, title="Short Stop Loss Hit", message="Short position stop loss hit")
alertcondition(short_take_profit_hit, title="Short Take Profit Hit", message="Short position take profit hit")
// Moving stop-loss input
initialProfitLevel = input.float(9, title="Initial Profit Level (points)")
trailingStopIncrement = input.float(3, title="Trailing Stop Increment (points)")
if (close - long_take_profit >= 150)
    strategy.exit("Move Buy to Break-even", from_entry="Buy", trail_price=close+5 , trail_offset=5  )
if (close - long_take_profit <= -150)
    strategy.exit("Move Sell to Break-even", from_entry="Sell", trail_price=close-5 , trail_offset=5)

// Execute long trade
if (enter_long or enter_long2  )
    strategy.entry("Buy", strategy.long, qty=1 , comment = "go long")

if (long_stop_loss_hit or long_take_profit_hit  )
    strategy.close("Buy",comment = "Close Buy Position")
//Only open short positions following a death cross
if (exit_long  or exit_long2  )
    strategy.entry("Sell" ,strategy.short, qty=1 , comment = "go short")

// Execute short trade
if ( short_take_profit_hit or short_stop_loss_hit )
    strategy.close("Sell",comment = "Close Sell Position")

// Draw moving average
plot(short_ma, title="Short MA", color=color.blue)
plot(long_ma, title="Long MA", color=color.red)

// Draw entry and exit points
plotshape(series=enter_long, location=location.belowbar, color=color.green, style=shape.labelup, text="go long")
plotshape(series=exit_long , location=location.abovebar, color=color.red, style=shape.labeldown, text="go short")
plotshape(series=long_take_profit_hit , location=location.abovebar, color=color.yellow, style=shape.labeldown, text="Take Profit on Buy")
plotshape(series=short_take_profit_hit , location=location.abovebar, color=color.yellow, style=shape.labeldown, text="Take Profit on Sell")
plotshape(series=short_stop_loss_hit , location=location.abovebar, color=color.black, style=shape.labeldown, text="Stop Loss on Sell")
plotshape(series=long_stop_loss_hit , location=location.abovebar, color=color.black, style=shape.labeldown, text="Stop Loss on Buy")

// Draw take profit and stop loss points
plot(series=enter_long ? Along_take_profit : na, title="Take Profit", color=color.green, linewidth=2, style=plot.style_linebr)
plot(series=enter_long ? Along_stop_loss : na, title="Stop Loss", color=color.red, linewidth=2, style=plot.style_linebr)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-09-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Channel-Trend-Following-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Factor Trend Price Action Strategy with Dynamic Risk Management SystemPine Script · Trend following · 2h
- Multi Indicator Dynamic Trend Following Strategy Based on EMA and SMAPine Script · Trend following · 1d
- Trend Tracking and Short term Trading Strategy Based on ADX IndicatorPine Script · Trend following · 1d
- DPO EMA Trend Crossover Quantitative Strategy ResearchPine Script · Trend following · 1d
- Dual EMA Crossover Trend Following Strategy with ATR and ADX FiltersPine Script · Trend following · 1d
- Multi Period Trend Confirmation Dynamic Risk Control Quantitative Trading StrategyPine Script · Trend following · 1h