Strategy vault / Trend following
Dual Moving Average Crossover Strategy 429464
This strategy generates trading signals based on the difference between two moving averages with different timeframes. It calculates a faster SMA and a slower SMA, and produces buy signals when the fast SMA crosses…
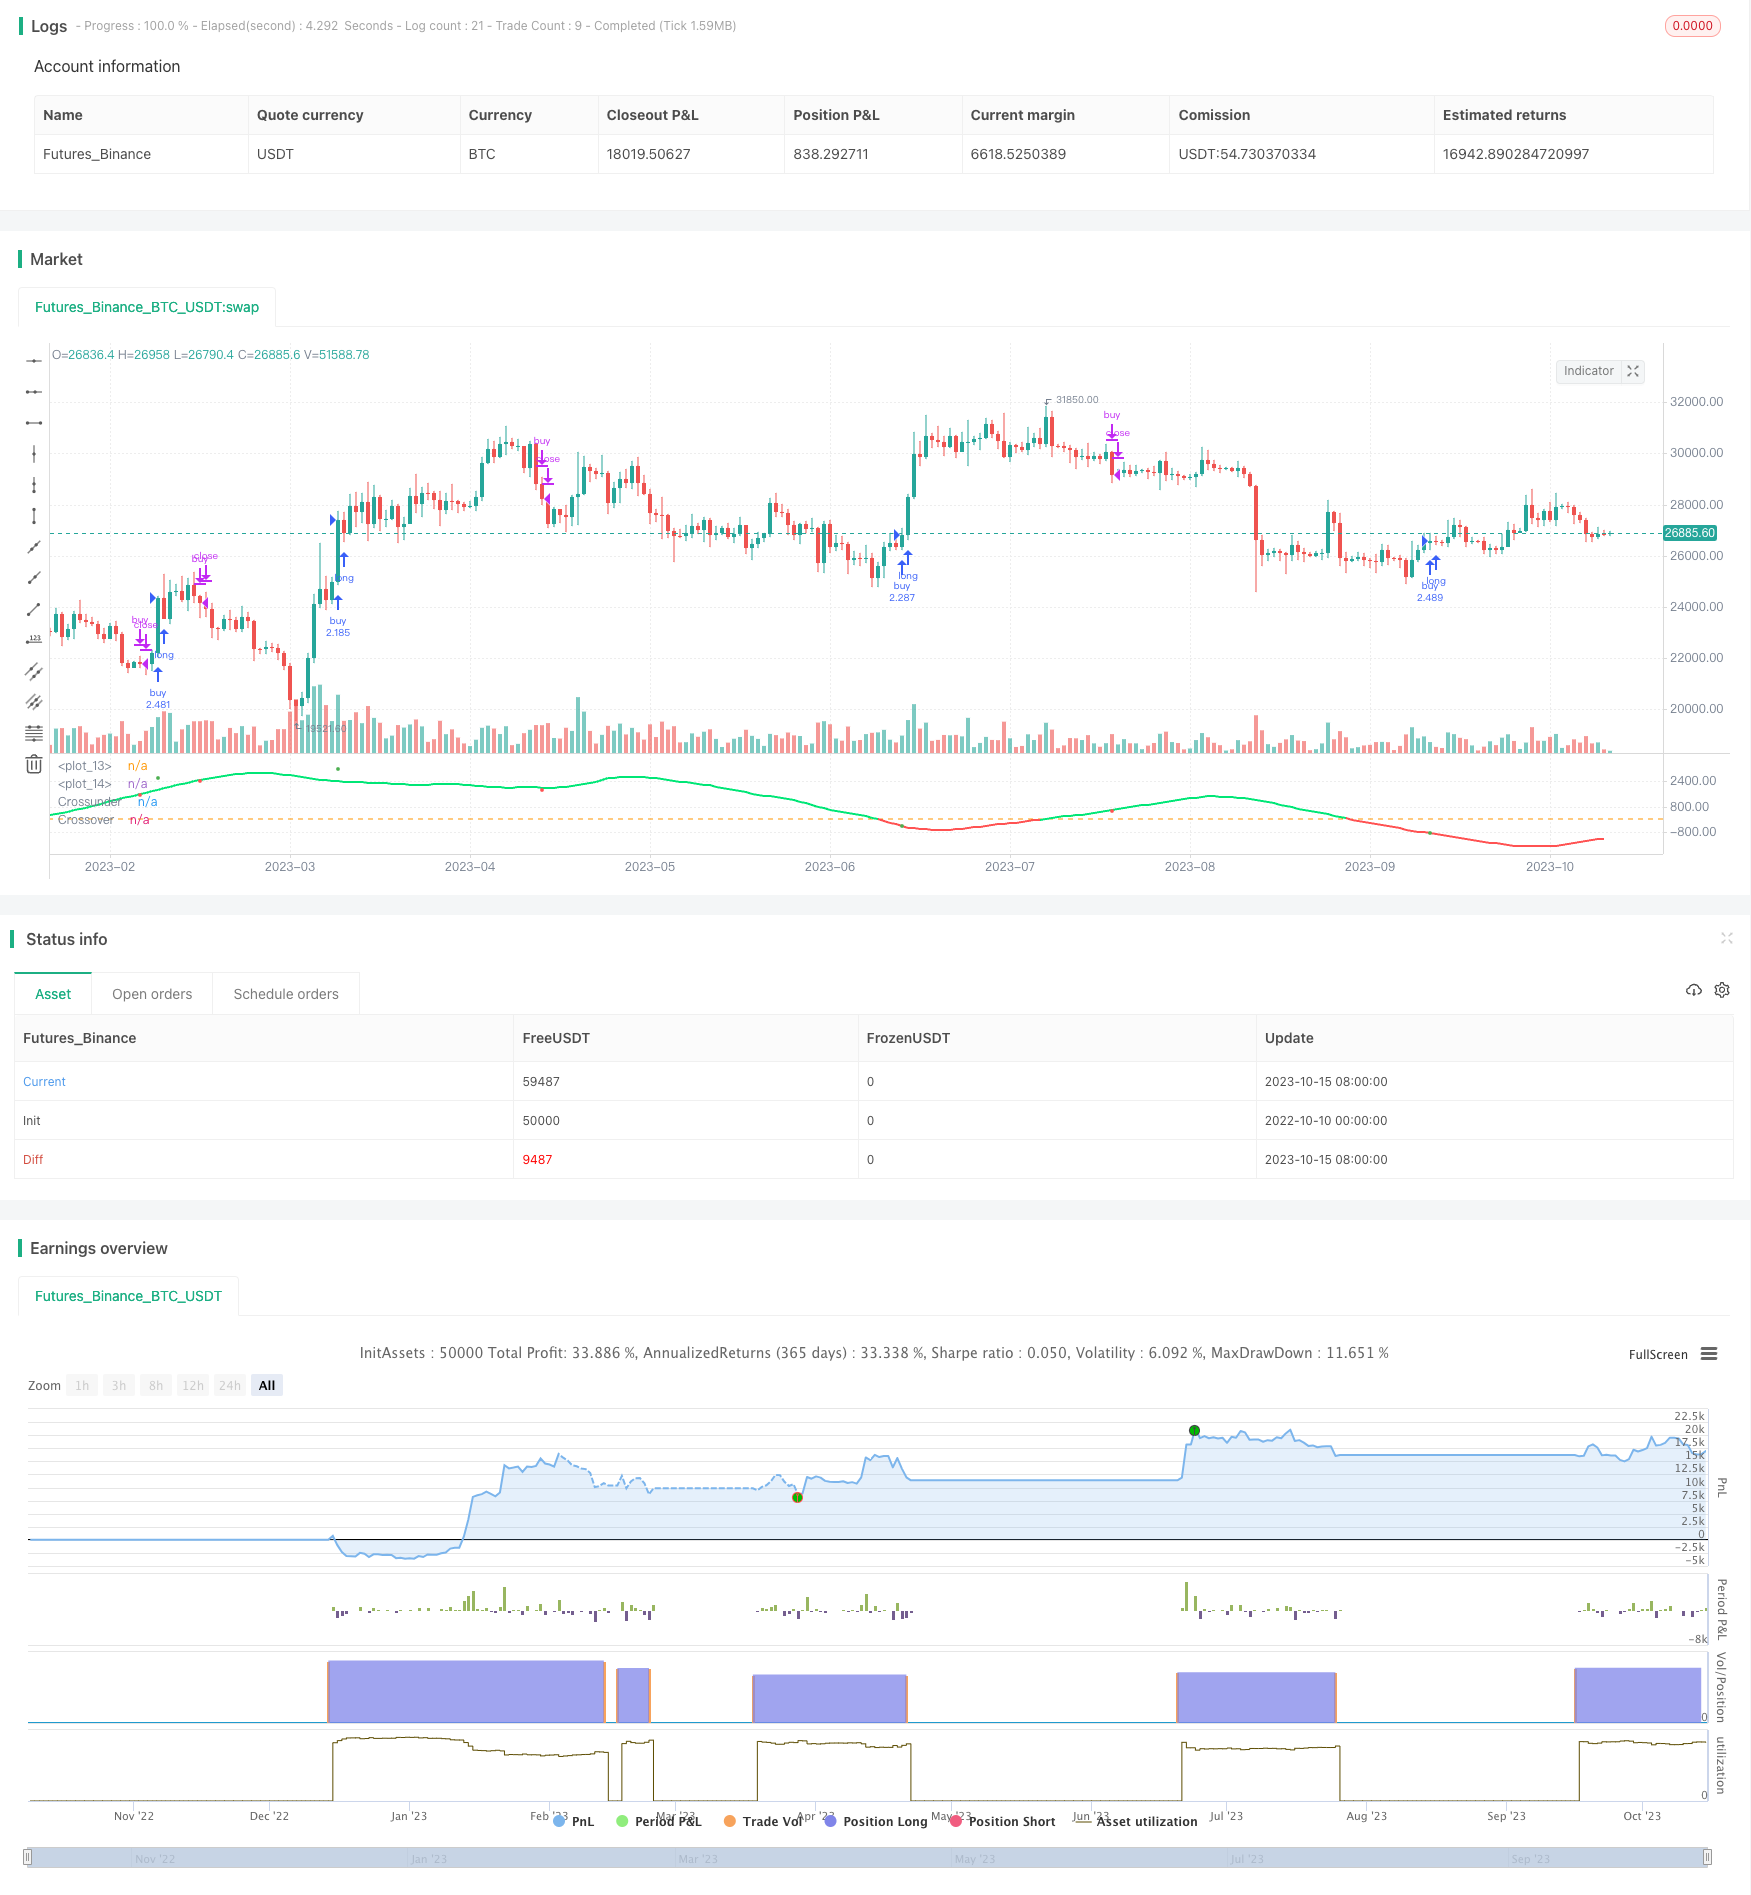
Overview
This strategy generates trading signals based on the difference between two moving averages with different timeframes. It calculates a faster SMA and a slower SMA, and produces buy signals when the fast SMA crosses above the slow SMA from below, and sell signals when the fast SMA crosses below the slow SMA from above.
How It Works
The core logic of this strategy is to compute two moving averages, SMA(len1) and SMA(len2), and their difference dif. Here len1 represents the period of the faster MA and len2 the slower MA. The faster MA responds quicker to price changes while the slower MA reflects the long term trend better.
When the faster MA crosses above the slower MA from below, it indicates the short term price has started to rise above the long term trend, and thus a long entry can be taken. When the faster MA crosses below the slower MA from above, it signals the short term price has started to fall below the trend, and a short position can be entered.
To filter out false signals, the strategy also uses out3 as the trading signal line, which is the smoothed difference between the faster MA and price midpoint. Only when out3 crosses dif will trades be triggered.
Specifically, the long variable holds positive values when out3 crosses above dif, giving buy signals. The short variable holds negative values when out3 crosses below dif, generating sell signals. strategy.entry entries long when long signal occurs, and strategy.close closes long when short signal emerges.
Advantage Analysis
This is a very simple and intuitive strategy to follow trends. It uses the crossover of two MAs of different periods to identify trend reversal points, which can be more reliable than a single MA system. The filter of trading signal line also helps avoid false signals in choppy markets to some extent.
Compared to stop loss, it adopts a trend following mindset to maximize profits during longer trends without being stopped out. At the same time, it also controls losses by closing positions in time when trend reverses.
This strategy has few parameters and is easy to understand and tune, making it suitable as a beginner's algo trading strategy.
Risks and Improvements
The biggest risk of this strategy is improperly chosen MA periods resulting in bad signals. If len1 is too long, early trend moves will be missed; if too short, whipsaws increase. If len2 is too long, position adjustments will be delayed; if too short, it may be disturbed by market noise.
The parameters can be optimized by trying different len1 and len2 values to find the best combination. Adaptive MAs can also be tested to dynamically change periods. The filter can also be improved to further reduce false signals.
Trend following strategies should also control loss on single trades, through stop loss or position sizing.
Conclusion
The dual MA crossover strategy is a quintessential trend following representative. Its simple dual MA crossover system provides steady signals, while the filter helps avoid noise. With optimized MA periods, it can achieve good performance. The strategy serves well as a beginner's algo trading strategy to learn.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 50 | Length1 |
| v_input_2 | 100 | Length2 |
| v_input_3 | true | Smoothing |
| v_input_4_ohlc4 | 0 | Source: ohlc4 | high | low | open | hl2 | hlc3 | hlcc4 | close |
Source Pine Script
/*backtest
start: 2022-10-10 00:00:00
end: 2023-10-16 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//by afrazium
//@version=3
strategy(title="SMA Diff strat", shorttitle="SMAD STR", overlay=false, initial_capital=1, precision=8, default_qty_type=strategy.percent_of_equity, default_qty_value=100, commission_type=strategy.commission.percent, commission_value=0.1, calc_on_order_fills= false, calc_on_every_tick=false, pyramiding=0)
len1 = input(50, minval=1, title="Length1"), len2 = input(100, minval=1, title="Length2"), smo = input(1, minval=1, title="Smoothing")
src = input(ohlc4, title="Source")

mid = src
expr1 = sma(src, len1), expr2 = sma(src, len2)
dif = (expr1 - expr2), out1 = (mid - expr1), out2 = (mid - expr2), out3 = sma(out1, smo)

long = crossover(out3, dif) ? out3 : na, short = crossunder(out3, dif) ? out3 : na

plot(out3, color=black, linewidth=2), hline(0)
clr = out2 >= out1 ? lime : red, plot(dif, color=clr, linewidth=2)
plot(long, title = 'Crossover', color = green, style = circles, linewidth=4), plot(short, title = 'Crossunder', color = red, style = circles, linewidth=4)

strategy.entry("buy", strategy.long, when=crossover(out1, dif))
strategy.close("buy", when=crossunder(out1, dif))

//plot(out2, color=blue, linewidth=2)
//A = plot(mid/10, color=red, linewidth=1, transp=100), B = plot(mid/20, color=red, linewidth=1, transp=100)
//C = plot(-mid/10, color=green, linewidth=1, transp=100), D = plot(-mid/20, color=green, linewidth=1, transp=100)
//fill(A, B, color=red), fill(C, D, color=green)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Crossover-Strategy-429464.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m