Strategy vault / Trend following
Dual Moving Average Crossover Strategy 430897
The dual moving average crossover strategy is one of the most popular trading strategies. It utilizes the crossover of a fast moving average and a slow moving average as buy and sell signals. When the fast MA crosses…
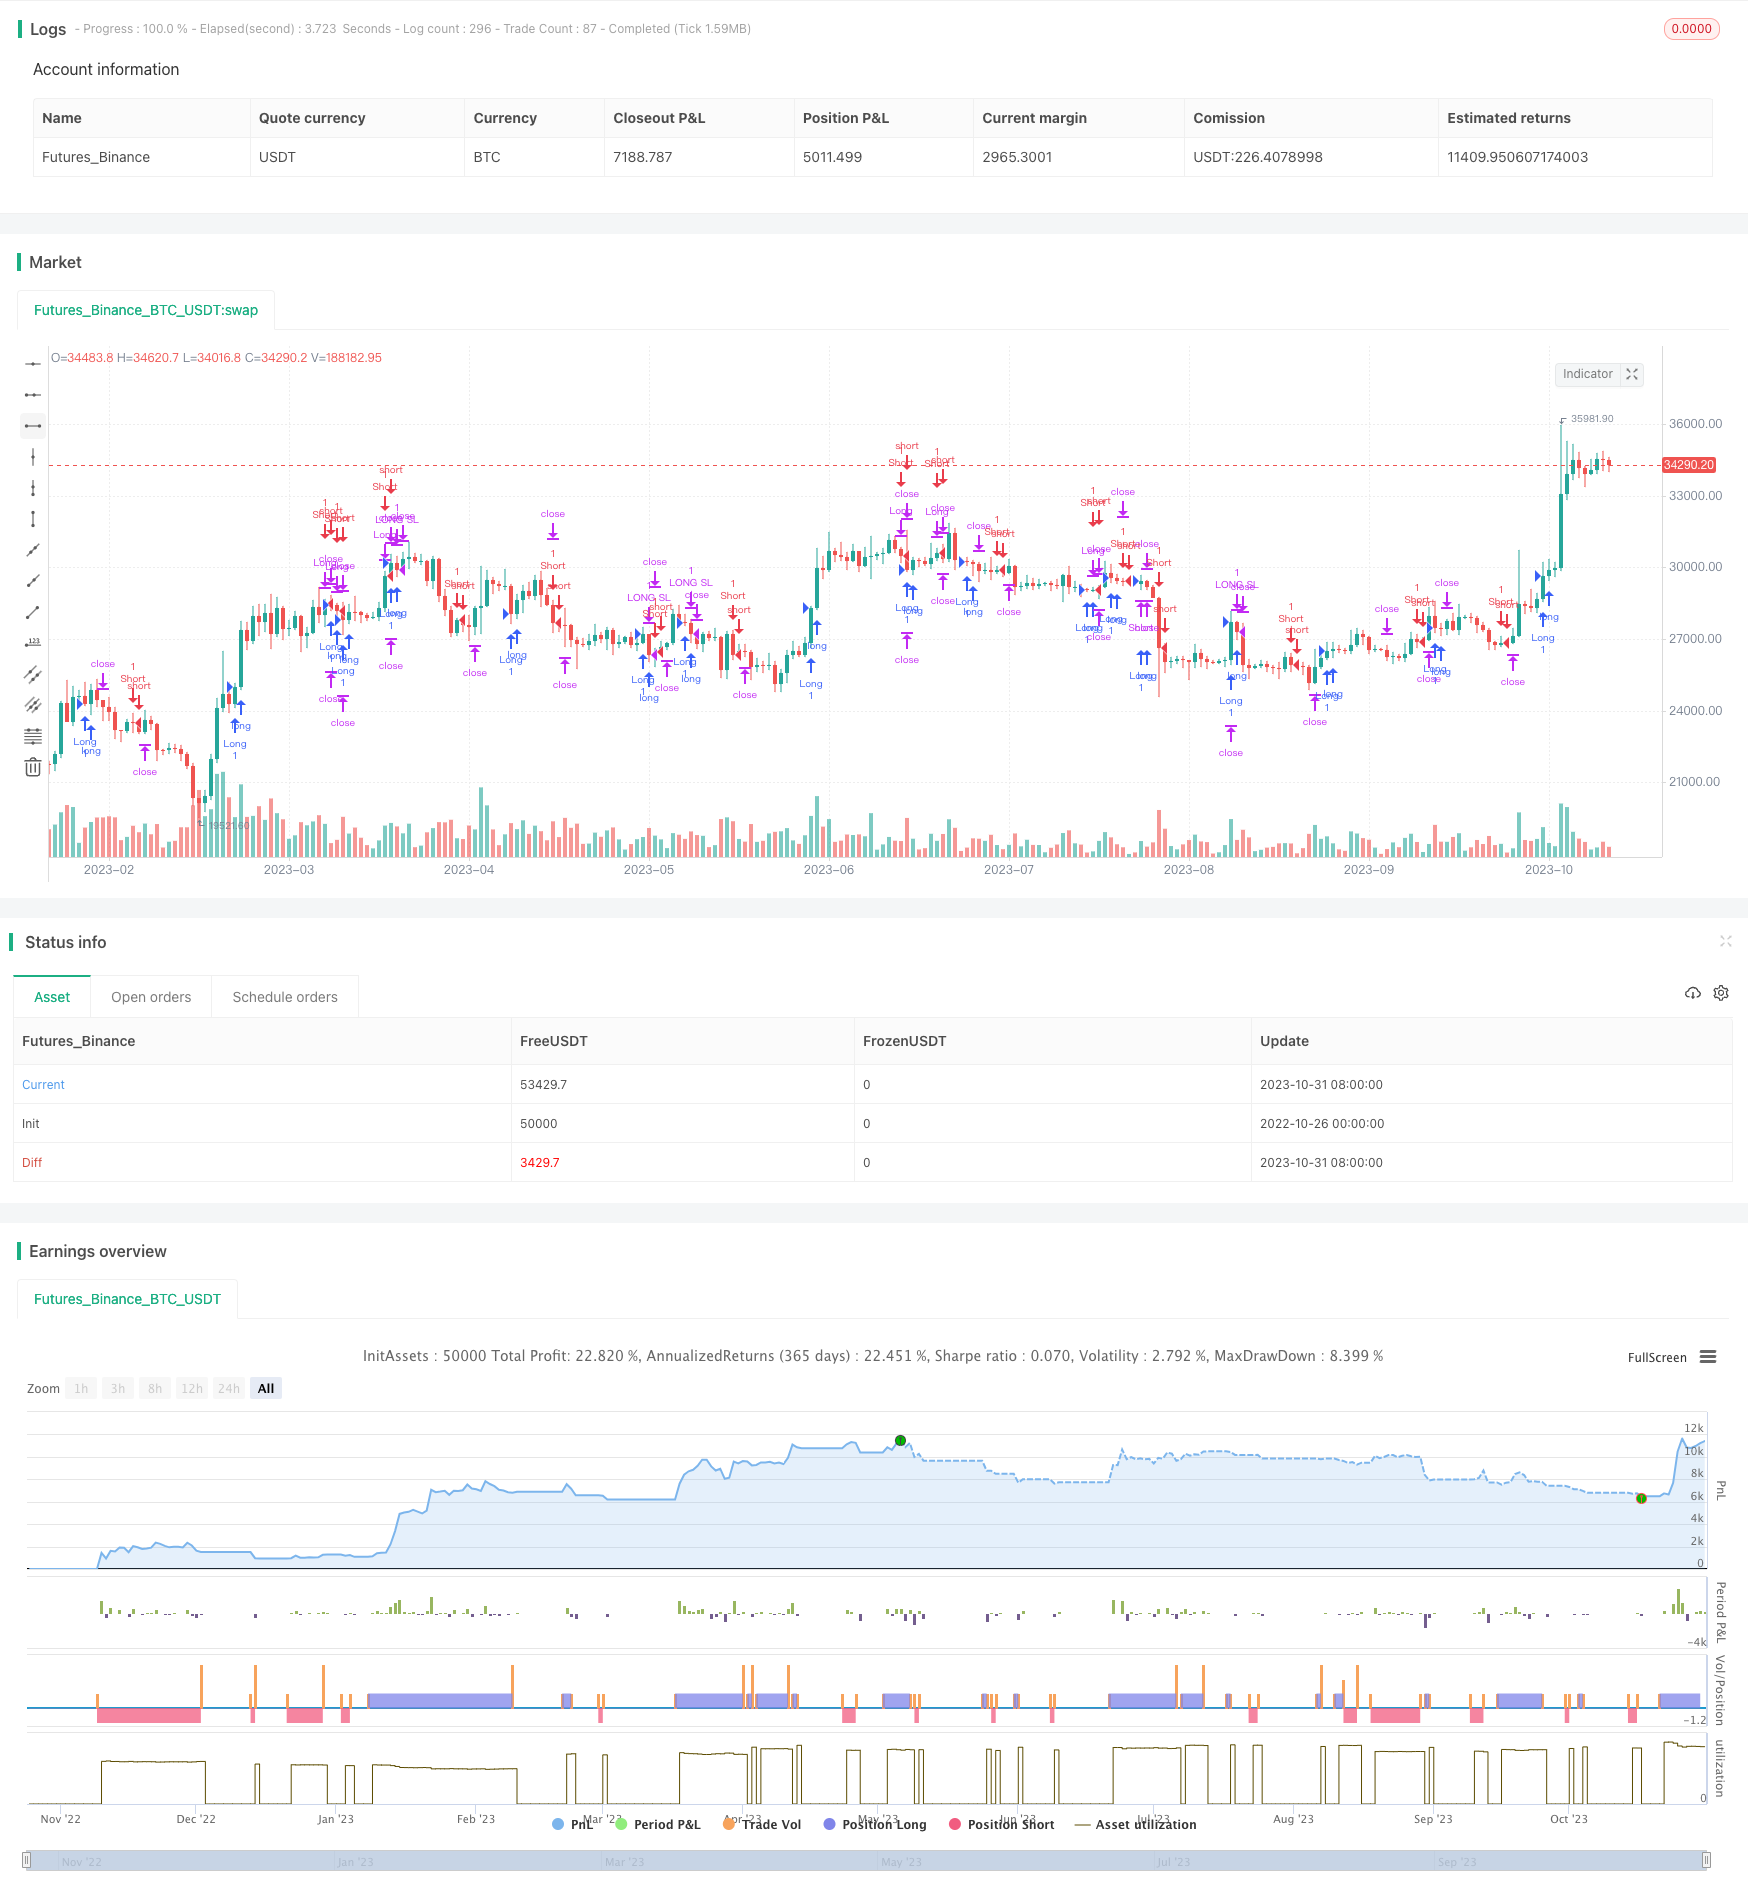 Here is a detailed analysis article of the trend-following strategy using double moving averages:
Overview
The dual moving average crossover strategy is one of the most popular trading strategies. It utilizes the crossover of a fast moving average and a slow moving average as buy and sell signals. When the fast MA crosses above the slow MA, it generates a buy signal. When the fast MA crosses below the slow MA, it generates a sell signal. This strategy belongs to the category of traditional trend following strategies.
Strategy Logic
This strategy uses simple moving averages of length 10 and 13. When the 10-period SMA crosses above the 13-period SMA, a buy signal is generated. When the 10-period SMA crosses below the 13-period SMA, a sell signal is generated.
If the long condition is met while currently holding a short position, the short position will be closed first before entering a long position. Similarly, if the short condition is met while currently holding a long position, the long position will be closed first before entering a short position.
In addition, this strategy incorporates stop loss logic. For long trades, the stop loss price is calculated based on the input percentage. The same applies for short trades. When price hits the stop loss level, the current position will be exited.
Advantage Analysis
This strategy captures trends and follows medium to long term trend movements.
The dual MA design helps filter out false breakouts effectively.
The stop loss helps control loss on individual trades.
The strategy logic is simple and easy to understand.
MA parameters can be adjusted for optimization.
Risk Analysis
As a trend following strategy, it risks being caught at trend reversals.
MA systems can lag and miss turning points.
Improper stop loss setting may lead to unnecessary losses.
Dual MA crossovers do not completely eliminate false signals.
The strategy ignores fundamentals and focuses solely on technicals.
Improvement Directions
The MA parameters can be optimized to find the optimal periods.
A triple MA system could improve signal accuracy.
The stop loss can be made adaptive to price.
Additional filters could be added to screen signals.
Money management can be enhanced to limit losses.
Conclusion
The dual moving average crossover is a simple and practical trend following strategy. It can effectively capture medium to long term trends and generate steady excess returns. But it runs the risk of being whipsawed at trend reversals. The strategy can be improved via parameter optimization, better signal filtering and enhanced risk management. Overall, it is an ideal starter strategy for novice traders.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Long Stop Loss (%) |
| v_input_2 | true | Short Stop Loss (%) |
Source Pine Script
/*backtest
start: 2022-10-26 00:00:00
end: 2023-11-01 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © chiragchopra91
//@version=4

strategy(title='Chirag Strategy SMA', shorttitle='CHIRAGSMA', overlay=true)

longCondition = crossover(sma(close, 10), sma(close, 13))
shortCondition = crossover(sma(close, 13), sma(close, 10))

// Set stop loss level with input options
longLossPerc = input(title="Long Stop Loss (%)", type=input.float, minval=0.0, step=0.1, defval=1) * 0.01
shortLossPerc = input(title="Short Stop Loss (%)", type=input.float, minval=0.0, step=0.1, defval=1) * 0.01

longStopPrice  = strategy.position_avg_price * (1 - longLossPerc)
shortStopPrice = strategy.position_avg_price * (1 + shortLossPerc)

if longCondition
    if strategy.position_size < 0
        strategy.close('Short', comment="SHORT EXIT")
    strategy.entry('Long', strategy.long, comment="BUY")

if shortCondition
    if strategy.position_size > 0
        strategy.close('Long', comment="BUY EXIT")
    strategy.entry('Short', strategy.short, comment="SHORT")

if strategy.position_size > 0
    strategy.exit('LONG SL', stop=longStopPrice, comment="LONG SL EXIT")

if strategy.position_size < 0
    strategy.exit('SHORT SL', stop=shortStopPrice, comment="SHORT SL EXIT")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-02. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Crossover-Strategy-430897.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m