Strategy vault / Trend following
Dual Moving Average HullMA Crossover Trend Strategy
The Dual Moving Average HullMA Crossover Trend strategy is a trend-following strategy based on the crossover of dual moving averages. It builds a dual moving average system using Weighted Moving Average (WMA) lines…
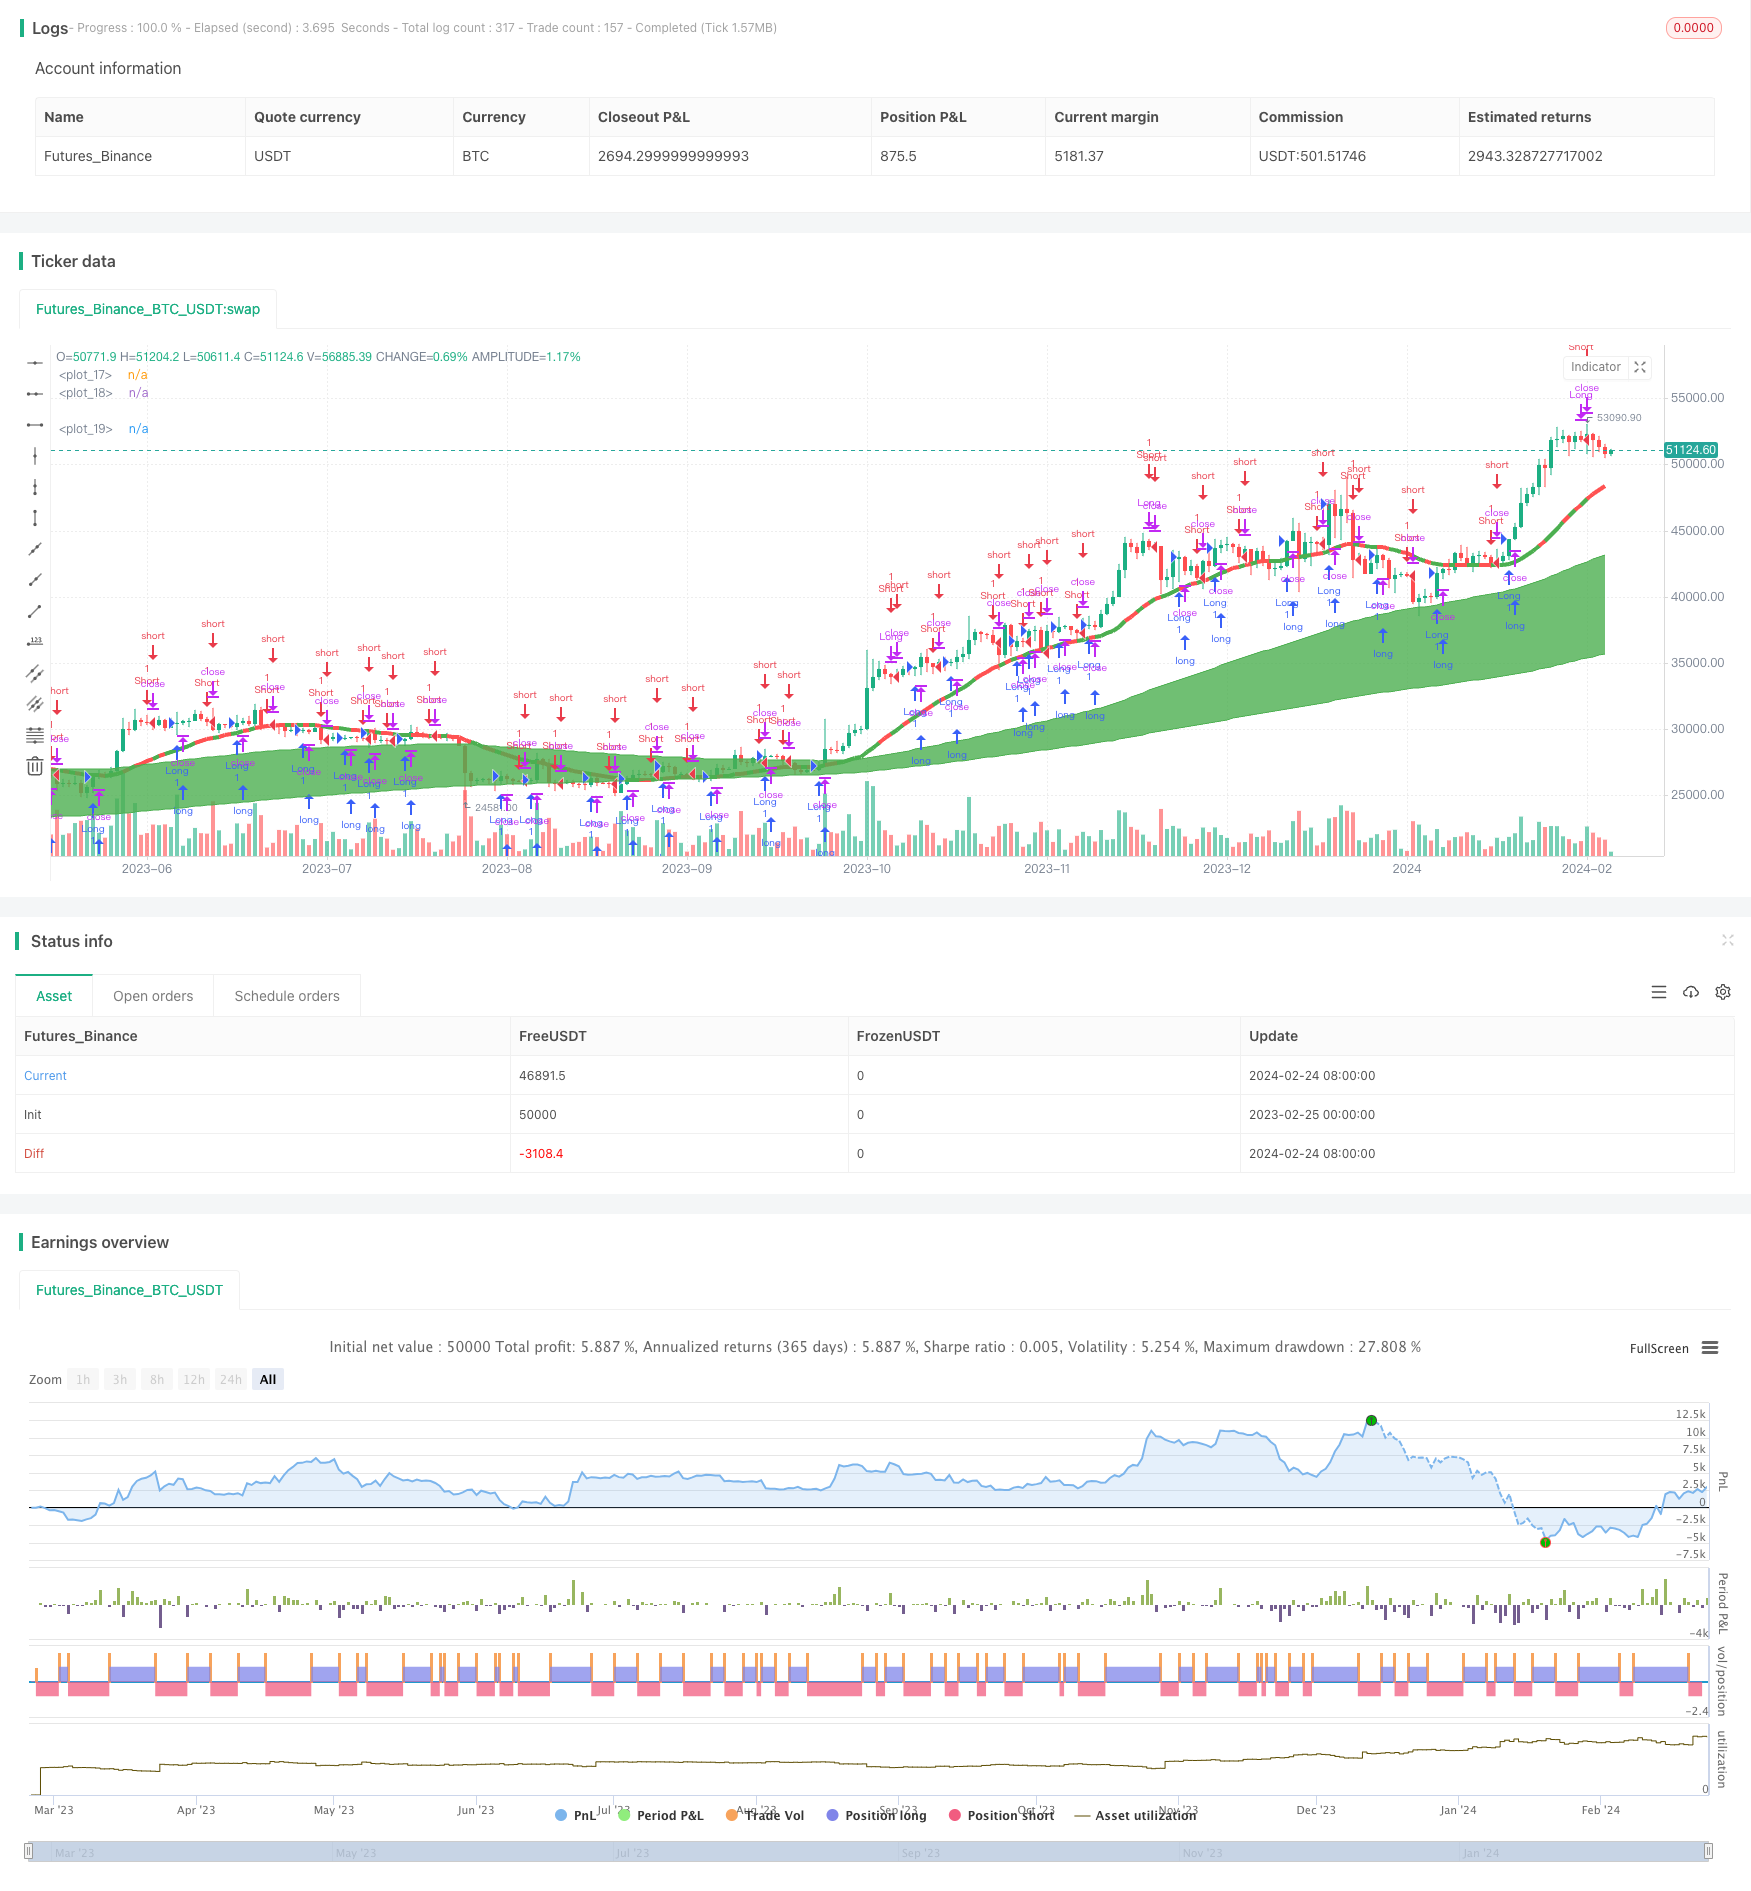
Overview
The Dual Moving Average HullMA Crossover Trend strategy is a trend-following strategy based on the crossover of dual moving averages. It builds a dual moving average system using Weighted Moving Average (WMA) lines and generates trading signals when they cross over. The strategy also incorporates price breakout validation to further filter the signals.
Strategy Logic
The Dual Moving Average HullMA Crossover Trend strategy employs three WMA lines with different periods, including wma1, wma2, and wma3. The wma2 and wma3 construct the dual moving average system. The wma2 crossing above wma3 gives bullish signals, while the wma2 crossing below wma3 gives bearish signals. The wma1 serves as an auxiliary reference line.
Additionally, the strategy utilizes the Hull Moving Average to strengthen signal validation. Specifically, it calculates the difference between 2-period WMA doubled (n2ma) and n-period WMA (nma). Only when the difference rises will bull signals be confirmed valid. Only when the difference falls will bear signals be confirmed valid.
The strategy also incorporates price validation. Only when the price is higher than the previous day will bull signals be confirmed valid for long orders. Only when the price is lower than the previous day will bear signals be confirmed valid for short orders.
Advantage Analysis
The Dual Moving Average HullMA Crossover Trend strategy combines dual moving average crossover and price validation, which allows it to effectively filter out false signals. This is its biggest strength. Also, with three moving average lines of various periods, the strategy can capture trends of different levels early on. Its stop loss mechanism is quite stable and reliable as well.
Risk Analysis
As a trend-following strategy, the Dual Moving Average HullMA Crossover Trend strategy can generate relatively more trades and slippage costs during range-bound markets. Additionally, dual moving average crossover systems tend to be too sensitive and may emit incorrect signals during sideways trends. It is advisable to tune the moving average parameters or impose additional filters accordingly.
Optimization Directions
The Dual Moving Average HullMA Crossover Trend strategy can be improved in the following aspects:
Optimize the moving average parameters to find the best parameter combination
Add filters like volume or volatility to eliminate false breakouts
Incorporate other indicators as supplementary validation to improve signal quality
Dynamically optimize moving average period parameters
Summary
In summary, the Dual Moving Average HullMA Crossover Trend strategy is a stable and reliable trend-following strategy. It produces high-quality signals by combining dual moving average crossover and price validation. Through parameter tuning and adding filters, it can further reduce incorrect signals and achieve better performance. It is suitable for catching medium- to long-term trends and a solid choice for quantitative trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0.001 | Decision Threshold |
| v_input_2 | 7 | Double HullMA Cross |
| v_input_3 | 34 | MA 1 |
| v_input_4 | 144 | MA 2 |
| v_input_5 | 377 | MA 3 |
| v_input_6 | 4200 | TP ($) |
Source Pine Script
/*backtest
start: 2023-02-25 00:00:00
end: 2024-02-25 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy("ZendicatoR", overlay=true)
dt = input(defval=0.0010, title="Decision Threshold", type=float, step=0.0001)
keh=input(title="Double HullMA Cross",defval=7, minval=1)
che1=input(title="MA 1",defval=34,minval=1)
che2=input(title="MA 2",defval=144,minval=1)
che3=input(title="MA 3",defval=377,minval=1)
amnt=input(title="TP ($)",defval=4200,minval=1)
wma1=wma(close,che1)
wma2=wma(close,che2)
wma3=wma(close,che3)
tms=10000000000000
A=request.security(syminfo.tickerid, 'D', close)*tms
B=request.security(syminfo.tickerid, 'D', close[1])*tms
C=A>B?green:red
D=wma2>wma3?green:red
plot(wma1,style=line,color=C,linewidth=4)
p1=plot(wma2,style=line,color=D)
p2=plot(wma3,style=line,color=D)
fill(p1, p2, color=D, transp=75)
n2ma=2*wma(close,round(keh/2))
nma=wma(close,keh)
diff=n2ma-nma,sqn=round(sqrt(keh))
n2ma1=2*wma(close[2],round(keh/2))
nma1=wma(close[2],keh)
diff1=n2ma1-nma1,sqn1=round(sqrt(keh))
n1=wma(diff,sqn)*tms
n2=wma(diff1,sqn)*tms
closelong = A*tms<B*tms and n2*tms>n1*tms and strategy.openprofit>amnt
if (closelong)
    strategy.close("Long")
closeshort = A*tms>B*tms and n1*tms>n2*tms and strategy.openprofit>amnt
if (closeshort)
    strategy.close("Short")
longCondition = A*tms>B*tms and n1*tms>n2*tms
if (longCondition)
    strategy.entry("Long",strategy.long)
shortCondition = A*tms<B*tms and n1*tms<n2*tms
if (shortCondition)
    strategy.entry("Short",strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-HullMA-Crossover-Trend-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Profit Target and Stop Loss StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h