Dual Moving Average Momentum Tracking Quantitative Strategy
This is a quantitative trading strategy based on dual moving average crossover signals. The strategy employs two moving averages, one as the main signal line and another as a smoothing signal line. It generates…
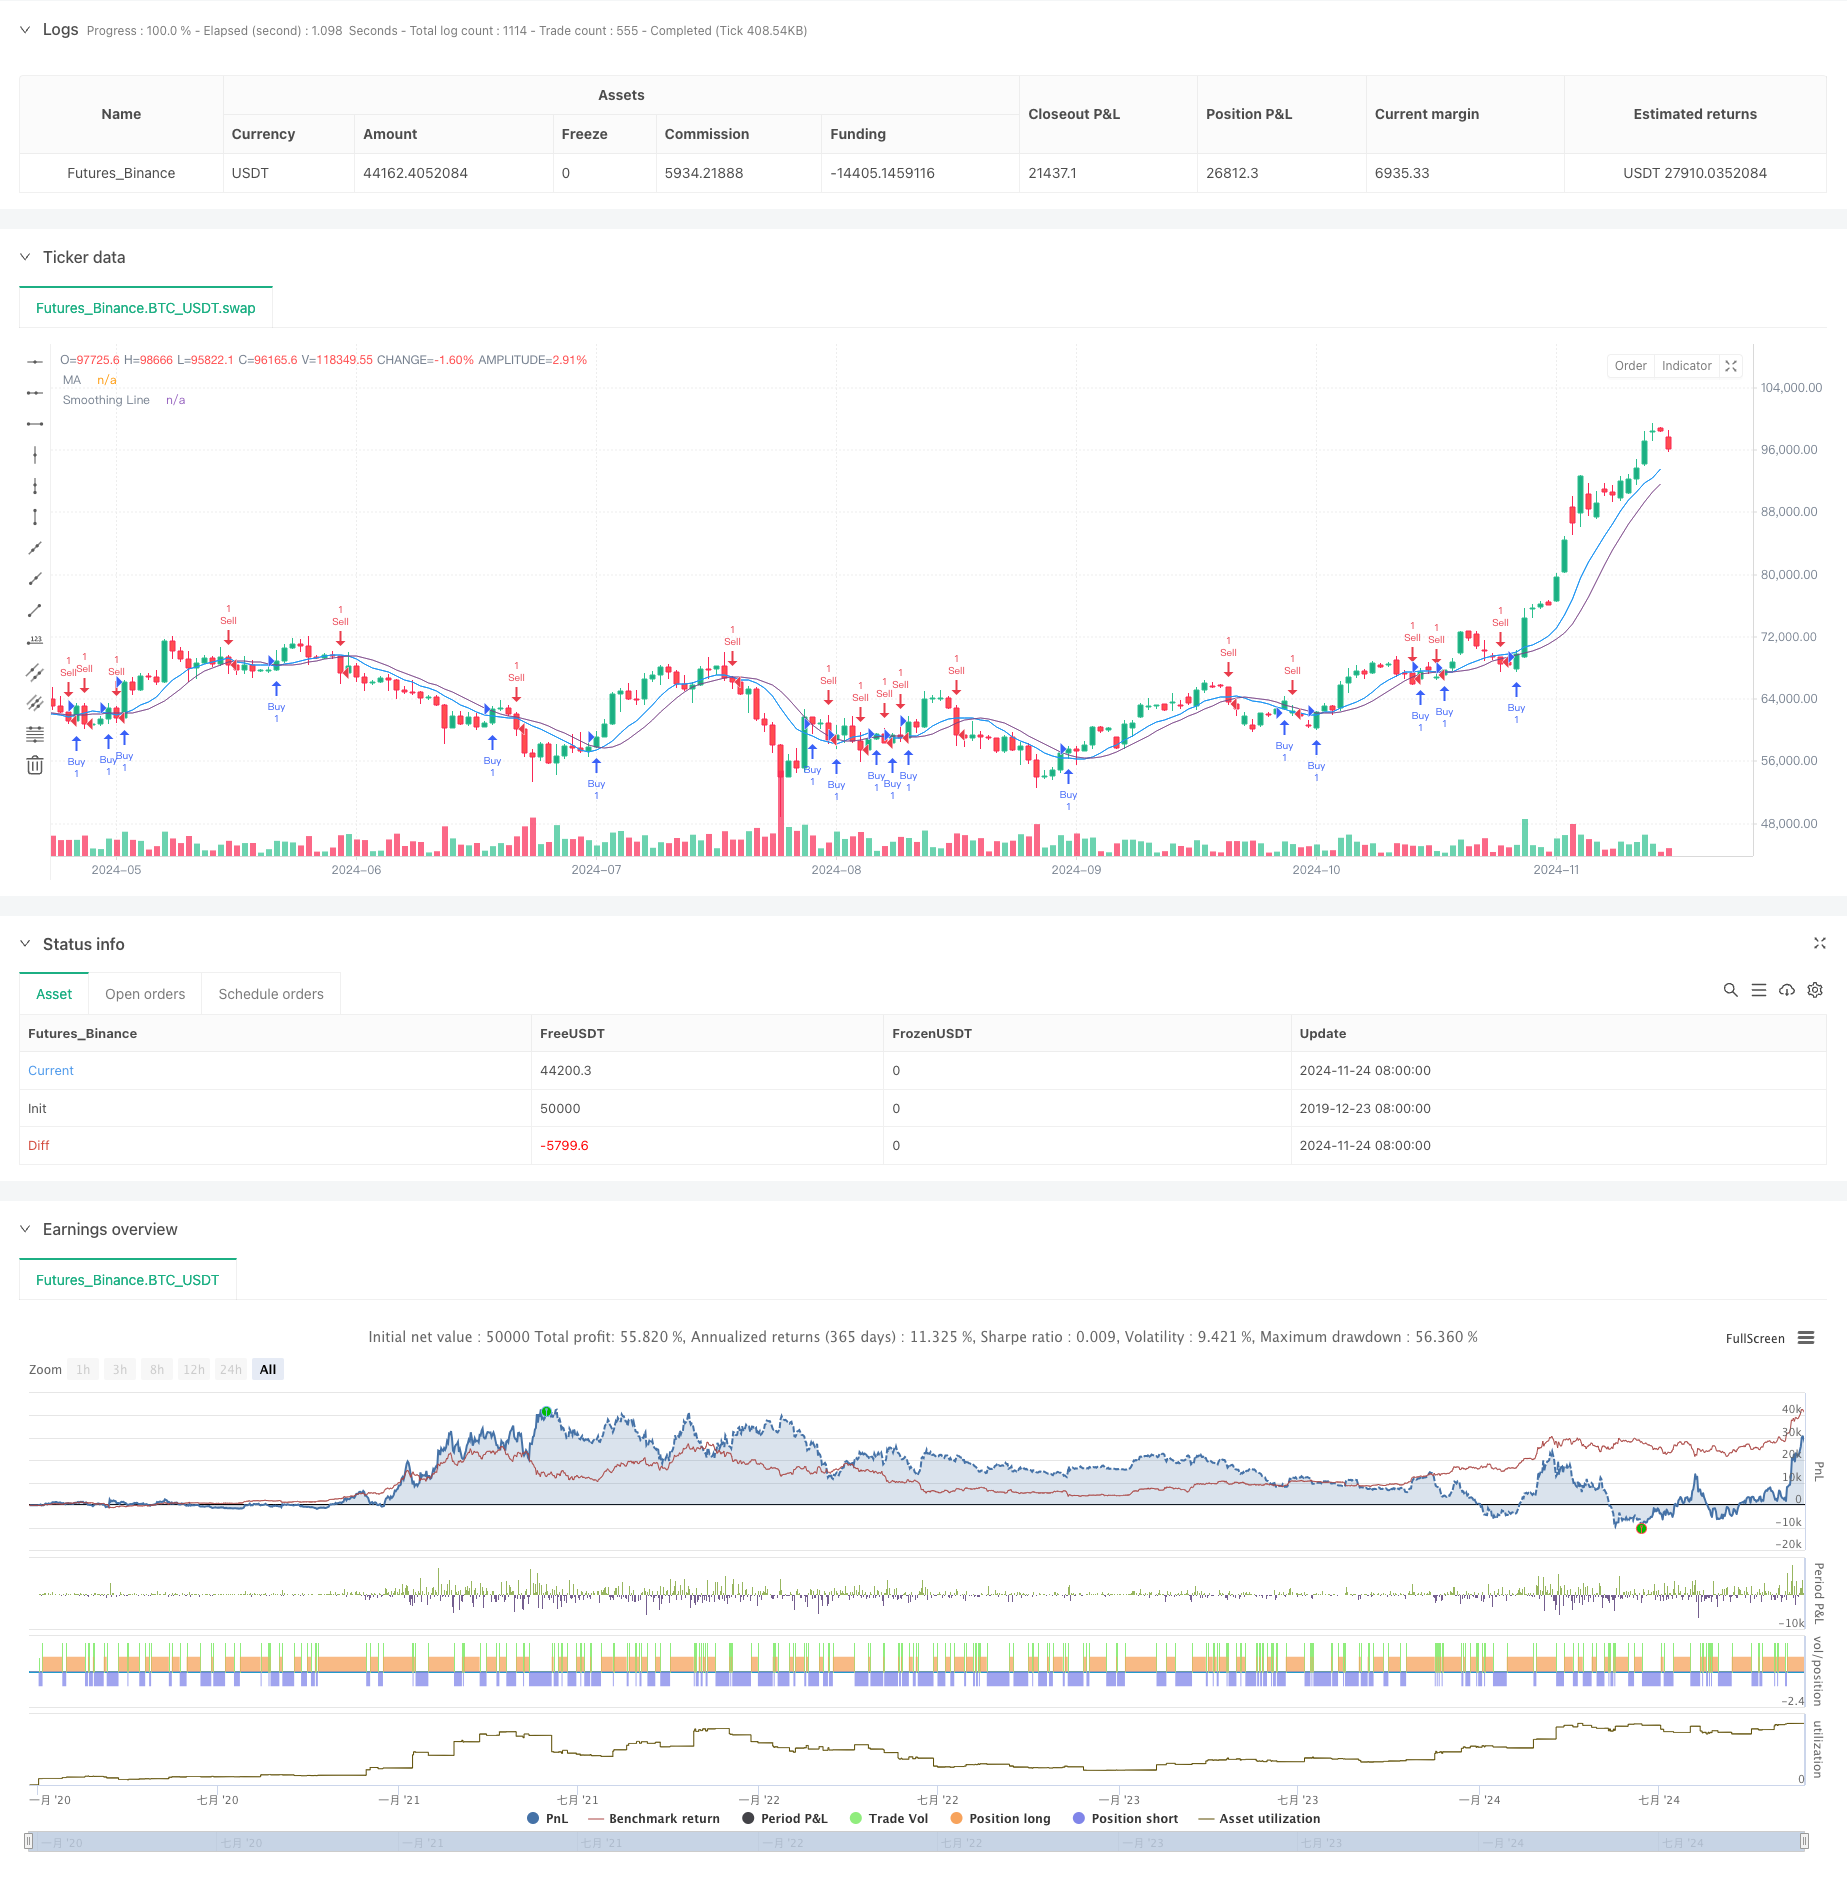
Overview
This is a quantitative trading strategy based on dual moving average crossover signals. The strategy employs two moving averages, one as the main signal line and another as a smoothing signal line. It generates trading signals by monitoring price crossovers with the smoothing signal line, enabling market trend capture and momentum tracking. The strategy's core strength lies in its simple yet effective signal generation mechanism and flexible parameter configuration options.
Strategy Principle
The strategy utilizes two levels of moving average calculations. It first computes a basic moving average (default period of 9), followed by a secondary smoothing process (default period of 5). The strategy offers various moving average calculation methods, including Simple Moving Average (SMA), Exponential Moving Average (EMA), Smoothed Moving Average (SMMA), Weighted Moving Average (WMA), and Volume Weighted Moving Average (VWMA). Long signals are generated when the closing price crosses above the smoothing signal line, while short signals are generated when the closing price crosses below it.
Strategy Advantages
- Clear and simple signal generation mechanism, easy to understand and implement
- Effective reduction of false signals through secondary smoothing
- Multiple moving average calculation methods available for different market characteristics
- Flexible parameter configuration for different market cycles
- Clear code structure, easy to maintain and expand
- Strong trend-following capabilities
Strategy Risks
- May generate frequent trading signals in oscillating markets, increasing transaction costs
- Some inherent lag, potentially missing the beginning of market moves
- Possible significant drawdowns during rapid market reversals
- Single technical indicator strategy, lacking market environment assessment
- Risk of overfitting through excessive parameter optimization
Strategy Optimization Directions
- Introduce market environment assessment mechanisms for different parameter configurations
- Add stop-loss and take-profit mechanisms for risk control
- Implement volume filters to avoid trading in low liquidity environments
- Incorporate additional technical indicators as confirmatory signals
- Develop adaptive parameter mechanisms for dynamic market adjustments
- Add position management module for more flexible position control
Summary
This is an improved version of a classic trend-following strategy that enhances stability while maintaining simplicity through a dual-layer moving average design. The strategy offers good scalability and flexibility, adaptable to different market environments through parameter optimization and function extensions. However, users need to pay attention to transaction cost control and risk management, and it is recommended to conduct thorough backtesting before live trading.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-25 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Moving Average 1.0 Strategy", overlay=true)

// Input for Moving Average Length
len = input.int(9, minval=1, title="Length")
src = input(close, title="Source")
offset = input.int(title="Offset", defval=0, minval=-500, maxval=500)

// Calculate the Moving Average
out = ta.sma(src, len)

// Plot the Moving Average
plot(out, color=color.blue, title="MA", offset=offset)

// Function to choose the type of moving average
ma(source, length, type) =>
    switch type
        "SMA" => ta.sma(source, length)
        "EMA" => ta.ema(source, length)
        "SMMA (RMA)" => ta.rma(source, length)
        "WMA" => ta.wma(source, length)
        "VWMA" => ta.vwma(source, length)

// Input for Smoothing Method and Length
typeMA = input.string(title="Method", defval="SMA", options=["SMA", "EMA", "SMMA (RMA)", "WMA", "VWMA"], group="Smoothing")
smoothingLength = input.int(title="Smoothing Length", defval=5, minval=1, maxval=100, group="Smoothing")

// Calculate the Smoothing Line
smoothingLine = ma(out, smoothingLength, typeMA)

// Plot the Smoothing Line
plot(smoothingLine, title="Smoothing Line", color=color.rgb(120, 66, 134, 35), offset=offset)

// Strategy Logic
if (ta.crossover(close, smoothingLine))
    strategy.entry("Buy", strategy.long)

if (ta.crossunder(close, smoothingLine))
    strategy.entry("Sell", strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Momentum-Tracking-Quantitative-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- Multi EMA Trend Momentum Trading Strategy with Risk Management SystemPine Script · Momentum · 1h
- Multi Indicator Trend Momentum Trading Strategy with Dynamic Risk Management SystemPine Script · Momentum · 1h
- Multi Level Technical Indicator Momentum Trading Strategy Based on Enhanced MACD Volume Strength and EMA Signal SystemPine Script · Momentum · 1h
- Multi Timeframe Momentum Confluence Automated Trading StrategyPine Script · Momentum · 1h
- Triple EMA and Fisher Transform Trend Momentum StrategyPine Script · Momentum · 1d