Strategy vault / Mean reversion
Dual Moving Average Reversal Strategy 432848
The main idea of this strategy is to use the crossover of fast and slow moving averages to judge market trends and take positions when short-term and long-term moving averages reverse, so as to achieve the effect of…
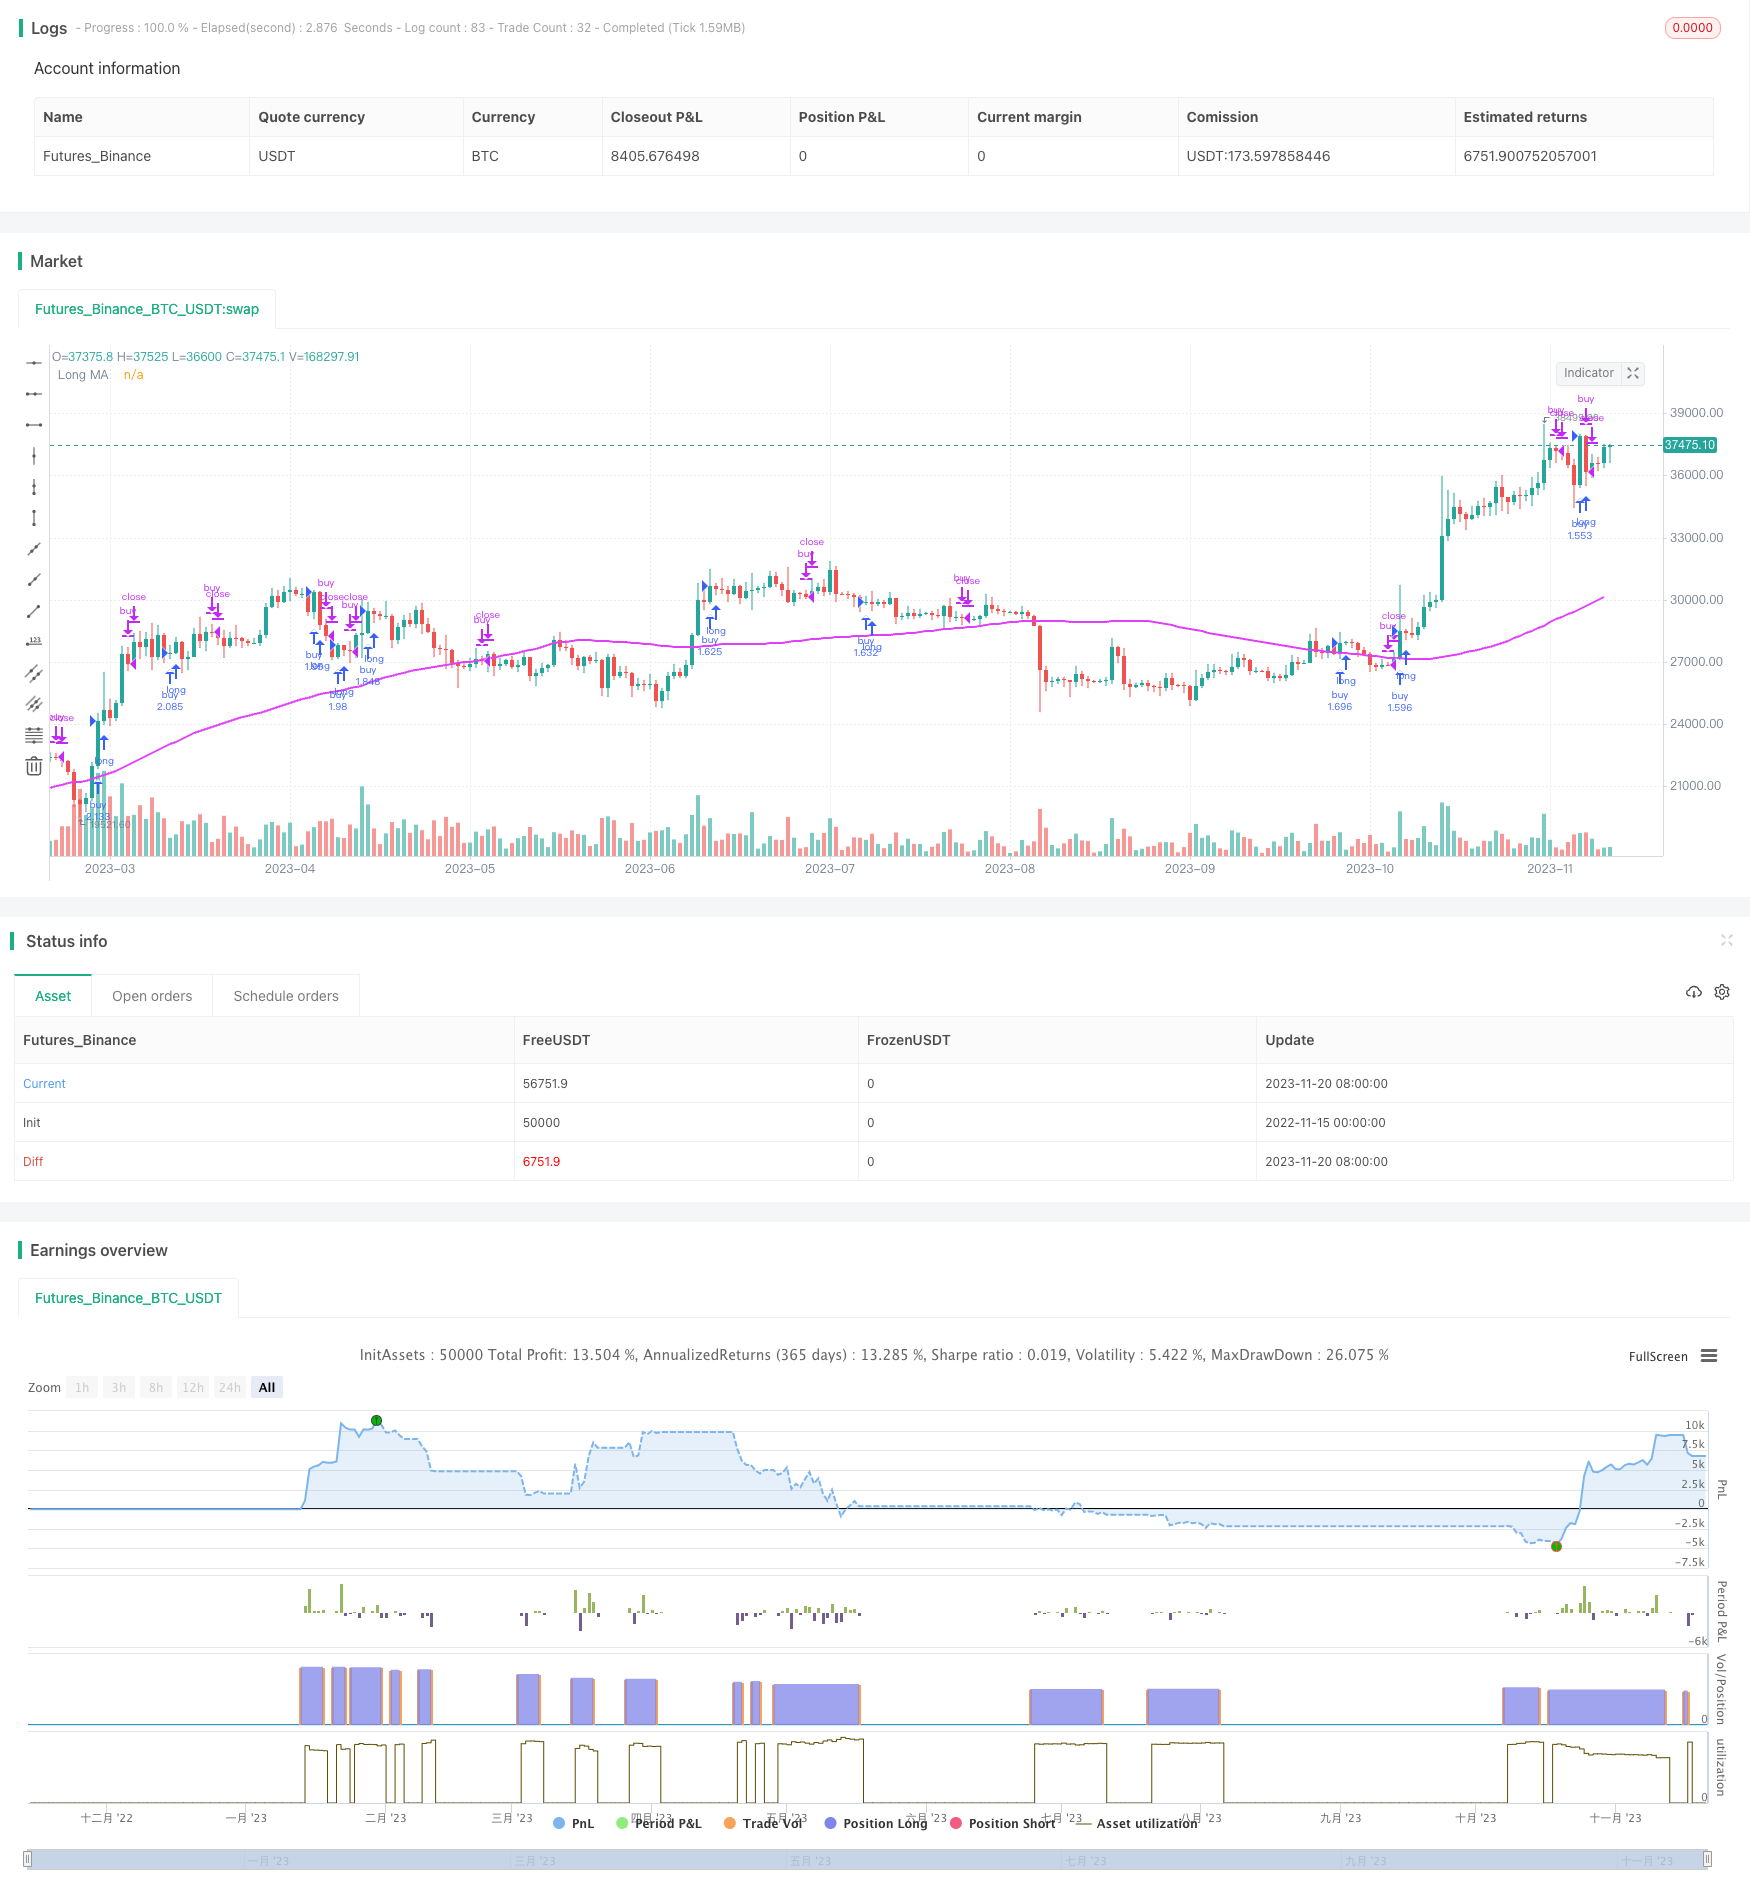
Overview
The main idea of this strategy is to use the crossover of fast and slow moving averages to judge market trends and take positions when short-term and long-term moving averages reverse, so as to achieve the effect of tracking trends.
Strategy Logic
- Set short-term moving average period shortma (default 7 days) and long-term moving average period longma (default 77 days)
- When the short MA crosses over the long MA, it is determined as a buy signal and record barssince(mabuy). The long MA implies an uptrend has begun. When the short MA crosses below the long MA, it is determined as a sell signal and record barssince(masell). The long MA implies the uptrend has ended.
- Compare the barssince values. The more bars since the short MA crossed down, the longer the uptrend has persisted. The more bars since the short MA crossed up, the stronger the reversal signal.
- When barssince for the sell signal is greater than barssince for the buy signal, a buy signal is triggered. When barssince for the buy signal is greater than barssince for the sell signal, a sell signal is triggered.
- Essentially this is a dual MA reversal strategy, using crossover reversals of fast and slow MAs to detect trend reversal points.
Advantages
- Uses dual MAs to filter some false signals
- Added barssince comparision avoids false breaks and close price reversals
- Easy to understand and implement
- Customizable MA parameters suit different periods and markets
Risks
- Dual MA strategies tend to produce more frequent trading signals
- Poor MA parameter tuning may miss longer trends
- Stop loss when breaking long term MAs may be distant, leading to larger drawdowns
- Cannot effectively filter out coils and oscillations
Enhancement Directions
- Add other indicators to avoid whipsaws in ranging markets
- Add stop loss mechanisms
- Optimize MA parameter combinations
- Dynamically tune MA parameters based on market cycle
Summary
The strategy overall has clear, easy to understand logic, using fast and slow MA reversals to detect trend reversal points. In theory it can effectively track trends. But in actual implementation it still needs optimization of the algorithm itself and tuning of parameters to make it more robust and practical.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 77 | Long MA Input |
| v_input_2 | 7 | Short MA Input |
| v_input_3 | 2017 | Backtest Start Year |
| v_input_4 | true | Backtest Start Month |
| v_input_5 | 2 | Backtest Start Day |
| v_input_6 | 2019 | Backtest Stop Year |
| v_input_7 | 7 | Backtest Stop Month |
| v_input_8 | 30 | Backtest Stop Day |
| v_input_9 | true | Color Background? |
Source Pine Script
/*backtest
start: 2022-11-15 00:00:00
end: 2023-11-21 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("Up Down", "Up Down", precision = 6, pyramiding = 1, default_qty_type = strategy.percent_of_equity, default_qty_value = 99, commission_type = strategy.commission.percent, commission_value = 0.0, initial_capital = 1000, overlay = true)

buy = close > open and open > close[1]
sell = close < open and open < close[1]

longma = input(77,"Long MA Input")
shortma = input(7,"Short MA Input")
long = sma(close,longma)
short = sma(close, shortma)
mabuy = crossover(short,long) or buy and short > long
masell = crossunder(short,long) or sell and short > long

num_bars_buy = barssince(mabuy)
num_bars_sell = barssince(masell)
//plot(num_bars_buy, color = teal)
//plot(num_bars_sell, color = orange)

xbuy = crossover(num_bars_sell, num_bars_buy)
xsell = crossunder(num_bars_sell, num_bars_buy)
plotshape(xbuy,"Buy Up Arrow", shape.triangleup, location.belowbar, white, size = size.tiny)
plotshape(xsell,"Sell Down Arrow", shape.triangledown, location.abovebar, white, size = size.tiny)
plot(long,"Long MA", fuchsia, 2)

// Component Code Start
// Example usage:
// if testPeriod()
//   strategy.entry("LE", strategy.long)
testStartYear = input(2017, "Backtest Start Year")
testStartMonth = input(01, "Backtest Start Month")
testStartDay = input(2, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,0,0)

testStopYear = input(2019, "Backtest Stop Year")
testStopMonth = input(7, "Backtest Stop Month")
testStopDay = input(30, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay,0,0)

// A switch to control background coloring of the test period
testPeriodBackground = input(title="Color Background?", type=bool, defval=true)
testPeriodBackgroundColor = testPeriodBackground and (time >= testPeriodStart) and (time <= testPeriodStop) ? #00FF00 : na
bgcolor(testPeriodBackgroundColor, transp=97)

testPeriod() => true
// Component Code Stop

if testPeriod()
    strategy.entry("buy", true, when = xbuy, limit = close)
    strategy.close("buy", when = xsell)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Reversal-Strategy-432848.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 3 10 Oscillator Profile Flagging StrategyPine Script · Mean reversion · 1d
- A Trend Reversal Strategy Based on Moving Averages Price Patterns and VolumePine Script · Mean reversion · 1d
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d