Strategy vault / Mean reversion
Dual Moving Average Reversal Trading Strategy 438787
The dual moving average reversal trading strategy combines the Bollinger Bands reversal trading strategy and the dual exponential moving average trading strategy to design a comprehensive signal judgment trading…
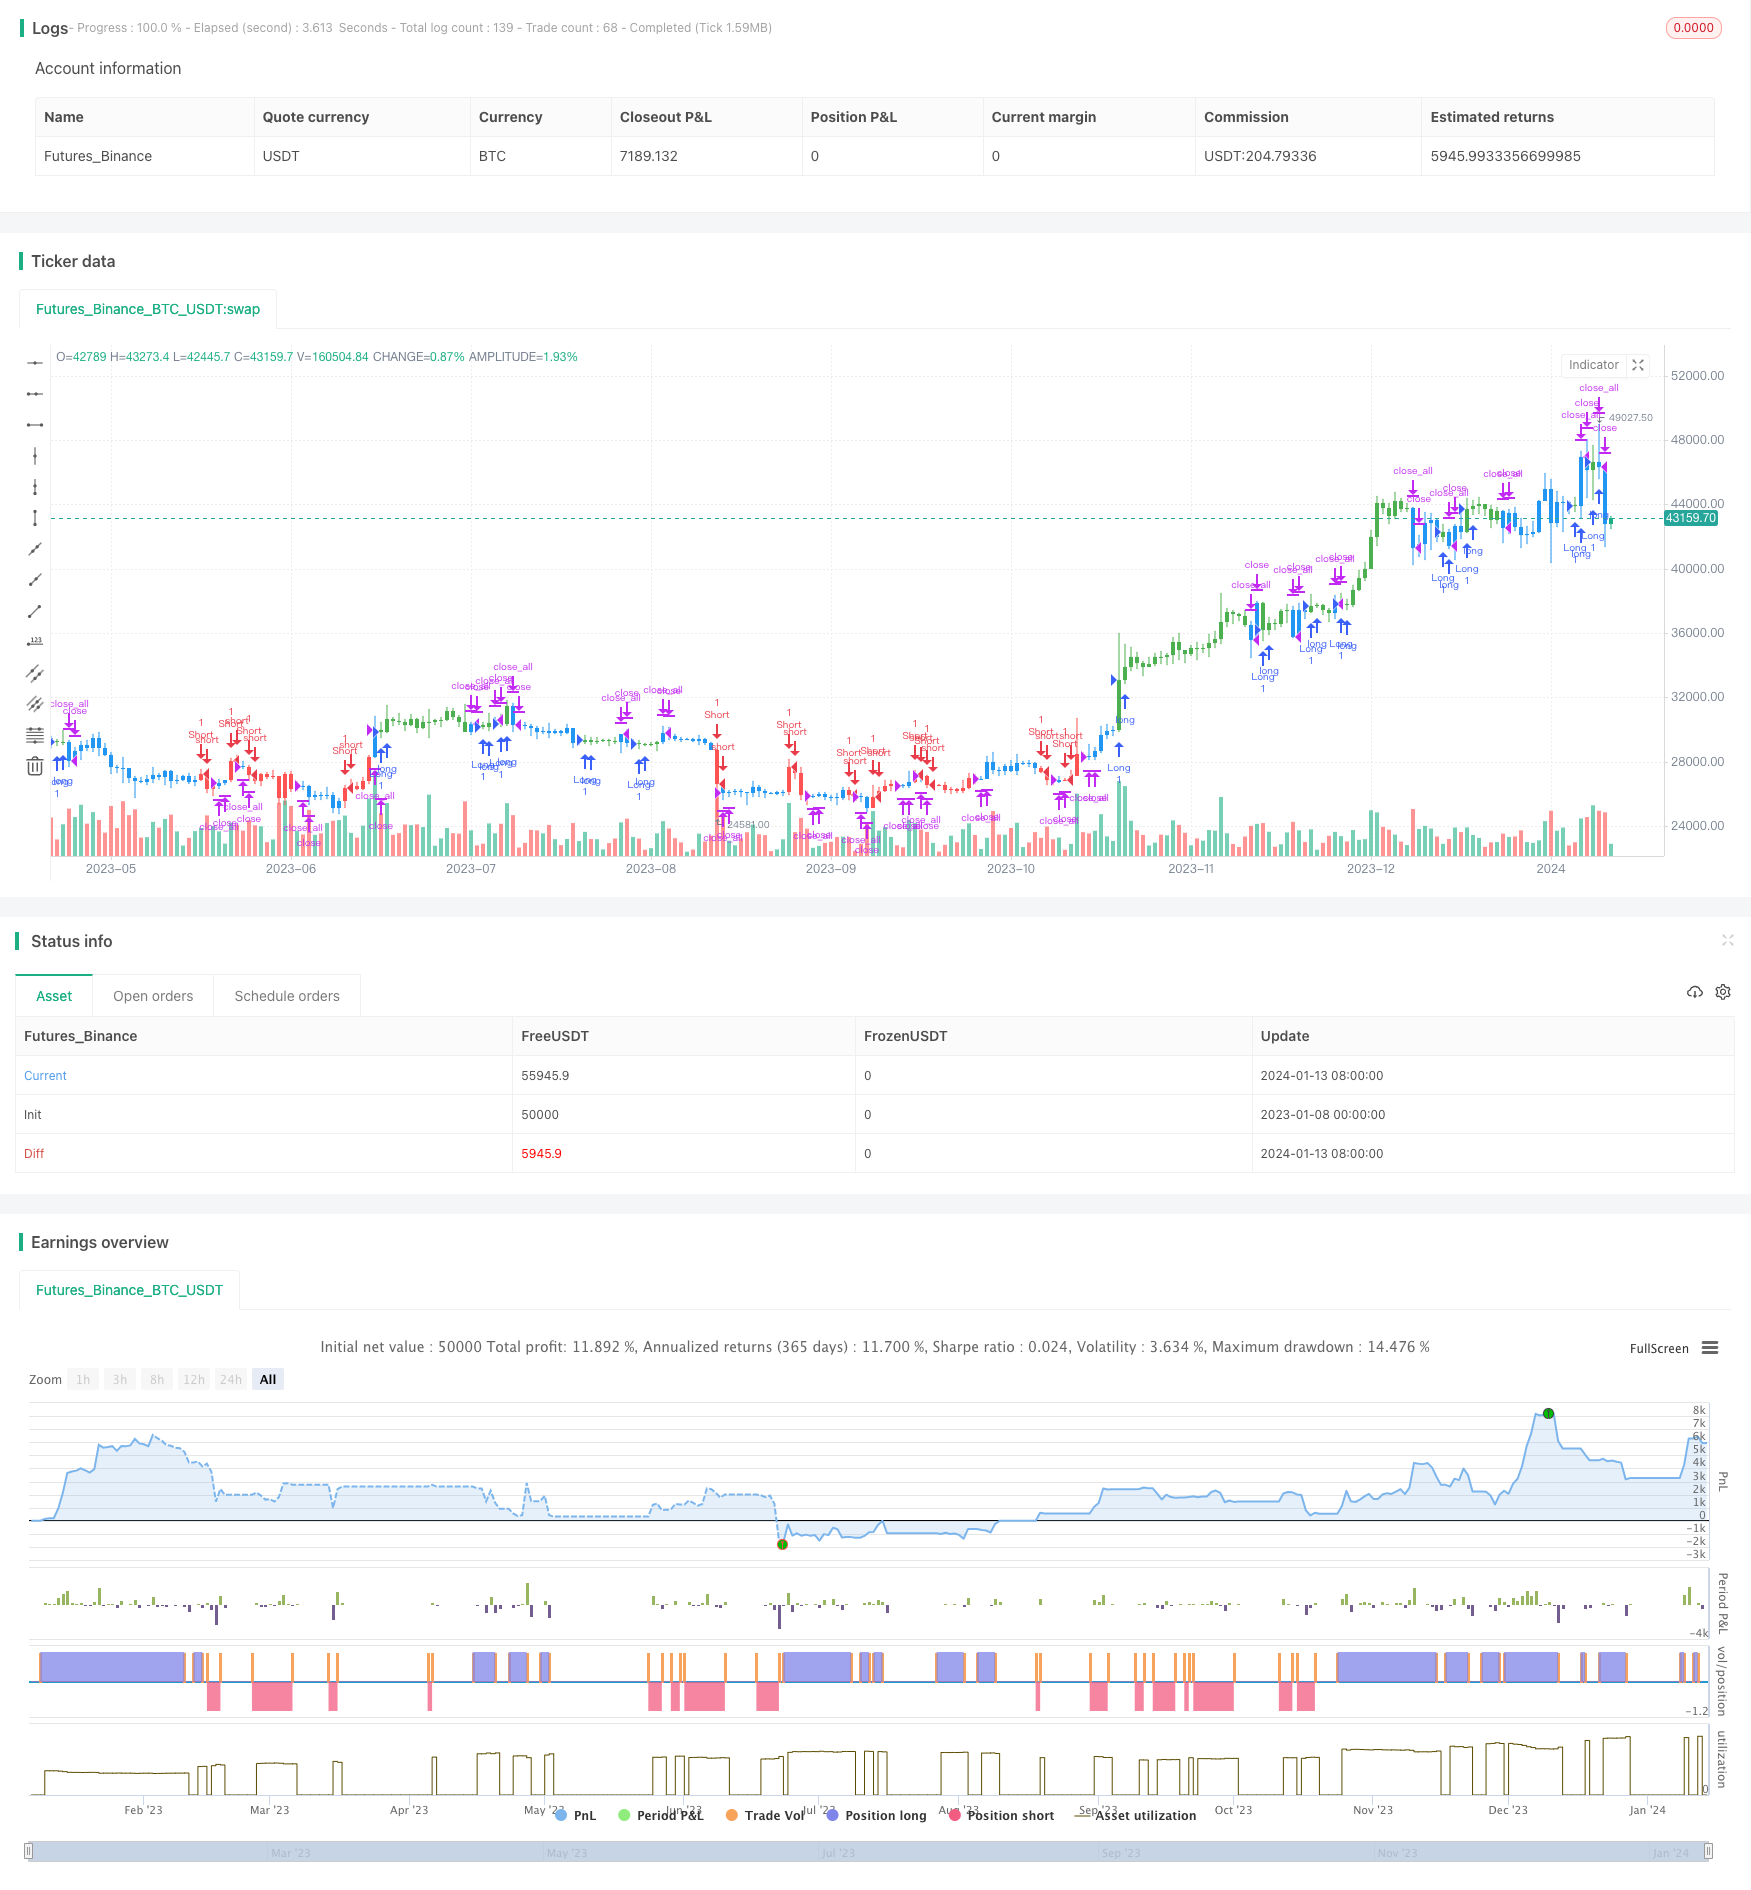
Overview
The dual moving average reversal trading strategy combines the Bollinger Bands reversal trading strategy and the dual exponential moving average trading strategy to design a comprehensive signal judgment trading strategy. It can be used in markets like stocks, forex, and cryptocurrencies.
Strategy Principles
The strategy consists of two parts:
Bollinger Bands reversal trading strategy
Use two lines from the Bollinger Bands indicator - %K line and %D line. Go long when the close price is lower than the previous day's close for two consecutive days and the %K line is above the %D line; go short when the close price is higher than the previous day's close for two consecutive days and the %K line is below the %D line.
Dual exponential moving average strategy
Calculate the 20-day and 20-day*2 dual exponential moving averages. A trading signal is generated when the price crosses over or under the dual moving averages.
The combined signal judgment rule: A actual trading signal is generated only when the trading signals from both strategies agree.
Advantage Analysis
The biggest advantage of this combined strategy is its high reliability and few false signals. Because it requires the signals from two different types of strategies to trigger at the same time, which filters out some of the false signals that may appear in a single strategy.
In addition, by combining reversal and trend strategies, it can capture both short-term reversals and medium-term trends of the underlying securities.
Risk Analysis
The main risk of this strategy is that when the market is in long-term oscillation, the two strategies may fail to produce consistent signals, resulting in invalid market conditions. At this point, traders need to suspend the use of this strategy and wait for a clear trend to form.
In addition, as a medium and long-term indicator, the dual moving average may fail when short-term reversals occur rapidly. This requires traders to judge the broader market trend with more indicators.
Optimization Directions
The strategy can be optimized in the following ways:
Add more parameters like stop loss price, trailing stop loss price range etc to make the strategy more controllable.
Add more indicators to form multiple filter criteria and eliminate more noisy trades. For example, combine with MACD, KD and other indicators.
Optimize indicator parameters like Bollinger period, moving average period etc, to find the best parameter combination.
Test the effectiveness of this strategy respectively in different products (stocks, forex, crypto etc) and select the best suitable ones.
Conclusion
The dual moving average reversal strategy generates relatively reliable combined trading signals by combining reversal and trend strategies. It suits traders who are interested in both short-term reversals and medium-term trends of the securities' prices. But note that the strategy may fail in long-term range-bound markets. By optimizing parameters and adding more indicators, the practicality of this strategy can be further enhanced.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | Length |
| v_input_2 | true | KSmoothing |
| v_input_3 | 3 | DLength |
| v_input_4 | 50 | Level |
| v_input_5 | 20 | MA_Length |
| v_input_6 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2023-01-08 00:00:00
end: 2024-01-14 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 12/04/2019
// This is combo strategies for get
// a cumulative signal. Result signal will return 1 if two strategies
// is long, -1 if all strategies is short and 0 if signals of strategies is not equal.
//
// First strategy
// This System was created from the Book "How I Tripled My Money In The
// Futures Market" by Ulf Jensen, Page 183. This is reverse type of strategies.
// The strategy buys at market, if close price is higher than the previous close
// during 2 days and the meaning of 9-days Stochastic Slow Oscillator is lower than 50.
// The strategy sells at market, if close price is lower than the previous close price
// during 2 days and the meaning of 9-days Stochastic Fast Oscillator is higher than 50.
//
// Secon strategy
// This indicator plots 2/20 exponential moving average. For the Mov
// Avg X 2/20 Indicator, the EMA bar will be painted when the Alert criteria is met.
// Please, use it only for learning or paper trading. Do not for real trading.
//
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
Reversal123(Length, KSmoothing, DLength, Level) =>
    vFast = sma(stoch(close, high, low, Length), KSmoothing)
    vSlow = sma(vFast, DLength)
    pos = 0.0
    pos := iff(close[2] < close[1] and close > close[1] and vFast < vSlow and vFast > Level, 1,
	         iff(close[2] > close[1] and close < close[1] and vFast > vSlow and vFast < Level, -1, nz(pos[1], 0)))
	pos

EMA2_20(MA_Length, MA_xPrice) =>
    xXA = ema(MA_xPrice, MA_Length)
    nHH = max(high, high[1])
    nLL = min(low, low[1])
    nXS = iff((nLL > xXA)or(nHH < xXA), nLL, nHH)
    pos = 0.0
    pos := iff(nXS > close[1] , -1, iff(nXS < close[1] , 1, nz(pos[1], 0)))
    pos

strategy(title="Combo Backtest 123 Reversal and 2/20 EMA", shorttitle="Combo Backtest", overlay = true)
Length = input(14, minval=1)
KSmoothing = input(1, minval=1)
DLength = input(3, minval=1)
Level = input(50, minval=1)
MA_Length = input(20, minval=1)
reverse = input(false, title="Trade reverse")
MA_xPrice = close
posReversal123 = Reversal123(Length, KSmoothing, DLength, Level)
posEMA2_20 = EMA2_20(MA_Length, MA_xPrice)
pos = iff(posReversal123 == 1 and posEMA2_20 == 1 , 1,
	   iff(posReversal123 == -1 and posEMA2_20 == -1, -1, 0))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1, 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close_all()
barcolor(possig == -1 ? red: possig == 1 ? green : blue ) Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-15. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Reversal-Trading-Strategy-438787.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Intraday Single Candle Indicator Combo Short Term Trading StrategyPine Script · Mean reversion · 1d
- Bollinger Bands RSI MACD and Stochastic Multi indicator Fusion Trading StrategyPine Script · Mean reversion · 1d
- Multi indicator Strategy to Identify Trading Inflection Points in Quant TradingPine Script · Mean reversion · 1h
- A Momentum Tracking Mean Reversion StrategyPine Script · Mean reversion · 1h
- Multi Indicator EMA StrategyPine Script · Mean reversion · 4h