Dual Moving Average Stochastic Indicator Binary Options Trading Strategy
This strategy combines dual moving averages and the Stochastic indicator to implement a simple and effective binary options trading strategy. It uses the EMA of high prices, EMA of low prices and EMA of closing…
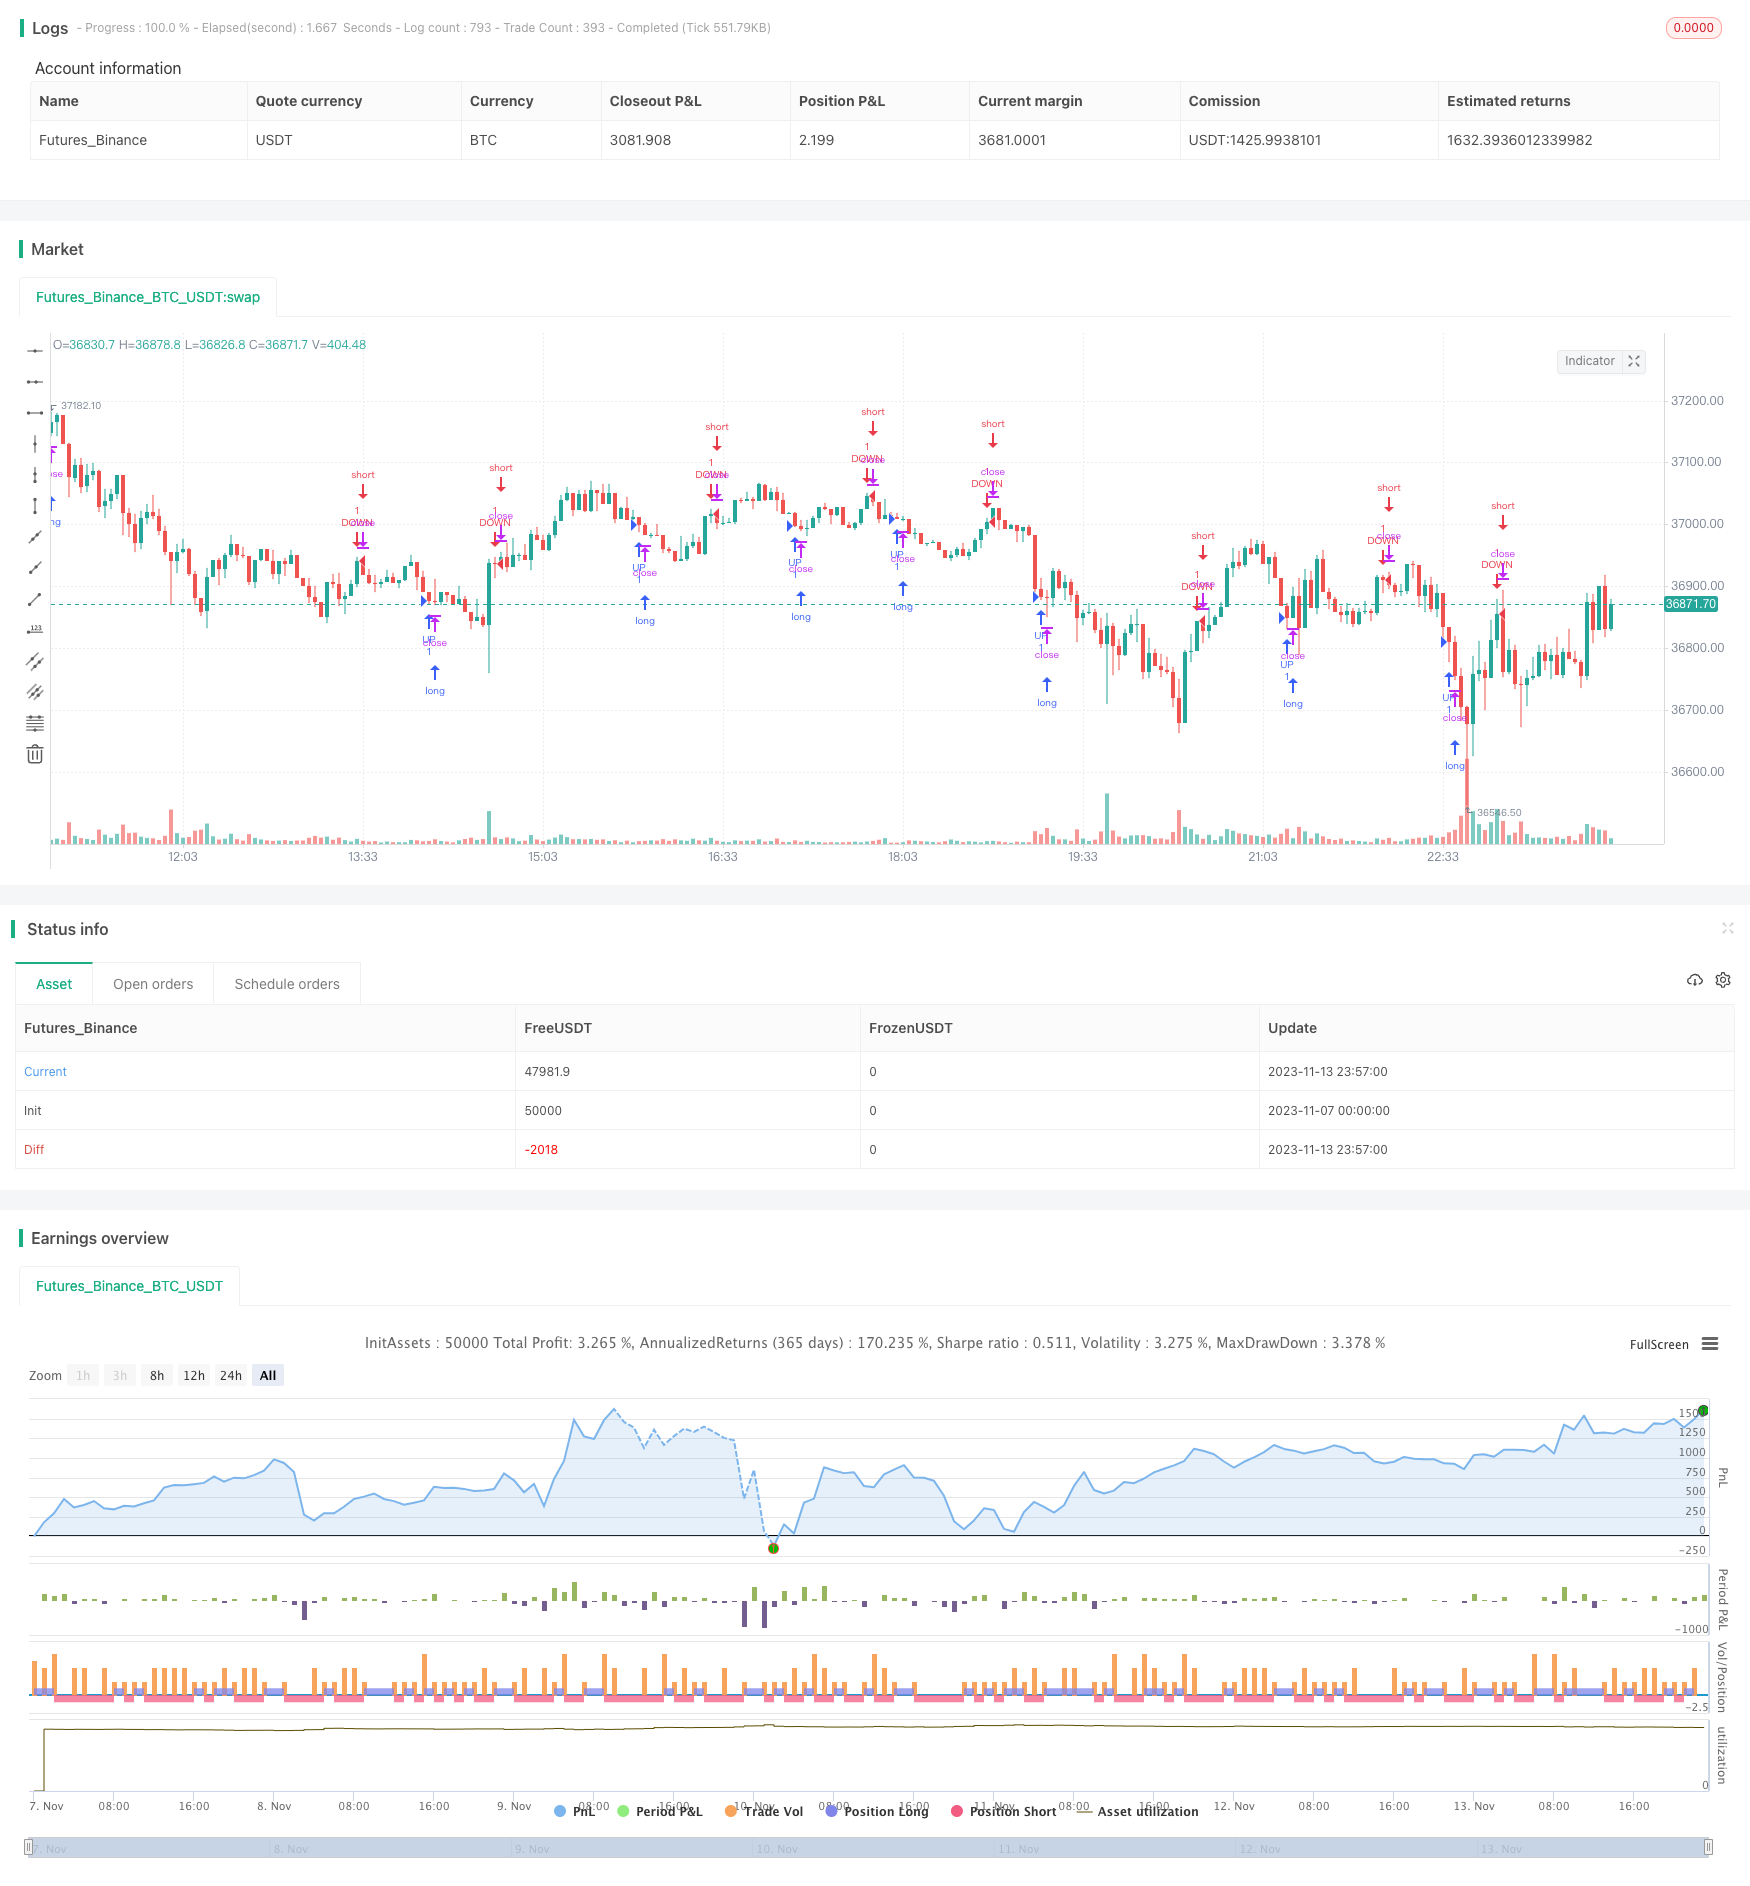
Overview
This strategy combines dual moving averages and the Stochastic indicator to implement a simple and effective binary options trading strategy. It uses the EMA of high prices, EMA of low prices and EMA of closing prices to build a dual moving average system, and incorporates the Stochastic indicator to generate trading signals, in order to capture short-term price fluctuations in binary options.
Principles
The strategy is mainly based on the following principles:
Use the EMA of high prices and EMA of low prices to build upper and lower bands as support and resistance levels.
Calculate the EMA of closing prices to determine the relationship between price and dual moving averages. If the closing price crosses above the upper band or breaks below the lower band, it indicates a possible trend reversal.
The Stochastic indicator determines overbought and oversold conditions. K and D values below 50 indicate oversold while above 50 overbought.
According to the overbought/oversold signals from Stochastic combined with price breakouts of the upper/lower bands, short-term buy/sell operations can be executed.
The specific trading rules are:
If the closing price is below the lower band and the opening price is below the midpoint of the dual moving averages, while Stochastic shows oversold (K<50, D<50), go long.
If the closing price is above the upper band and the opening price is above the midpoint of the dual moving averages, while Stochastic shows overbought (K>50, D>50), go short.
Advantage Analysis
By combining dual moving averages and the Stochastic oscillator, this strategy can effectively capture short-term trend reversals in binary options prices, with the following advantages:
The moving average system filters out consolidation while Stochastic increases accuracy by determining overbought/oversold levels.
The trading rules are simple and clear, easy to implement.
High capital utilization efficiency, only hold one direction at a time.
Controllable drawdowns, avoid unnecessary losses.
Easy to optimize by adjusting moving average parameters and Stochastic inputs.
Risk Analysis
Although this strategy has some merits, it also has the following risks:
There is a probability of false breakouts with the dual moving averages, potentially missing strong trends or reversals.
Stochastic has lagging issues, signals may come after trend reversals have already begun.
Cannot adapt to highly volatile markets, should avoid major events.
Improper parameter settings may lead to excessive trading frequency or insufficient signals.
Unable to accurately predict binary option price movements, has inherent loss risks.
Corresponding risks can be reduced by adjusting parameters, optimizing rules and strict stop loss. In addition, account size and stop loss levels should match to control single trade loss amount and maximum drawdown.
Optimization Directions
There is further optimization potential for this strategy:
Add other indicators for filtration, like MACD, RSI etc, to improve signal accuracy.
Incorporate trend indicators to avoid counter-trend trading.
Optimize moving average parameters to find the best length combinations.
Adjust overbought/oversold criteria to reduce Stochastic lag.
Set dynamic or trailing stop loss.
Combine relevant technical analysis tools to find optimal entry timing.
Test spread trading feasibility across different products.
Through the above optimization means, strategy stability and profitability can be further enhanced.
Conclusion
This strategy integrates the advantages of dual moving averages and Stochastic oscillator into a simple and reliable short-term binary options trading strategy. It standardizes trading rules for better risk control. Although there is still room for improvement, its logic is clear and easy to implement, making it a viable choice worth considering. By optimizing parameters and rules, better strategy performance may be achieved.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | length1 |
| v_input_2 | true | smoothK |
| v_input_3 | 3 | smoothD |
| v_input_4 | 4 | Length |
| v_input_5_high | 0 | Source: high | close | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_6 | 4 | Length |
| v_input_7_low | 0 | Source: low | high | close | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_8 | 21 | Length |
| v_input_9_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
Source Pine Script
/*backtest
start: 2023-11-07 00:00:00
end: 2023-11-14 00:00:00
period: 3m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy("Binary Option EMA/Stoch strategy Corrected", overlay=true)

//stoch

length1 = input(14, minval=1), smoothK = input(1, minval=1), smoothD = input(3, minval=1)
k = sma(stoch(close, high, low, length1), smoothK)
d = sma(k, smoothD)


len = input(4, minval=1, title="Length")
src = input(high, title="Source")
out = ema(src, len)
HIGH = out

len1 = input(4, minval=1, title="Length")
src1 = input(low, title="Source")
out1 = ema(src1, len1)
LOW = out1


HL2 = (HIGH+LOW)/2

len2 = input(21, minval=1, title="Length")
src2 = input(close, title="Source")
out2 = ema(src2, len2)
EMA = out2


x = close < LOW and open < HL2 and close < EMA  and d < 50 and k < 50

y =   close > HIGH and open > HL2 and close > EMA and d > 50 and k > 50

if (x)
    strategy.entry("UP", strategy.long)

if (y)
    strategy.entry("DOWN", strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-15. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Stochastic-Indicator-Binary-Options-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual Moving Average and MACD Combination Short term Trading StrategyPine Script · Breakout · 1h
- Multi Period Dynamic Signal Integration ICT Smart Structure Breakthrough StrategyPine Script · Breakout · 2d
- Price Breakthrough Bollinger Band A StrategyPine Script · Breakout · 1m
- Momentum Breakout Intraday Trading StrategyPine Script · Breakout · 5m
- Multi Indicator Trend Following and Volatility Breakout StrategyPine Script · Breakout · 2h
- Bull Market Tracking SystemPine Script · Breakout · 1h