Strategy vault / Mean reversion
Dual Moving Average Stochastic Strategy
The Dual Moving Average Stochastic strategy attempts to identify trading opportunities using a combination of moving average indicators and the stochastic oscillator. It generates trade signals when the fast EMA…
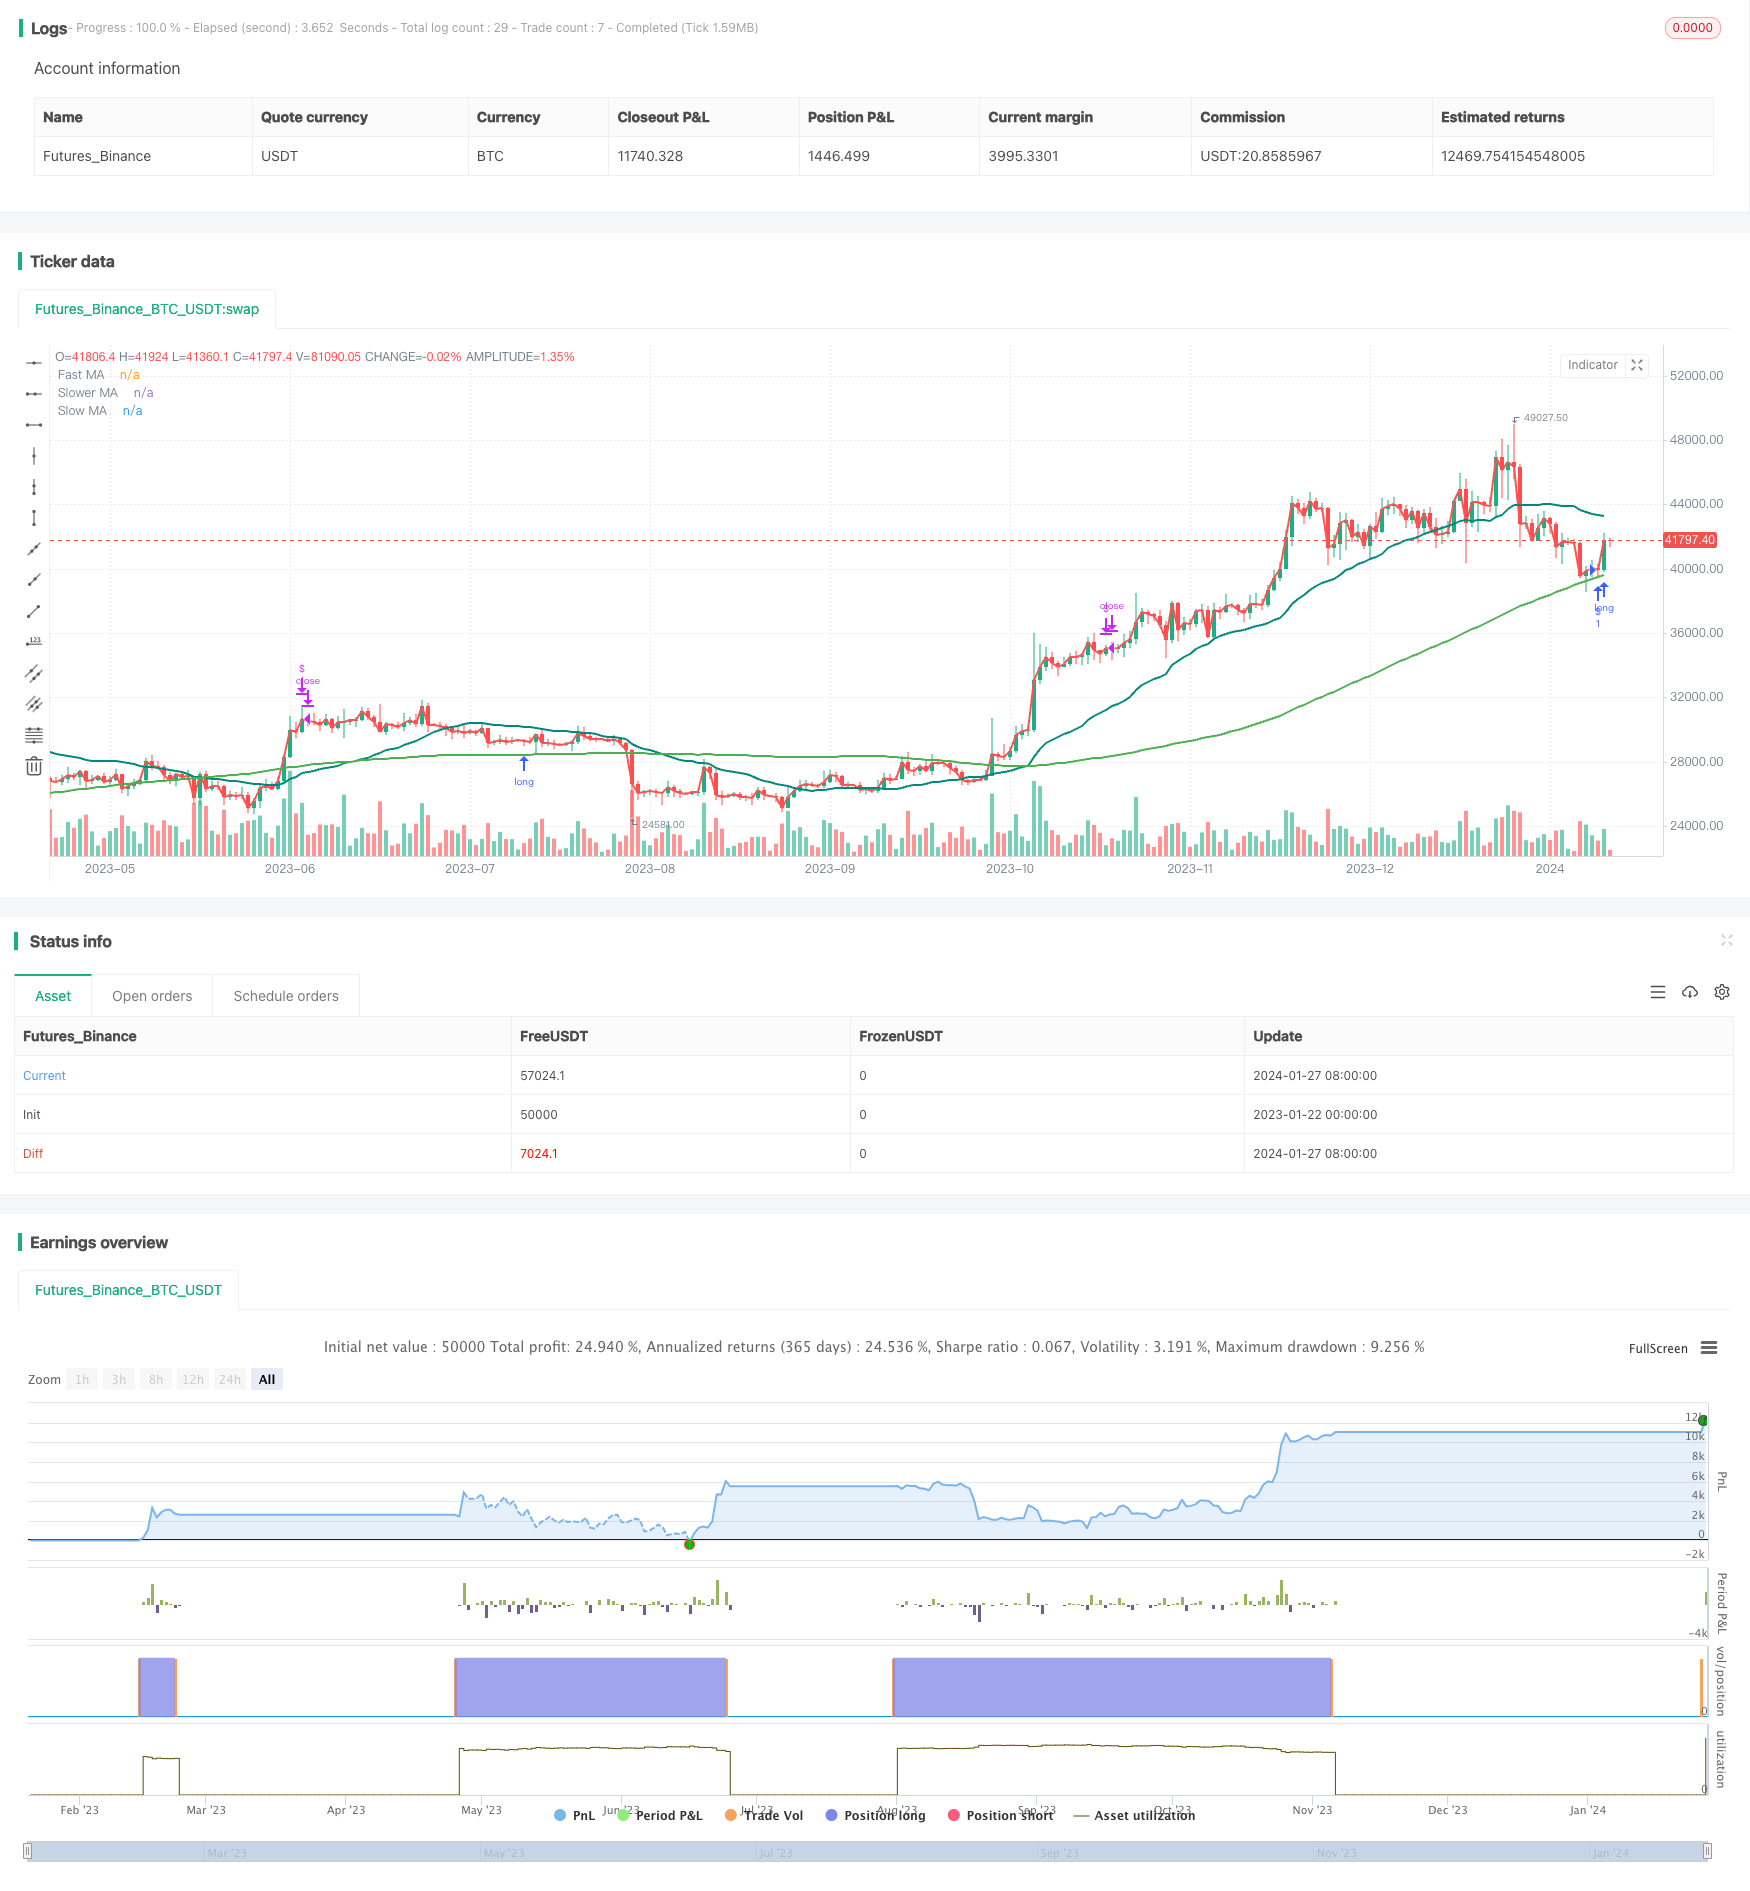
Overview
The Dual Moving Average Stochastic strategy attempts to identify trading opportunities using a combination of moving average indicators and the stochastic oscillator. It generates trade signals when the fast EMA crosses above or below the slow SMA, while also using the stochastic %K value to filter out signals when the market is overextended.
Strategy Logic
The strategy is primarily based on two technical indicators:
Moving Averages: It computes a fast EMA, slow SMA and slow VWMA using different parameters, and generates trade signals when the fast EMA crosses the slow SMA.
Stochastic Oscillator: It calculates the %K value and considers the market overbought or oversold when %K crosses preset upper or lower threshold levels, using this to filter some of the moving average signals.
Specifically, the logic for signal generation is:
When the fast EMA crosses above the slow SMA, and %K is below the oversold level, go long. When the fast EMA crosses below the slow SMA, and %K is above the overbought level, go short.
For existing long positions, close when %K re-enters the overbought zone or price breaches the stop loss. For short positions, close when %K re-enters the oversold zone or price breaches the stop loss.
By combining moving averages and the stochastic oscillator, the strategy attempts to identify high probability moving average signal points to enter trades, while using the stochastic to filter out some of the false signals.
Advantage Analysis
The main advantages of this strategy are:
- Combining multiple technical indicators provides more comprehensive judgment versus using a single indicator.
- Filtering with the stochastic oscillator avoids some false signals.
- Using multiple moving averages with mixed parameters allows for more robust signals.
- Incorporates a stop loss mechanism to control single trade loss.
Risk Analysis
There are also some risks:
- Moving averages can generate many uncertain signals resulting in more false entries; limited stop loss capability.
- Stochastic oscillator may also produce incorrect signals on its own.
- Parameter settings require optimization (e.g. overbought/oversold levels, moving average periods) otherwise performance impact.
- Lack of fundamental analysis.
Mitigations:
- Optimize parameters to find best combination of indicator settings.
- Use smaller position sizing, scale in.
- Incorporate fundamental analysis to avoid events.
Enhancement Opportunities
The main optimization opportunities are:
- Test and optimize moving average parameters to find optimum.
- Test stochastic parameters like overbought/oversold zones for optimum settings.
- Incorporate additional indicators like volume or volatility for richer entry logic.
- Enhance stop loss methodology e.g. trailing stops to lower risk.
- Improve money management such as dynamic position sizing based on ATR.
- Avoid risk-off events using VIX etc.
Conclusion
The Dual Moving Average Stochastic Strategy utilizes a blend of moving averages and the stochastic oscillator to design a robust trend following system, but has some enhancement opportunities around parameters, stops etc. Further refinements like additional indicators and optimizations can potentially deliver more consistent alpha.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 16 | length |
| v_input_2 | 80 | OverBought |
| v_input_3 | 20 | OverSold |
| v_input_4 | true | TradeLong |
| v_input_5 | true | TradeShort |
| v_input_6 | 80 | OverBoughtClose |
| v_input_7 | 20 | OverSoldClose |
| v_input_8 | 50 | trail_points |
| v_input_9_close | 0 | Fast EMA Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_10 | true | Fast EMA Period |
| v_input_11_close | 0 | Slow SMA Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_12 | 100 | Slow SMA Period |
| v_input_13_close | 0 | Slower SMA Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_14 | 30 | Slower SMA Period |
| v_input_15 | 7 | ATR Days Lookback |
| v_input_16 | 5 | ATR Modifier |
Source Pine Script
/*backtest
start: 2023-01-22 00:00:00
end: 2024-01-28 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("TVIX MEAN REV V2 TREND", overlay=true)
length = input(16, minval=1)
OverBought = input(80)
OverSold = input(20)
TradeLong = input (true)
TradeShort = input (true)

OverBoughtClose = input(80)
OverSoldClose = input(20)

smoothK = 3
smoothD = 3
trail_points = input(50)

k = sma(stoch(close, high, low, length), smoothK)
d = sma(k, smoothD)
k2 = sma(stoch(close, high, low, length), smoothK)
d2 = sma(k, smoothD)


// === GENERAL INPUTS ===
// short Ema
maFastSource = input(defval=close, title="Fast EMA Source")
maFastLength = input(defval=1, title="Fast EMA Period", minval=1)
// long Sma
maSlowSource = input(defval=close, title="Slow SMA Source")
maSlowLength = input(defval=100, title="Slow SMA Period", minval=1)
// longer Sma
maSlowerSource = input(defval=close, title="Slower SMA Source")
maSlowerLength = input(defval=30, title="Slower SMA Period", minval=1)

//ATR Stop Loss Indicator by Keith Larson
atrDays = input(7, "ATR Days Lookback")
theAtr = atr(atrDays)
atrModifier = input(5.0, "ATR Modifier")
//plot(atr * atrModifier, title="ATR")

LstopLoss = close - (theAtr * atrModifier)
SstopLoss = close + (theAtr * atrModifier)


// === SERIES SETUP ===
/// a couple of ma's..
maFast = ema(maFastSource, maFastLength)
maSlow = sma(maSlowSource, maSlowLength)
maSlower = vwma(maSlowerSource, maSlowerLength)
rsi = rsi(maSlowerSource, maSlowerLength)

// === PLOTTING ===
fast = plot(maFast, title="Fast MA", color=color.red, linewidth=2, style=plot.style_line, transp=30)
slow = plot(maSlow, title="Slow MA", color=color.green, linewidth=2, style=plot.style_line, transp=30)
slower = plot(maSlower, title="Slower MA", color=color.teal, linewidth=2, style=plot.style_line, transp=30)


// === LOGIC === Basic - simply switches from long to short and vice-versa with each fast-slow MA cross
LongFilter = maFast > maSlow
ShortFilter = maSlow > maFast


BUY=crossover(k, d) and k < OverSold
SELL=crossunder(k, d) and k > OverBought

SELLCLOSE=crossover(k, d) and k < OverSoldClose
BUYCLOSE=crossunder(k, d) and k > OverBoughtClose

Open = open


if not na(k) and not na(d)
    if crossover(k, d) and k < OverSold and LongFilter and TradeLong
        strategy.entry("$", strategy.long, limit = Open, comment="Long")

    strategy.close("$",when = crossunder(k, d) and k > OverBoughtClose or open < LstopLoss  )
    ///strategy.close("$",when = open < LstopLoss  )

if not na(k) and not na(d)
    if crossunder(k, d) and k > OverBought and ShortFilter and TradeShort
        strategy.entry("$1", strategy.short, limit = Open, comment="S")

    strategy.close ("$1", when = crossover(k, d) and k < OverSoldClose or open > SstopLoss  )
    ///strategy.close ("$1", when = open < SstopLoss)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Stochastic-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- Oma and Apollo Dual Rail Trading StrategyPine Script · Mean reversion · 5m
- 3EMA with Stochastic RSI StrategyPine Script · Mean reversion · 1h
- Multi Indicator Weighted Smart Trading StrategyPine Script · Mean reversion · 2d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d