Dual Stochastics and Volume Weighted Moving Average Combination Indicator Strategy
This is a strategy that utilizes a combination of dual Stochastics indicators and Volume Weighted Moving Average to identify trends. It uses two Stochastics indicators with different periods, one short-term and one…
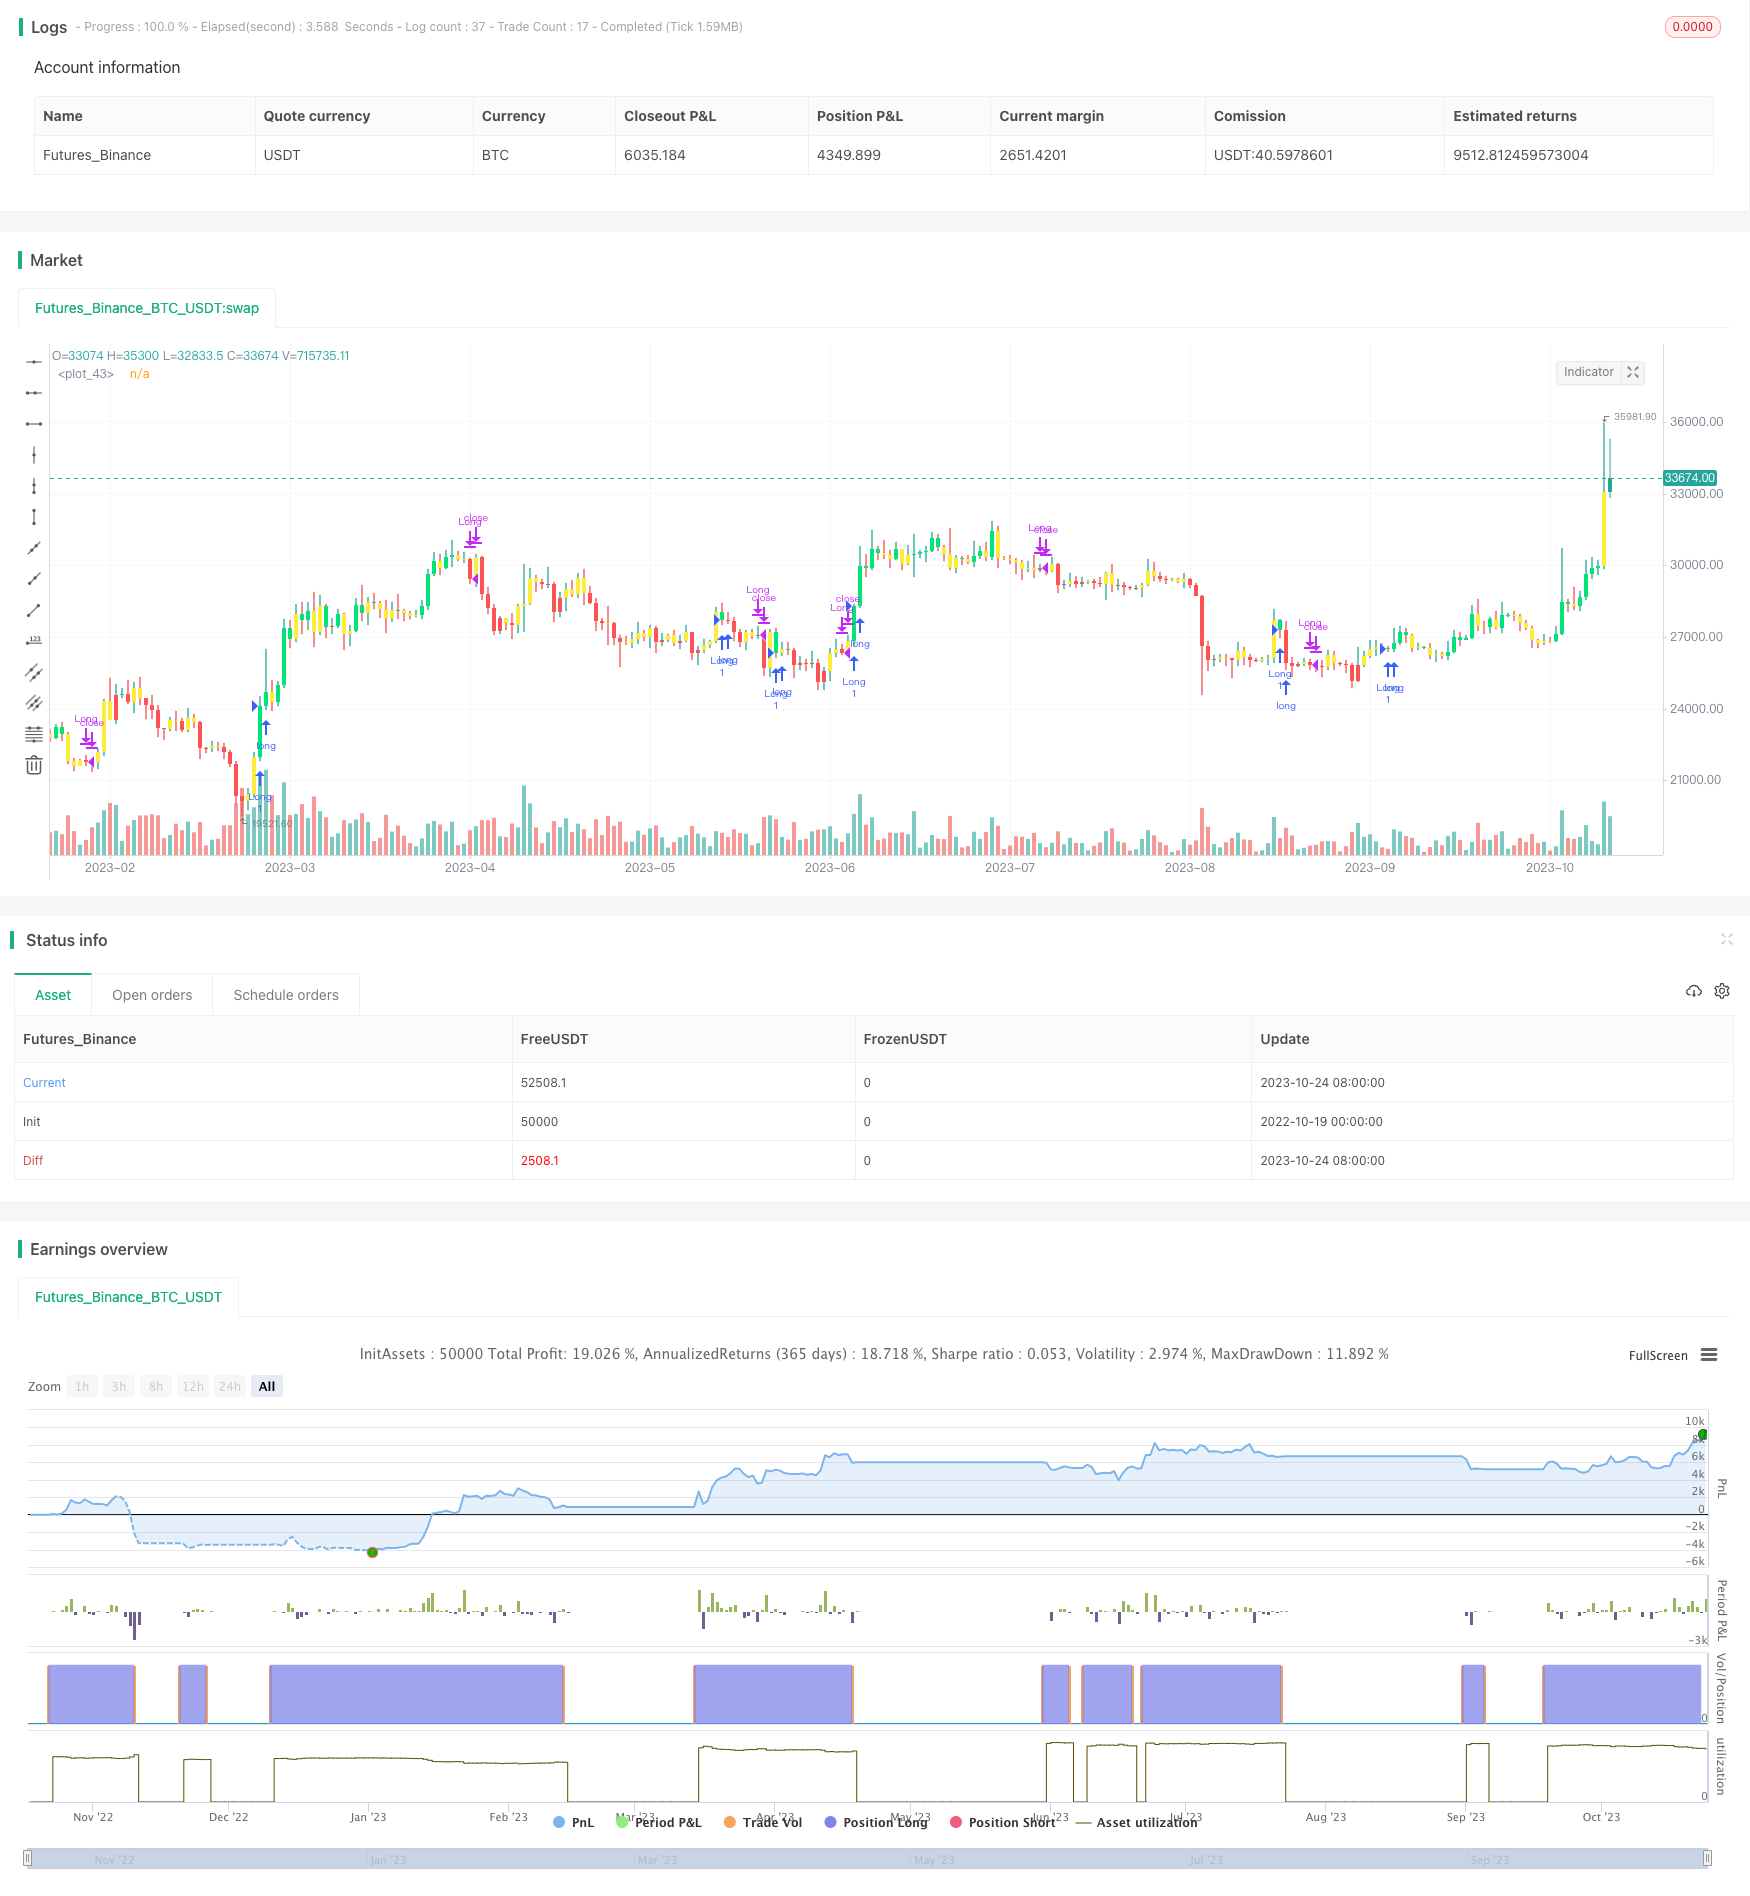
Overview
This is a strategy that utilizes a combination of dual Stochastics indicators and Volume Weighted Moving Average to identify trends. It uses two Stochastics indicators with different periods, one short-term and one long-term, combined with VWMA to determine the current trend direction.
Strategy Logic
The strategy mainly implements trend identification through the following parts:
Calculate a short-period Stochastics indicator with period length input(30) and smooth parameter 2
Calculate a long-period Stochastics indicator with period length input(90) and smooth parameter 2
Add the short-period and long-period Stochastics together to get a combined Stochastics curve ts
Calculate a Volume Weighted Moving Average of ts curve with period length input(30)
Compare current tsl value with its value 1 period ago, when tsl rises, it indicates an uptrend, when tsl falls, it indicates a downtrend
Combine with Stochastics curve position to identify bullish or bearish signals
- When tsl rises and ts is in middle zone, it is a bullish signal
- When tsl falls and ts is in middle zone, it is a bearish signal
Advantage Analysis
The strategy combines trend identification and overbought-oversold analysis, which can identify trend direction quite reliably. The advantages are:
The dual Stochastics can reflect both short-term and long-term overbought/oversold situations, avoiding missing some signals
Volume weighted moving average can filter out some false breakout signals
Stochastics curve position re-confirms the reliability of trend signals
Adjustable parameters suit different markets
Clear and simple logic, easy to understand and modify
Risks and Improvements
There are also some risks to note for this strategy:
Stochastics may give false signals, needs filtering with longer-period indicators
Fixed periods may not suit all markets, dynamic optimization could help
Purely technical indicator based, fundamentals may improve accuracy
Inaccurate volume data affects results, need to verify data quality
Insufficient backtesting history, more data needed for validation
Entry points can be improved, rather than direct long on crosses under lowest
Conclusion
In summary, this strategy identifies trends using dual Stochastics and VWMA, which can reliably identify trend reversals in theory. But parameter tuning is needed for specific markets, and false signals risk exists. Recommend combining other factors like fundamentals, long-term trends etc for judgment, to improve strategy Profit Factor. The logic is simple and clear, providing a template for quant trading, which can be modified as needed. It has great application value.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 30 | periodK |
| v_input_2 | 90 | periodK_two |
| v_input_3 | 30 | VWMA Length |
Source Pine Script
/*backtest
start: 2022-10-19 00:00:00
end: 2023-10-25 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title="Trend Finder V2", shorttitle="TFV2", format=format.price, precision=2, overlay = true)

//----------Indicator------------//

periodK = input(30)
periodD = 3
smoothK = 2

periodK_two = input(90)
periodD_two = 3
smoothK_two = 2

k = sma(stoch(close, high, low, periodK), smoothK)
d = sma(k, periodD)

k_two = sma(stoch(close, high, low, periodK_two), smoothK_two)
d_two = sma(k, periodD_two)

ts = k + k_two
tsl = vwma(ts, input(30, title = "VWMA Length"))

//--------Label parameter--------//

up_label = tsl[1] < 100 and tsl > 100 ? 1 : 0
down_label = tsl[1] > 100 and tsl < 100 ? 1 : 0

//----------Color Code-----------//

//tsl_col = tsl > 100 and tsl > tsl[1] ? color.aqua : tsl > 100 and tsl < tsl[1] ? color.green : tsl < 100 and tsl > tsl[1] ? color.maroon : tsl < 100 and tsl < tsl[1] ? color.red : color.silver

//tsl_col = tsl > 100 and ts < 100 and ts > ts[1] ? color.aqua : tsl > 100 and ts > 100 and (ts > ts[1] or ts < ts[1]) ? color.green : tsl < 100 and ts > 100 and ts < ts[1] ? color.red : tsl < 100 and ts < 100 and (ts < ts[1] or ts > ts[1]) ? color.maroon : color.purple

tsl_col = ts > ts[1] and tsl > tsl[1] ? color.lime : ts < ts[1] and tsl < tsl[1] ? color.red : color.yellow

ts_col = (tsl_col == color.lime or tsl_col == color.maroon) and (k>k[1] and k < 30) ? color.lime :  (tsl_col == color.green or tsl_col == color.red) and (k < k[1] and k > 70)  ? color.red : color.silver

//-------------Plots-------------//

buy = tsl_col[1] == color.yellow and tsl_col == color.lime ? 1 : 0
sell = tsl_col[1] == color.yellow and tsl_col == color.red ? -1 : 0

plotcandle(open,high,low,close, color=tsl_col)

strategy.entry("Long", strategy.long,when=buy==1)
strategy.close("Long", when=sell==-1)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Stochastics-and-Volume-Weighted-Moving-Average-Combination-Indicator-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bull Market Tracking SystemPine Script · Breakout · 1h
- Dynamic Stop Loss Strategy Adaptive to ATR FluctuationsPine Script · Breakout · 1h
- Moving Stop Loss Tracking StrategyPine Script · Breakout · 1d
- Quantitative Strategy PSARZigZagMACDART Based on Multi Indicator CombinationPine Script · Breakout · 1m
- Quantitative Trading Price Breakthrough StrategyPine Script · Breakout · 1d
- Reversal Breakout Bandpass Combo StrategyPine Script · Breakout · 1h