Strategy vault / Mean reversion
Dual Thrust MyLanguage version
- Fundamental: At the close of the day, two values are calculated: the highest price - the closing price, and the closing price - the lowest price. Then take the larger one and multiply it by the value of k. The…
Fundamental: At the close of the day, two values are calculated: the highest price - the closing price, and the closing price - the lowest price. Then take the larger one and multiply it by the value of k. The result is called the trigger value. At the opening of the next day, record the opening price, then buy immediately when the price exceeds (opening price + trigger value), or sell short when the price is lower than (opening price - trigger value). This system is a reversal system with no separate stop loss. In other words, the reverse signal is also the closing signal.

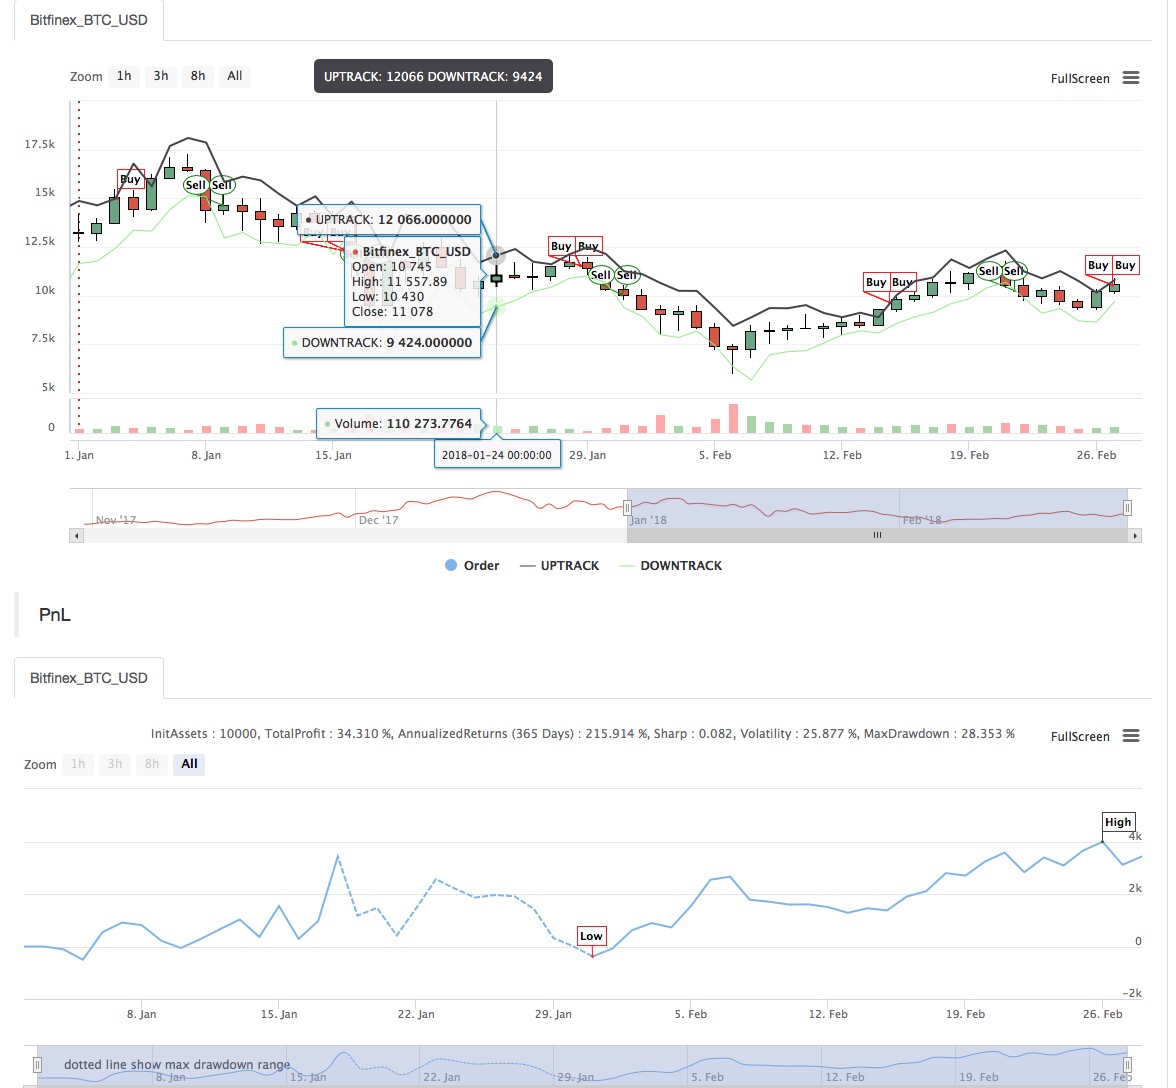
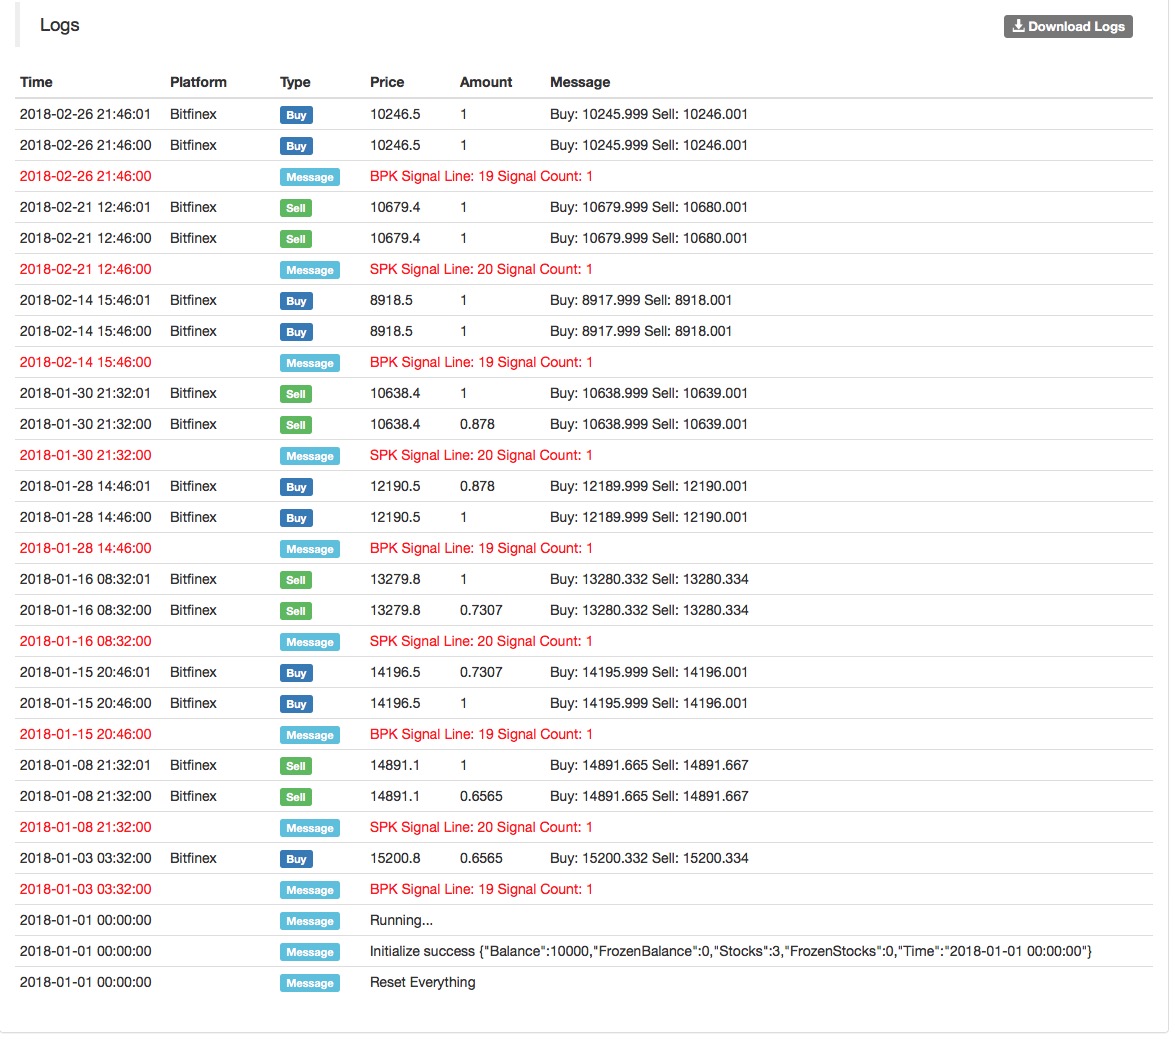
Main chart: Upper track: formula: UPTRACK^^O+KSRG; Lower track: formula: DOWNTRACK^^O-KXRG;
Secondary chart: none
Parameters
| Name | Default | What it controls |
|---|---|---|
| N | 4 | Calculation cycle | Period: calculate period |
| KS | 0.5 | Upper rail coefficient | upper track coefficient |
| KX | 0.5 | Lower rail coefficient | lower track coefficient |
Source MyLanguage
(*backtest
start: 2018-01-01 00:00:00
end: 2018-02-28 00:00:00
period: 1d
exchanges: [{"eid":"Futures_OKCoin","currency":"BTC_USD"}]
args: [["ContractType","this_week",126961]]
*)

HH:=HV(H,N);
HC:=HV(C,N);
LL:=LV(L,N);
LC:=LV(C,N);

RG:=MAX(HH-LC,HC-LL);
UPTRACK^^O+KS*RG;
DOWNTRACK^^O-KX*RG;


C>UPTRACK,BPK;
C<DOWNTRACK,SPK;
Published by 阿基米德的浴缸 on the FMZ strategy square · last modified 2019-08-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Thrust-MyLanguage-version.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 1 2 3 Pattern Quantitative Trading Strategy with EMAs MACD and 4th Candle ExtensionPine Script · Mean reversion · 1h
- 3 10 Oscillator Profile Flagging StrategyPine Script · Mean reversion · 1d
- A Trend Reversal Strategy Based on Moving Averages Price Patterns and VolumePine Script · Mean reversion · 1d
- ATR and EMA based Dynamic Take Profit and Stop Loss Adaptive StrategyPine Script · Mean reversion · 1h
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Adaptive Moving Average Tracking StrategyPine Script · Mean reversion · 1d