Dual Timeframe Stochastic Momentum Trading Strategy
This strategy is a dual timeframe momentum trading system based on the Stochastic indicator. It identifies potential trading opportunities by analyzing Stochastic crossover signals across different timeframes…
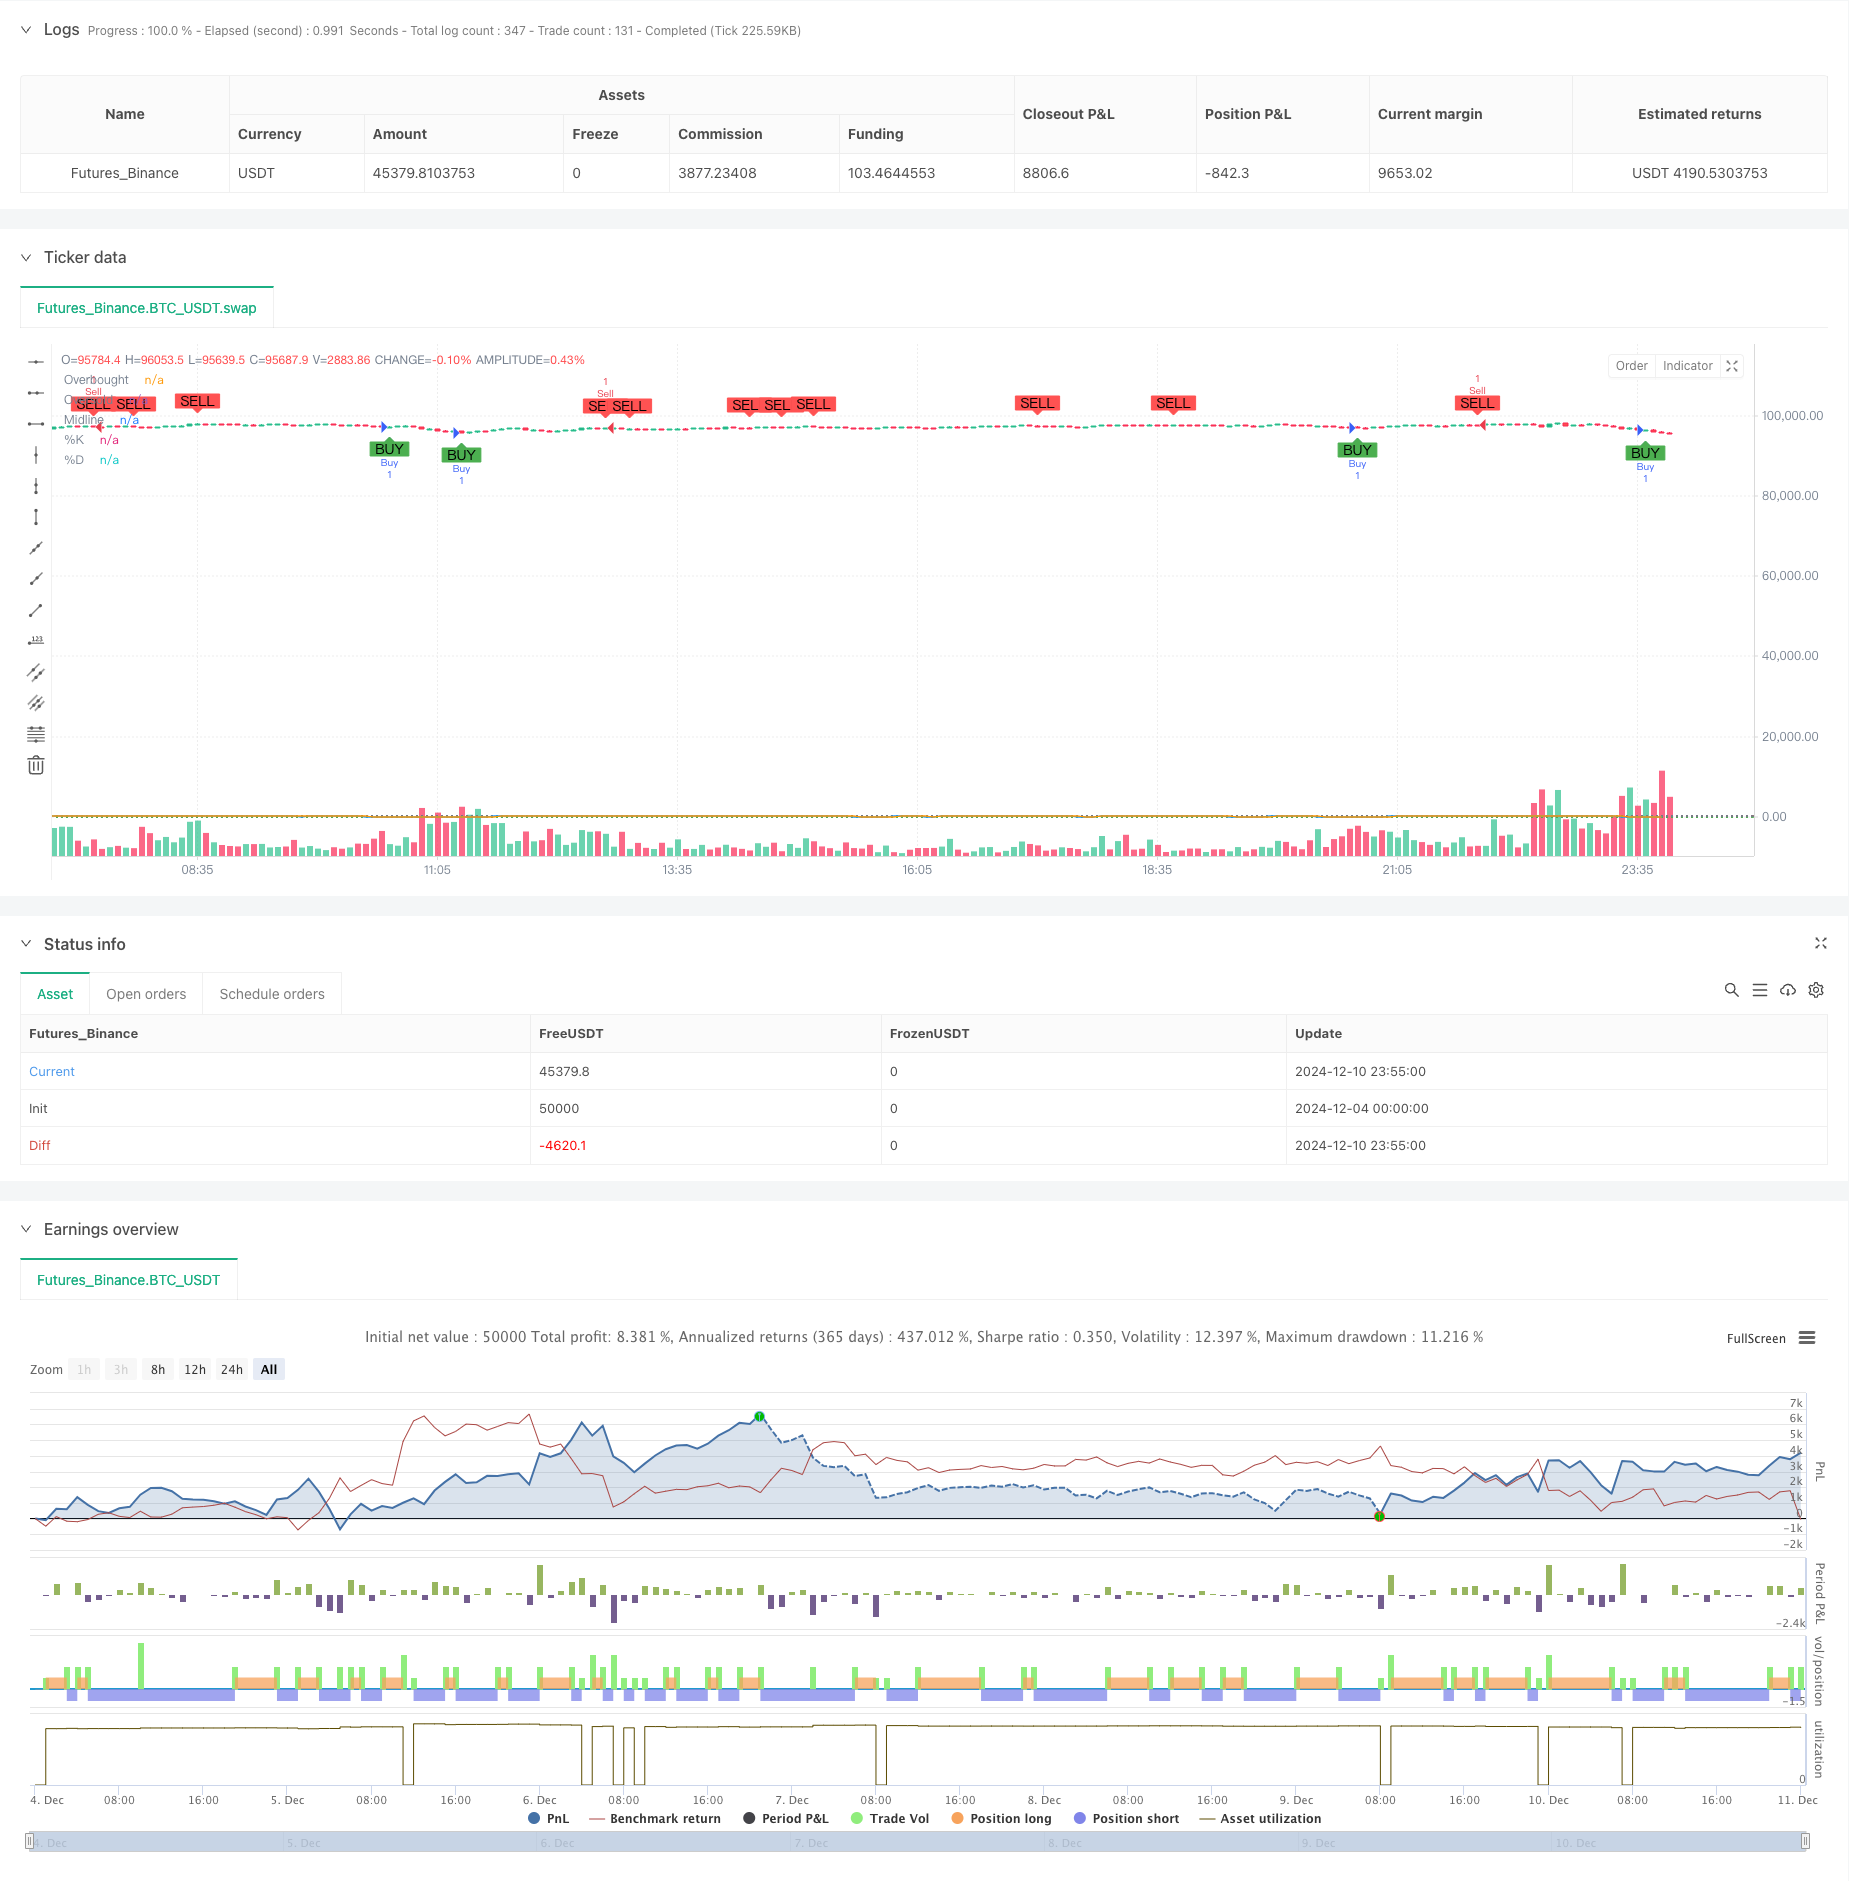
Overview
This strategy is a dual timeframe momentum trading system based on the Stochastic indicator. It identifies potential trading opportunities by analyzing Stochastic crossover signals across different timeframes, combining momentum principles and trend-following methods for more accurate market trend judgment and trade timing. The strategy also incorporates risk management mechanisms, including take-profit and stop-loss settings, for better money management.
Strategy Principles
The core logic is based on the following key elements:
- Uses Stochastic indicators on two timeframes: longer timeframe for overall trend confirmation, shorter timeframe for specific trade signal generation.
- Trade signal generation rules:
- Long signals: when short-period %K crosses above %D from oversold area (below 20), while longer timeframe shows uptrend.
- Short signals: when short-period %K crosses below %D from overbought area (above 80), while longer timeframe shows downtrend.
- Sets 14 periods as the base period for Stochastic indicator, 3 periods as smoothing factor.
- Integrates candlestick pattern confirmation mechanism to enhance signal reliability.
Strategy Advantages
- Multiple confirmation mechanism: provides more reliable signals through dual timeframe analysis.
- Trend following capability: effectively captures market trend turning points.
- High flexibility: parameters can be adjusted for different market conditions.
- Comprehensive risk control: integrated take-profit and stop-loss mechanisms.
- Clear signals: trading signals are explicit and easy to execute.
- Strong adaptability: applicable to multiple timeframe combinations.
Strategy Risks
- False breakout risk: may generate false signals in ranging markets.
- Lag risk: signals may have some delay due to moving average smoothing factors.
- Parameter sensitivity: different parameter settings significantly affect strategy performance.
- Market environment dependency: performs better in trending markets but may underperform in ranging markets.
Strategy Optimization Directions
- Introduce volatility indicators: add ATR indicator for dynamic stop-loss adjustment.
- Optimize signal filtering: add volume confirmation mechanism.
- Add trend strength filtering: incorporate trend strength indicators like ADX.
- Improve risk management: implement dynamic position sizing mechanism.
- Optimize parameter adaptation: dynamically adjust parameters based on market conditions.
Summary
This is a well-structured trading strategy with clear logic, capturing market opportunities through dual timeframe Stochastic indicator analysis. The strategy's strengths lie in its multiple confirmation mechanisms and comprehensive risk control, but attention must be paid to risks such as false breakouts and parameter sensitivity. Through continuous optimization and improvement, the strategy has the potential to achieve better trading results.
Source Pine Script
/*backtest
start: 2024-12-04 00:00:00
end: 2024-12-11 00:00:00
period: 5m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Enhanced Stochastic Strategy", overlay=true)

// Input untuk Stochastic
length = input.int(14, title="Length", minval=1)
OverBought = input(80, title="Overbought Level")
OverSold = input(20, title="Oversold Level")
smoothK = input.int(3, title="Smooth %K")
smoothD = input.int(3, title="Smooth %D")

// Input untuk Manajemen Risiko
tpPerc = input.float(2.0, title="Take Profit (%)", step=0.1)
slPerc = input.float(1.0, title="Stop Loss (%)", step=0.1)

// Hitung Stochastic
k = ta.sma(ta.stoch(close, high, low, length), smoothK)
d = ta.sma(k, smoothD)

// Logika Sinyal
co = ta.crossover(k, d)  // %K memotong %D ke atas
cu = ta.crossunder(k, d) // %K memotong %D ke bawah

longCondition = co and k < OverSold
shortCondition = cu and k > OverBought

// Harga untuk TP dan SL
var float longTP = na
var float longSL = na
var float shortTP = na
var float shortSL = na

if (longCondition)
    longTP := close * (1 + tpPerc / 100)
    longSL := close * (1 - slPerc / 100)
    strategy.entry("Buy", strategy.long, comment="StochLE")
    strategy.exit("Sell Exit", "Buy", limit=longTP, stop=longSL)

if (shortCondition)
    shortTP := close * (1 - tpPerc / 100)
    shortSL := close * (1 + slPerc / 100)
    strategy.entry("Sell", strategy.short, comment="StochSE")
    strategy.exit("Buy Exit", "Sell", limit=shortTP, stop=shortSL)

// Plot Stochastic dan Level
hline(OverBought, "Overbought", color=color.red, linestyle=hline.style_dotted)
hline(OverSold, "Oversold", color=color.green, linestyle=hline.style_dotted)
hline(50, "Midline", color=color.gray, linestyle=hline.style_dotted)

plot(k, color=color.blue, title="%K")
plot(d, color=color.orange, title="%D")

// Tambahkan sinyal visual
plotshape(longCondition, title="Buy Signal", location=location.belowbar, style=shape.labelup, color=color.new(color.green, 0), text="BUY")
plotshape(shortCondition, title="Sell Signal", location=location.abovebar, style=shape.labeldown, color=color.new(color.red, 0), text="SELL")Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Timeframe-Stochastic-Momentum-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi EMA Trend Momentum Trading Strategy with Risk Management SystemPine Script · Momentum · 1h
- Advanced EMA Crossover Momentum Trend Capture StrategyPine Script · Momentum · 2h
- Multi MA Trend Strength Capture with Momentum Profit Taking StrategyPine Script · Momentum · 2h
- Momentum Trading Strategy Based on Multi factor ModelPine Script · Momentum · 1d
- Triple Moving Average Momentum Trend Trading StrategyPine Script · Momentum · 2d
- Momentum Direction Divergence StrategyPine Script · Momentum · 1d