Dual track System Momentum Trading Strategy
This strategy combines the MACD and Stoch RSI indicators to build a dual-rail trading system for trend tracking and oversold/overbought judgment. The strategy also builds indicators on the daily and 4-hour timeframes…
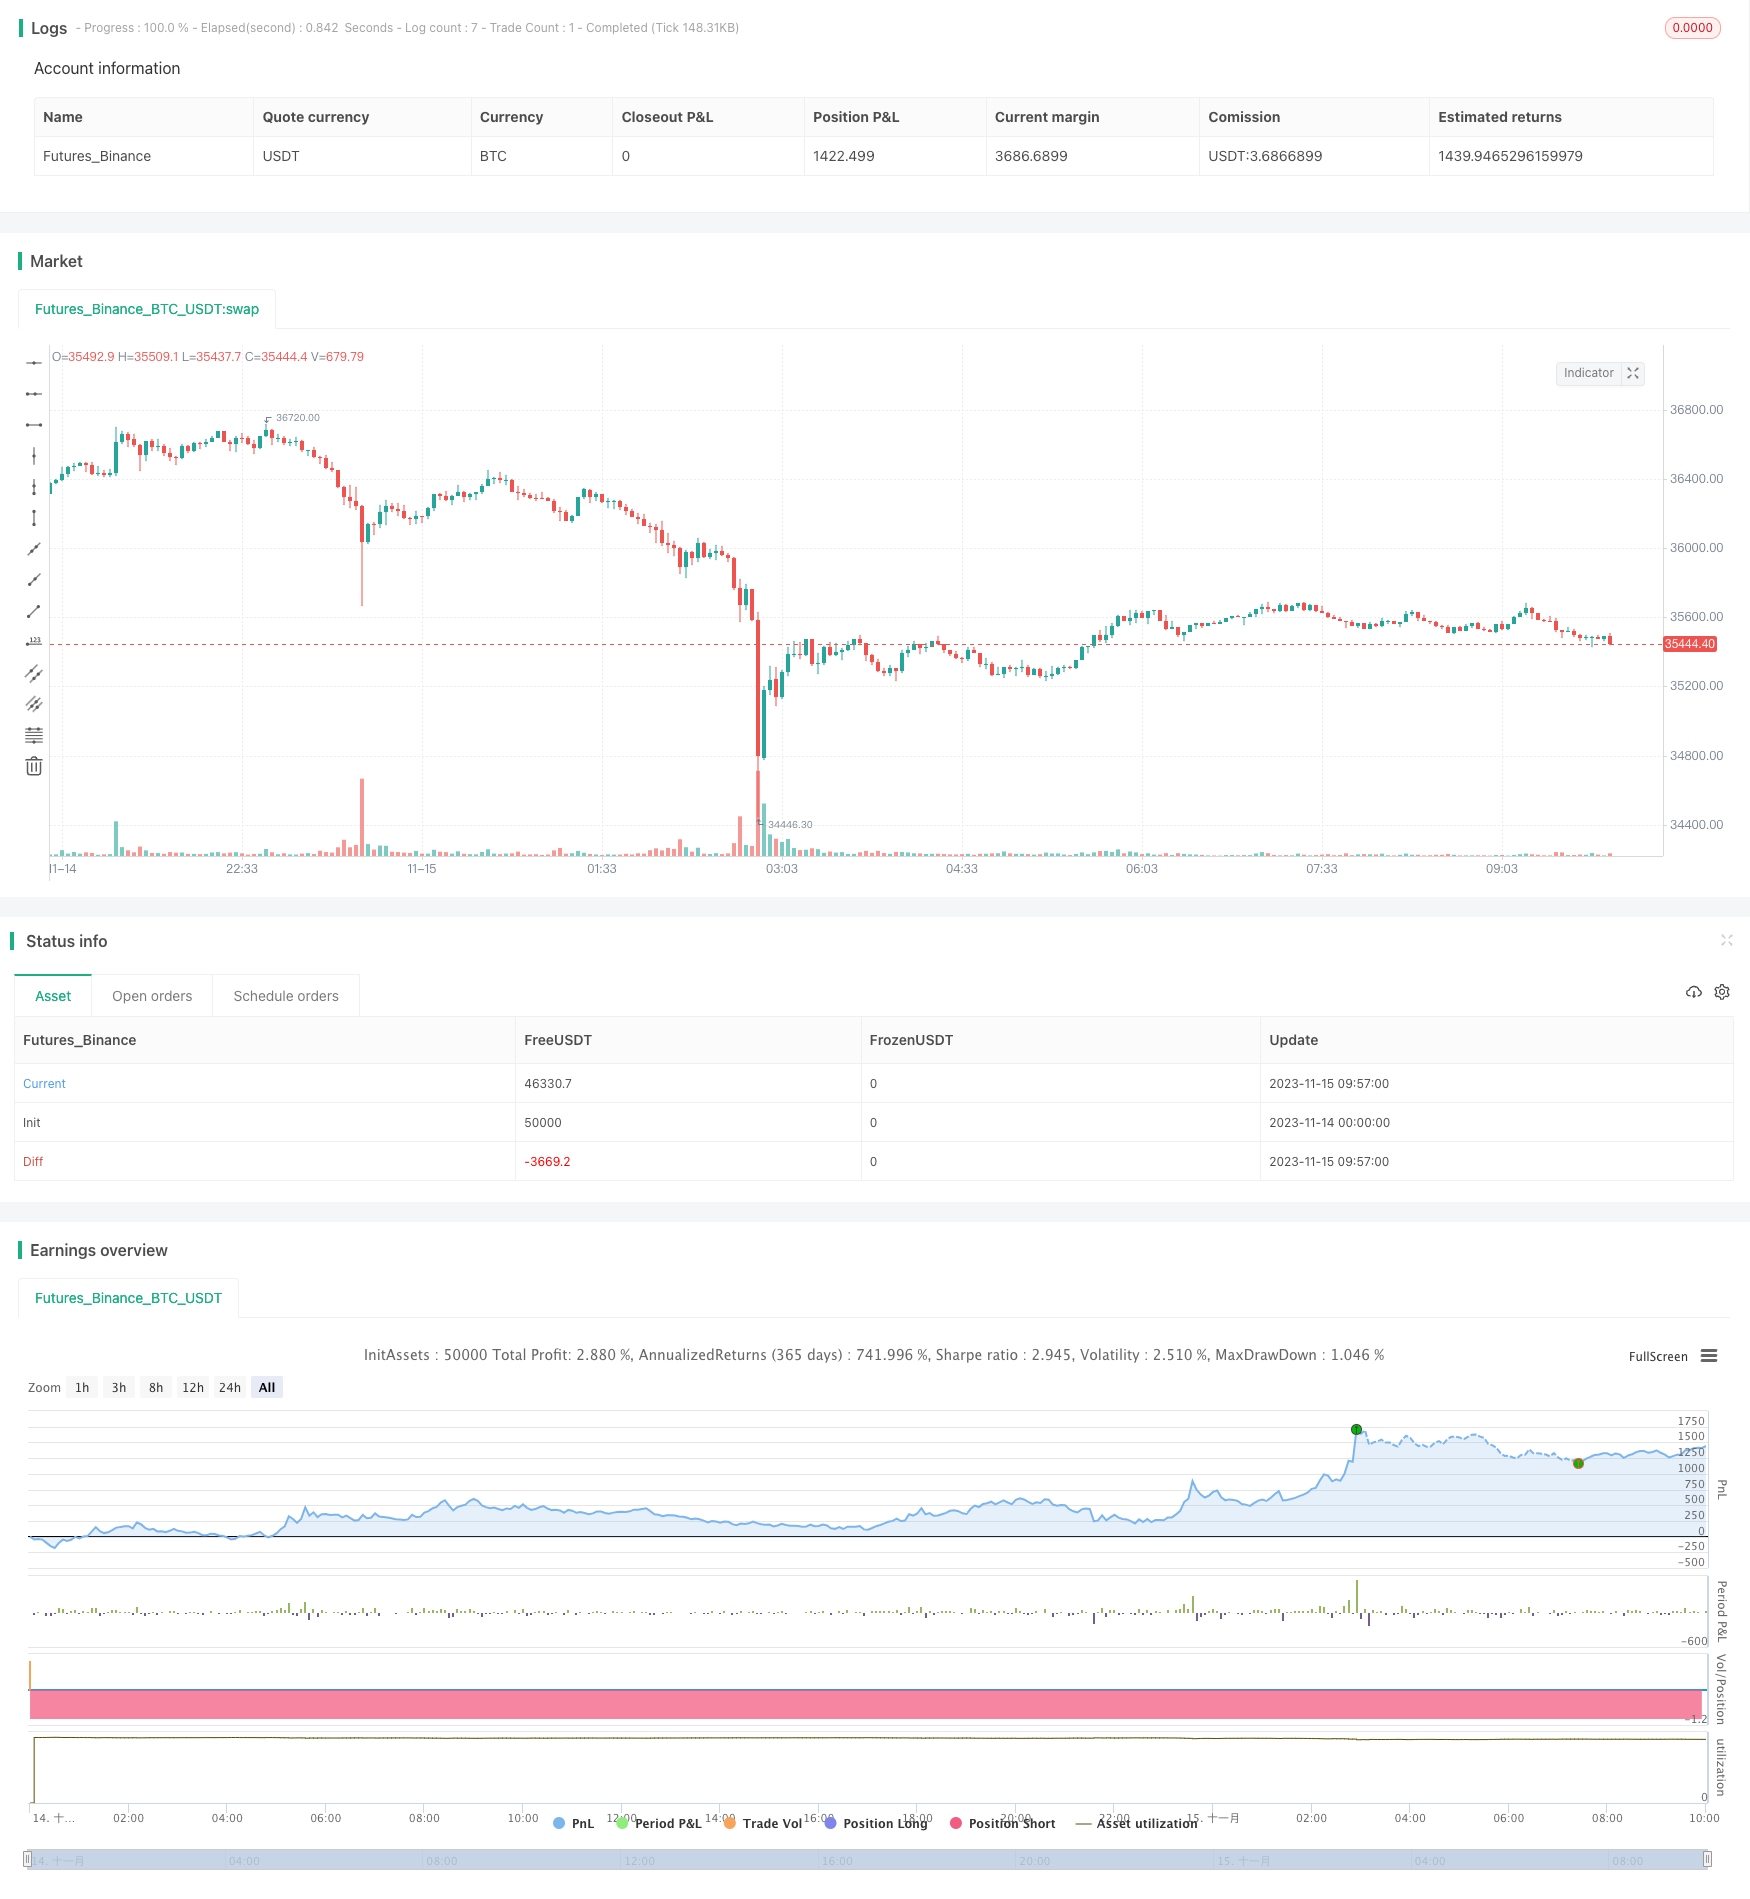
Overview
This strategy combines the MACD and Stoch RSI indicators to build a dual-rail trading system for trend tracking and oversold/overbought judgment. The strategy also builds indicators on the daily and 4-hour timeframes to make multi-timeframe judgments to reduce misjudgment probability.
Strategy Principle
The strategy combines the MACD and Stoch RSI indicators, which are different types of technical indicators, for configuration. MACD is a momentum indicator that judges price change velocity; Stoch RSI is an overbought/oversold indicator that judges relative price strength.
The strategy first constructs the MACD and Stoch RSI indicators on the daily and 4-hour timeframes respectively for trend and overbought/oversold judgments. When signals are triggered on both timeframes, corresponding buy/sell operations are performed.
Specifically, the MACD indicator is constructed with the DIF and DEA lines forming golden/dead crosses for judgment; the Stoch RSI indicator is constructed with the K and D lines forming golden/dead crosses for judgment. When both indicator pairs have golden crosses, buy signals are generated; when both have dead crosses, sell signals are generated.
Thus, by comprehensively applying the dual-indicator system and multi-timeframe judgments, the strategy judges price velocity and relative strength thoroughly, which helps improve decision accuracy and gain better returns.
Advantage Analysis
This strategy has the following advantages:
- Combining dual-indicator system for comprehensive judgment and higher decision accuracy
- Applying multi-timeframe to reduce misjudgment probability
- Adopting trend tracking and overbought/oversold judgment for consideration of both price velocity and relative strength
- Flexible indicator parameters adjustable for different products and market environments
- Clean code structure easy to understand and expand
Risk Analysis
There are also some risks with this strategy:
- There exist systemic market risks that cannot be fully avoided
- Inappropriate indicator parameter settings may lead to overtrading or missing opportunities
- Dual indicators may still give concurrent wrong signals, but less likely than single ones
- Unable to cope with drastic market changes like black swan events
Countermeasures:
- Optimize parameters and adjust trading conditions to reduce misjudgments
- Incorporate more indicators for combined judgments
- Add stop loss mechanisms to control single loss risk
Optimization Directions
This strategy can also be improved in the following aspects:
- Incorporate more indicators for multi-indicator strategies
- Add machine learning algorithms for dynamic parameter optimization
- Combine sentiment indicators, news etc. for more comprehensive market condition judgments
- Add stop loss, take profit strategies to optimize money management
- Expand to more trading products to discover better opportunities
Conclusion
By combined application of the dual-indicator system and multi-timeframe judgments, this strategy judges price velocity and relative strength thoroughly, which can effectively capture market trends and improve deficiencies of single indicators. It also has advantages like flexible parameter tuning, easy understanding and expansion. Further expansions by multi-indicator combination, dynamic parameter optimization, sentiment indicator incorporation etc. can help boost strategy performance. [trans]
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | MACD Source:: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 12 | MACD Fast Length: |
| v_input_3 | 26 | MACD Slow Length: |
| v_input_4 | 9 | MACD Signal Smoothing: |
| v_input_5_close | 0 | SRSI Source:: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_6 | 14 | SRSI RSI Length: |
| v_input_7 | 14 | SRSI Stoch Length: |
| v_input_8 | 3 | SRSI Smoothing: |
| v_input_9 | 3 | SRSI Signal Smoothing: |
| v_input_10 | true | Trade Size in USD: |
| v_input_11 | true | Perform buy trading? |
| v_input_12 | true | Perform sell trading? |
Source Pine Script
/*backtest
start: 2023-11-14 00:00:00
end: 2023-11-15 10:00:00
period: 3m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy(title='[RS]Khizon (UWTI) Strategy V0', shorttitle='K', overlay=false, pyramiding=0, initial_capital=100000, currency=currency.USD)
//  ||  Inputs:
macd_src = input(title='MACD Source:',  defval=close)
macd_fast = input(title='MACD Fast Length:',  defval=12)
macd_slow = input(title='MACD Slow Length:',  defval=26)
macd_signal_smooth = input(title='MACD Signal Smoothing:',  defval=9)
srsi_src = input(title='SRSI Source:',  defval=close)
srsi_rsi_length = input(title='SRSI RSI Length:',  defval=14)
srsi_stoch_length = input(title='SRSI Stoch Length:',  defval=14)
srsi_smooth = input(title='SRSI Smoothing:',  defval=3)
srsi_signal_smooth = input(title='SRSI Signal Smoothing:',  defval=3)
//  ||  Strategy Inputs:
trade_size = input(title='Trade Size in USD:', type=float, defval=1)
buy_trade = input(title='Perform buy trading?', type=bool, defval=true)
sel_trade = input(title='Perform sell trading?', type=bool, defval=true)
//  ||  MACD(close, 12, 26, 9):     ||---------------------------------------------||
f_macd_trigger(_src, _fast, _slow, _signal_smooth)=>
    _macd = ema(_src, _fast) - ema(_src, _slow)
    _signal = sma(_macd, _signal_smooth)
    _return_trigger = _macd >= _signal ? true : false
//  ||  Stoch RSI(close, 14, 14, 3, 3)  ||-----------------------------------------||
f_srsi_trigger(_src, _rsi_length, _stoch_length, _smooth, _signal_smooth)=>
    _rsi = rsi(_src, _rsi_length)
    _stoch = sma(stoch(_rsi, _rsi, _rsi, _stoch_length), _smooth)
    _signal = sma(_stoch, _signal_smooth)
    _return_trigger = _stoch >= _signal ? true : false
//  ||-----------------------------------------------------------------------------||
//  ||-----------------------------------------------------------------------------||
//  ||  Check Directional Bias from daily timeframe:
daily_trigger = security('USOIL', 'D', f_macd_trigger(macd_src, macd_fast, macd_slow, macd_signal_smooth) and f_srsi_trigger(srsi_src, srsi_rsi_length, srsi_stoch_length, srsi_smooth, srsi_signal_smooth))
h4_trigger = security('USOIL', '240', f_macd_trigger(macd_src, macd_fast, macd_slow, macd_signal_smooth) and f_srsi_trigger(srsi_src, srsi_rsi_length, srsi_stoch_length, srsi_smooth, srsi_signal_smooth))

plot(title='D1T', series=daily_trigger?0:na, style=circles, color=blue, linewidth=4, transp=65)
plot(title='H4T', series=h4_trigger?0:na, style=circles, color=navy, linewidth=2, transp=0)

sel_open = sel_trade and not daily_trigger and not h4_trigger
buy_open = buy_trade and daily_trigger and h4_trigger
sel_close = not buy_trade and daily_trigger and h4_trigger
buy_close = not sel_trade and not daily_trigger and not h4_trigger
strategy.entry('sel', long=false, qty=trade_size, comment='sel', when=sel_open)
strategy.close('sel', when=sel_close)
strategy.entry('buy', long=true, qty=trade_size, comment='buy', when=buy_open)
strategy.close('buy', when=buy_close)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-track-System-Momentum-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- MoonFlag MACD Momentum StochRSI Trading StrategyPine Script · Momentum · 1d
- Multi factor Adaptive Momentum Tracking StrategyPine Script · Momentum · 3m
- Dual Momentum Oscillator Smart Timing Trading StrategyPine Script · Momentum · 1h
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m
- Oscillator Candles Momentum Trading StrategyPine Script · Momentum · 1h
- Multi factor Fusion Strategy Multi factor Fusion StrategyPine Script · Momentum · 3h