Strategy vault / Trend following
Dynamic Adaptive Multi Indicator Crossing Strategy with SRSI MACD Smart Risk Control System
This strategy is a dynamic trading system that combines the Stochastic Relative Strength Index (SRSI) and Moving Average Convergence/Divergence (MACD). It implements intelligent risk management through dynamic…
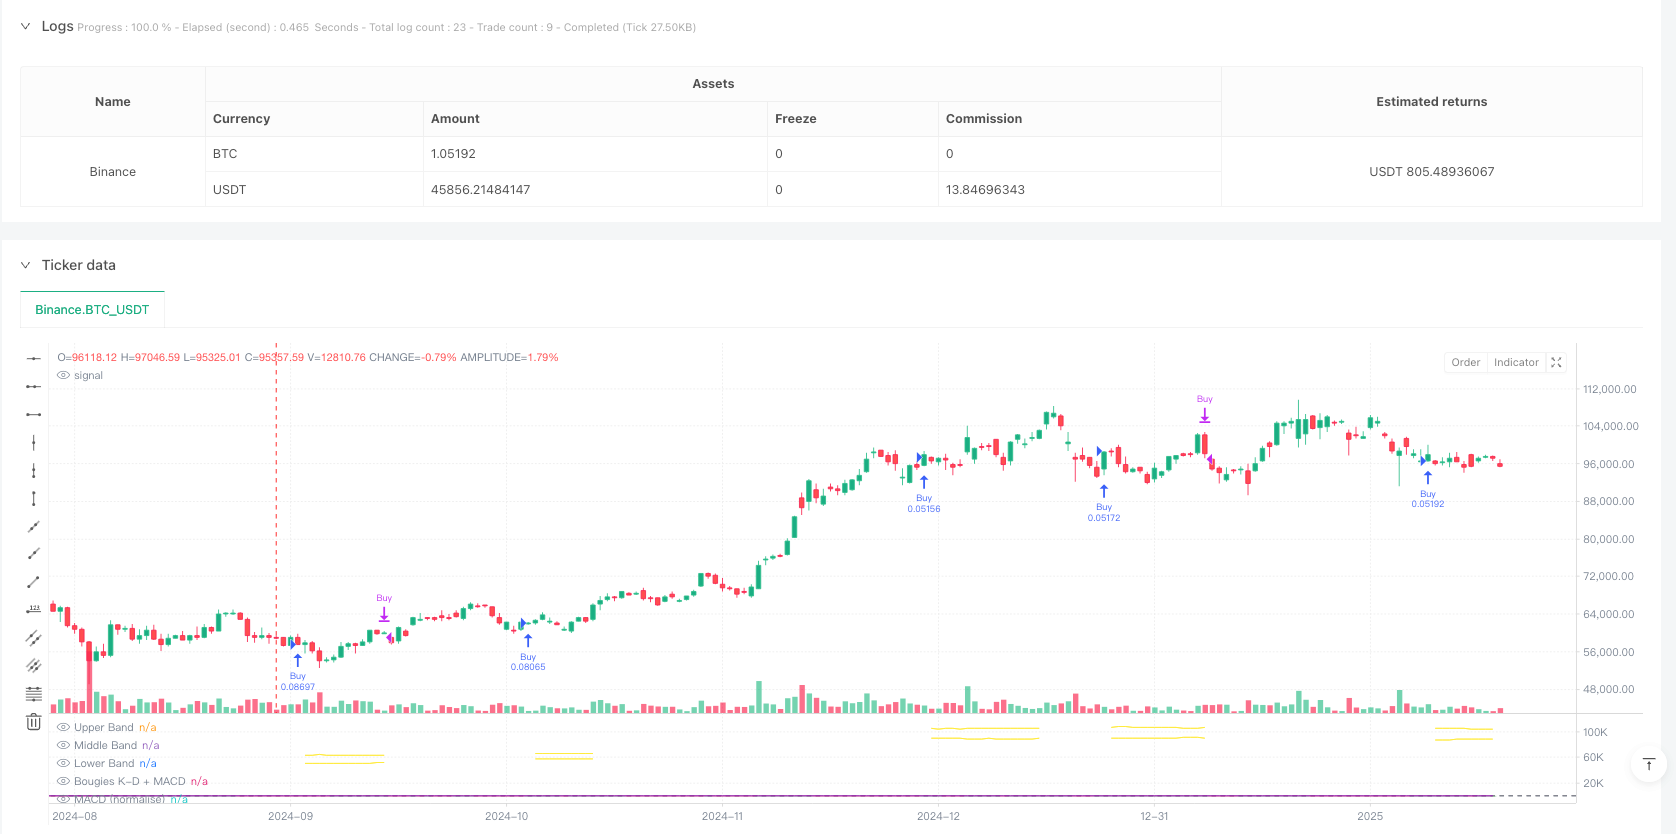
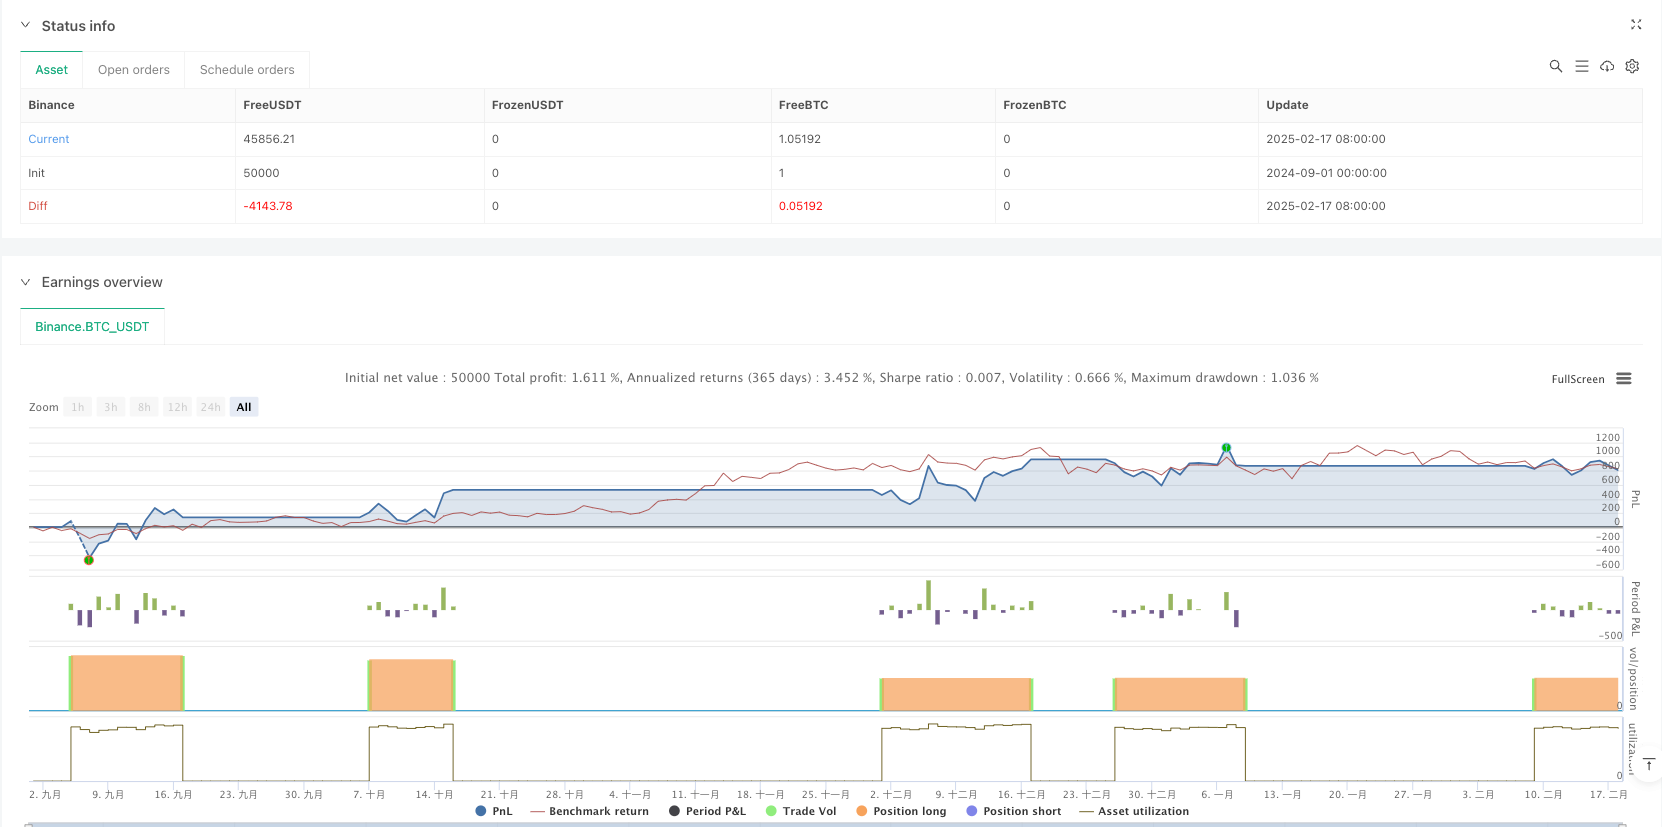
Overview
This strategy is a dynamic trading system that combines the Stochastic Relative Strength Index (SRSI) and Moving Average Convergence/Divergence (MACD). It implements intelligent risk management through dynamic stop-loss and take-profit levels adjusted by the Average True Range (ATR) indicator. The core of the strategy lies in generating trading signals through multiple technical indicator crossovers while managing positions based on market volatility.
Strategy Principles
The strategy operates based on the following core mechanisms:
- Market trends are determined by calculating the difference between K-line and D-line of SRSI, as well as the difference between K-line and normalized MACD
- Buy conditions require: positive K-D difference, positive K-MACD difference, and MACD not in downtrend
- Sell conditions require: negative K-D difference, negative K-MACD difference, and MACD not in uptrend
- Dynamic calculation of stop-loss and take-profit distances using ATR multiplied by a risk factor, adapting to market volatility
Strategy Advantages
- Multiple signal confirmation mechanism significantly improves trading reliability, avoiding false signals from single indicators
- Dynamic stop-loss and take-profit settings automatically adjust to market volatility, providing better risk-reward ratios
- The strategy demonstrates good adaptability, maintaining stable performance across different market conditions
- Strong parameter adjustability allows traders to optimize according to personal risk preferences
Strategy Risks
- May generate excessive trading signals in ranging markets, leading to frequent market entries and exits
- Multiple indicators might result in delayed signals, missing optimal entry points in rapidly changing markets
- ATR calculations based on historical volatility may not adapt quickly to sudden market volatility changes
- Requires appropriate risk factor settings, as both too high or too low values can affect strategy performance
Strategy Optimization Directions
- Add trend filters to apply different signal confirmation standards in ranging and trending markets
- Incorporate volume indicators as auxiliary confirmation to improve signal reliability
- Optimize stop-loss and take-profit calculations, potentially incorporating support and resistance levels
- Introduce market volatility prediction models for preemptive risk parameter adjustments
- Consider signal confirmation across different timeframes to enhance strategy robustness
Summary
This strategy builds a robust trading system by combining the advantages of SRSI and MACD. Its dynamic risk management mechanism provides good adaptability, though traders still need to optimize parameters based on actual market conditions. Successful strategy implementation requires deep market understanding and appropriate position management aligned with individual risk tolerance.
Source Pine Script
/*backtest
start: 2024-09-01 00:00:00
end: 2025-02-18 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy(title="SRSI + MACD Strategy with Dynamic Stop-Loss and Take-Profit", shorttitle="SRSI + MACD Strategy", overlay=false, default_qty_type=strategy.percent_of_equity, default_qty_value=10)

// User Inputs
smoothK = input.int(3, "K", minval=1)
smoothD = input.int(3, "D", minval=1)
lengthRSI = input.int(16, "RSI Length", minval=1)
lengthStoch = input.int(16, "Stochastic Length", minval=1)
src = input(close, title="RSI Source")
enableStopLoss = input.bool(true, "Enable Stop-Loss")
enableTakeProfit = input.bool(true, "Enable Take-Profit")
riskFactor = input.float(2.5, "Risk Factor", minval=0.1, step=1)

// Calculate K and D lines
rsi1 = ta.rsi(src, lengthRSI)
k = ta.sma(ta.stoch(rsi1, rsi1, rsi1, lengthStoch), smoothK)
d = ta.sma(k, smoothD)
differenceKD = k - d

// Calculate MACD and normalization
[macdLine, signalLine, _] = ta.macd(close, 12, 26, 9)
lowestK = ta.lowest(k, lengthRSI)
highestK = ta.highest(k, lengthRSI)
normalizedMacd = (macdLine - ta.lowest(macdLine, lengthRSI)) / (ta.highest(macdLine, lengthRSI) - ta.lowest(macdLine, lengthRSI)) * (highestK - lowestK) + lowestK
differenceKMacd = k - normalizedMacd

// Sum both differences for a unique display
differenceTotal = (differenceKD + differenceKMacd) / 2

// Check if MACD is falling or rising
isMacdFalling = ta.falling(macdLine, 1)
isMacdRising = ta.rising(macdLine, 1)

// Check if K is falling or rising
isKFalling = ta.falling(k, 1)
isKdRising = ta.rising(k, 1)

// Calculate ATR and dynamic levels
atrValue = ta.atr(14)
stopLossDistance = atrValue * riskFactor
takeProfitDistance = atrValue * riskFactor

// Variables for stop-loss and take-profit levels
var float longStopPrice = na
var float longTakeProfitPrice = na

// Buy and sell conditions with differenceKD added
buyCondition = ((differenceTotal > 0 or differenceKD > 0) and (isKdRising or isMacdRising) and k < 20 )
sellCondition = ((differenceTotal <= 0 or differenceKD <= 0) and (isKFalling or isMacdFalling) and k > 80)

// Execute strategy orders with conditional stop-loss and take-profit
if buyCondition and strategy.position_size == 0
    strategy.entry("Buy", strategy.long)

if strategy.position_size > 0
    longStopPrice := strategy.position_avg_price - stopLossDistance
    longTakeProfitPrice := strategy.position_avg_price + takeProfitDistance

    if enableStopLoss or enableTakeProfit
        strategy.exit("Sell/Exit", "Buy", stop=(enableStopLoss ? longStopPrice : na), limit=(enableTakeProfit ? longTakeProfitPrice : na))

if sellCondition
    strategy.close("Buy")

// Hide lines when position is closed
stopLossToPlot = strategy.position_size > 0 ? longStopPrice : na
takeProfitToPlot = strategy.position_size > 0 ? longTakeProfitPrice : na

// Plot stop-loss and take-profit lines only when long positions are active
plot(enableStopLoss ? stopLossToPlot : na, title="Stop-Loss", color=color.yellow, linewidth=1, style=plot.style_linebr, offset=0, force_overlay=true)
plot(enableTakeProfit ? takeProfitToPlot : na, title="Take-Profit", color=color.yellow, linewidth=1, style=plot.style_linebr, offset=0, force_overlay=true)

// Plot the MACD and candles

plot(normalizedMacd, "Normalized MACD", color=color.new(color.purple, 0), linewidth=1, display=display.all)

h0 = hline(80, "Upper Band", color=#787B86)
hline(50, "Middle Band", color=color.new(#787B86, 50))
h1 = hline(20, "Lower Band", color=#787B86)
fill(h0, h1, color=color.rgb(33, 150, 243, 90), title="Background")

// New candle based on the sum of differences
plotcandle(open=0, high=differenceTotal, low=0, close=differenceTotal, color=(differenceTotal > 0 ? color.new(color.green, 60) : color.new(color.red, 60)), title="K-D + MACD Candles")
Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Adaptive-Multi-Indicator-Crossing-Strategy-with-SRSI-MACD-Smart-Risk-Control-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Dimensional Short Term Trend Predictor Technical Analysis and Volatility Adaptive Trading StrategyPine Script · Trend following · 1h
- Going with the Trend Moving Average Crossover StrategyPine Script · Trend following · 1d
- Mini Pullback Supertrend StrategyPine Script · Trend following · 1h
- Three Exponential Moving Averages and Stochastic Relative Strength Index Trading StrategyPine Script · Trend following · 1h
- Enhanced Moving Average Crossover Sakkoulas Trading StrategyPine Script · Trend following · 1h