Dynamic ATR Trend Following Strategy Based on Support Breakout
This is a dynamic ATR trend following strategy based on support breakout. The strategy incorporates EMA system, ATR volatility indicator, and Smart Money Concept (SMC) to capture market trends. It achieves effective…
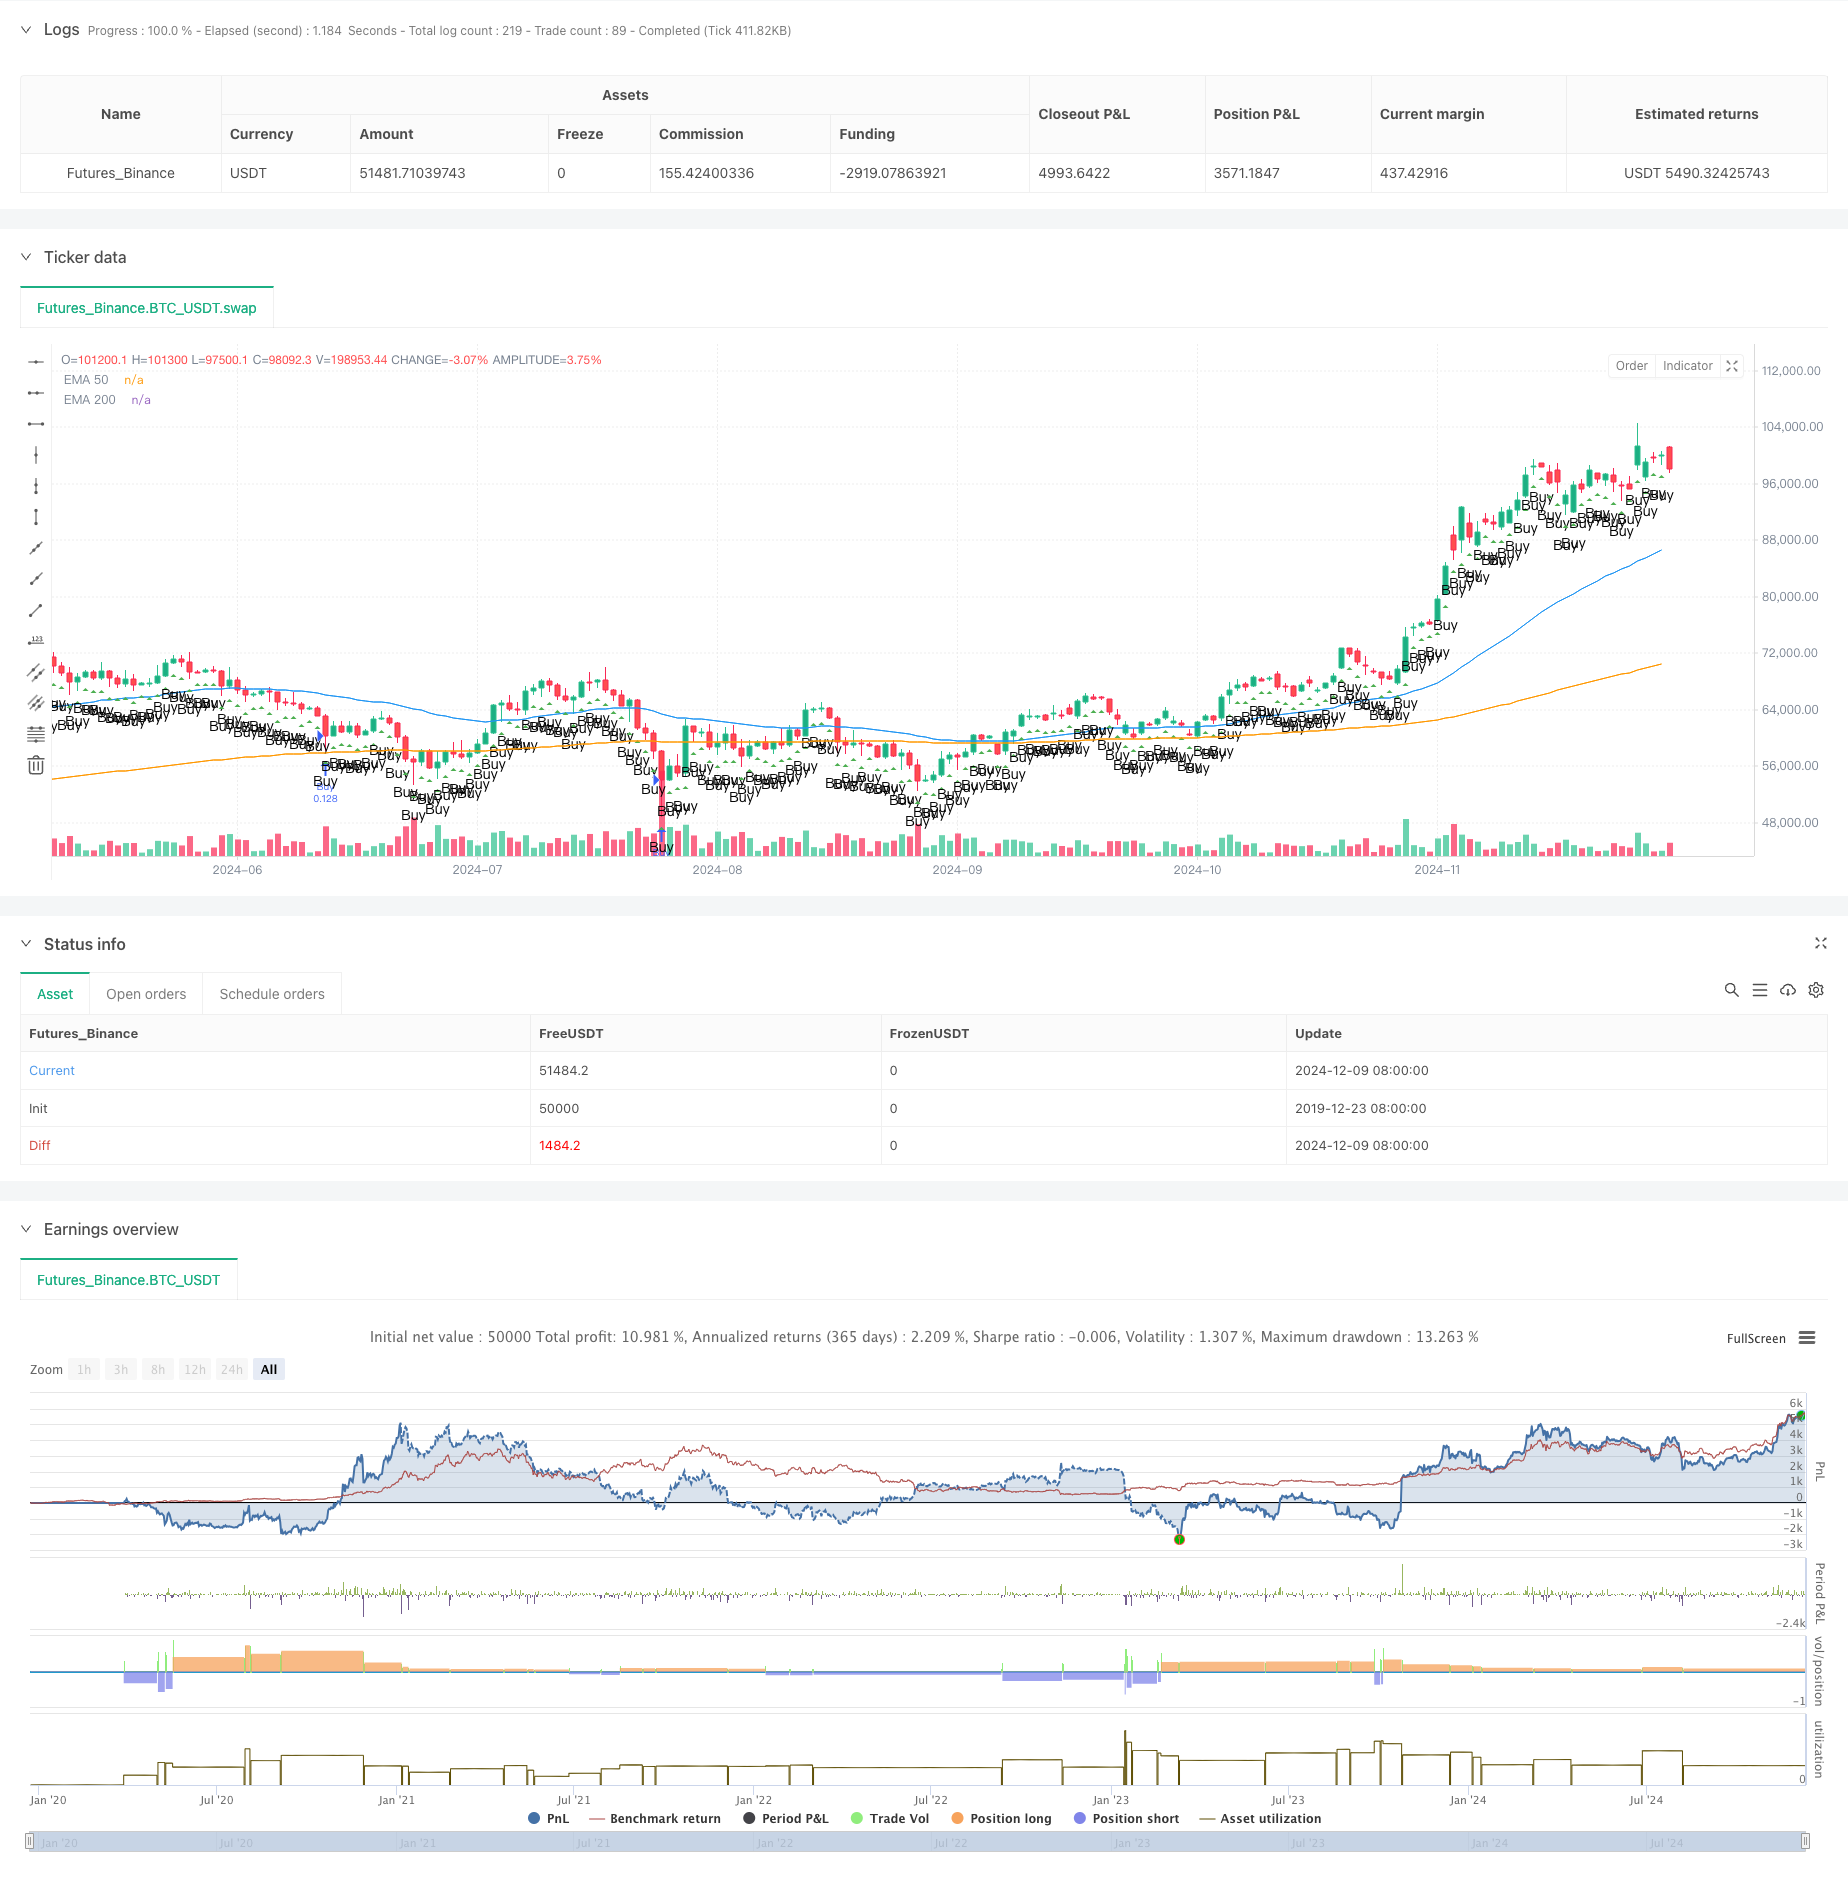
Overview
This is a dynamic ATR trend following strategy based on support breakout. The strategy incorporates EMA system, ATR volatility indicator, and Smart Money Concept (SMC) to capture market trends. It achieves effective risk management through dynamic position sizing and stop-loss/take-profit placement.
Strategy Principle
The strategy is built on several core components:
- Uses 50 and 200-period EMA system to confirm market trend direction
- Utilizes ATR indicator to dynamically adjust stop-loss and profit targets
- Analyzes Order Blocks and Imbalance Zones to find optimal entry points
- Automatically calculates position size based on account risk percentage
- Determines market consolidation by observing price range of last 20 candles
Strategy Advantages
- Comprehensive risk management through dynamic calculation
- Reliable trend identification system that avoids consolidation markets
- Reasonable stop-loss and take-profit settings with 1:3 risk-reward ratio
- Adapts well to different market conditions
- Clear code structure that's easy to maintain and optimize
Strategy Risks
- EMA indicators have inherent lag, potentially delaying entry points
- May generate false signals in highly volatile markets
- Strategy depends on trend continuation, may underperform in ranging markets
- Wide stop-loss placement may lead to larger losses in certain situations
Optimization Directions
- Incorporate volume-price relationship analysis to improve trend identification
- Add market sentiment indicators to optimize entry timing
- Consider multiple timeframe analysis to enhance system stability
- Refine Order Block and Imbalance Zone identification criteria
- Optimize stop-loss method, consider implementing trailing stops
Summary
This strategy is a comprehensive trend following system that achieves trading stability through proper risk management and multiple signal confirmation. Despite some lag in signals, it represents a reliable trading system overall. It's recommended to conduct thorough backtesting before live implementation and optimize parameters according to specific trading instruments and market conditions.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-12-10 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// TradingView Pine Script strategy for Smart Money Concept (SMC)
//@version=5
strategy("Smart Money Concept Strategy", overlay=true, default_qty_type=strategy.fixed, default_qty_value=100)

// === Input Parameters ===
input_risk_percentage = input.float(1, title="Risk Percentage", step=0.1)
input_atr_length = input.int(14, title="ATR Length")
input_ema_short = input.int(50, title="EMA Short")
input_ema_long = input.int(200, title="EMA Long")

// === Calculations ===
atr = ta.atr(input_atr_length)
ema_short = ta.ema(close, input_ema_short)
ema_long = ta.ema(close, input_ema_long)

// === Utility Functions ===
// Identify Order Blocks
is_order_block(price, direction) =>
    ((high[1] > high[2] and low[1] > low[2] and direction == 1) or (high[1] < high[2] and low[1] < low[2] and direction == -1))

// Identify Imbalance Zones
is_imbalance() =>
    range_high = high[1]
    range_low = low[1]
    range_high > close and range_low < close

// Calculate Lot Size Based on Risk
calculate_lot_size(stop_loss_points, account_balance) =>
    risk_amount = account_balance * (input_risk_percentage / 100)
    lot_size = risk_amount / (stop_loss_points * syminfo.pointvalue)
    lot_size

// Determine if Market is Consolidating
is_consolidating() =>
    (ta.highest(high, 20) - ta.lowest(low, 20)) / atr < 2

// === Visual Enhancements ===
// Plot Order Blocks
// if is_order_block(close, 1)
//     line.new(x1=bar_index[1], y1=low[1], x2=bar_index, y2=low[1], color=color.green, width=2, extend=extend.right)
// if is_order_block(close, -1)
//     line.new(x1=bar_index[1], y1=high[1], x2=bar_index, y2=high[1], color=color.red, width=2, extend=extend.right)

// Highlight Imbalance Zones
// if is_imbalance()
//     box.new(left=bar_index[1], top=high[1], right=bar_index, bottom=low[1], bgcolor=color.new(color.orange, 80))

// === Logic for Trend Confirmation ===
is_bullish_trend = ema_short > ema_long
is_bearish_trend = ema_short < ema_long

// === Entry Logic ===
account_balance = strategy.equity
if not is_consolidating()
    if is_bullish_trend
        stop_loss = close - atr * 2
        take_profit = close + (math.abs(close - (close - atr * 2)) * 3)
        stop_loss_points = math.abs(close - stop_loss) / syminfo.pointvalue
        lot_size = calculate_lot_size(stop_loss_points, account_balance)
        strategy.entry("Buy", strategy.long, qty=lot_size)
        strategy.exit("TP/SL", "Buy", stop=stop_loss, limit=take_profit)

    if is_bearish_trend
        stop_loss = close + atr * 2
        take_profit = close - (math.abs(close - (close + atr * 2)) * 3)
        stop_loss_points = math.abs(close - stop_loss) / syminfo.pointvalue
        lot_size = calculate_lot_size(stop_loss_points, account_balance)
        strategy.entry("Sell", strategy.short, qty=lot_size)
        strategy.exit("TP/SL", "Sell", stop=stop_loss, limit=take_profit)

// === Plotting Indicators ===
plot(ema_short, color=color.blue, title="EMA 50")
plot(ema_long, color=color.orange, title="EMA 200")
plotshape(series=is_bullish_trend and not is_consolidating(), style=shape.triangleup, location=location.belowbar, color=color.green, text="Buy")
plotshape(series=is_bearish_trend and not is_consolidating(), style=shape.triangledown, location=location.abovebar, color=color.red, text="Sell")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-ATR-Trend-Following-Strategy-Based-on-Support-Breakout.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- BB Breakout StrategyPine Script · Breakout · 1d
- Donchian Channel and Larry Williams Large Trade Index StrategyPine Script · Breakout · 1m
- Dual Breakout Volatility Channel StrategyPine Script · Breakout · 1h
- Dual MA Momentum Breakout StrategyPine Script · Breakout · 1h
- Dynamic ATR based Trailing Stop Trading StrategyPine Script · Breakout · 1d
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h