Dynamic Channel Breakout Strategy 431895
This strategy utilizes the dynamic channel indicator to determine market direction based on channel breakouts, aiming to capture trend directionality. It mainly calculates the highest high and lowest low over a…
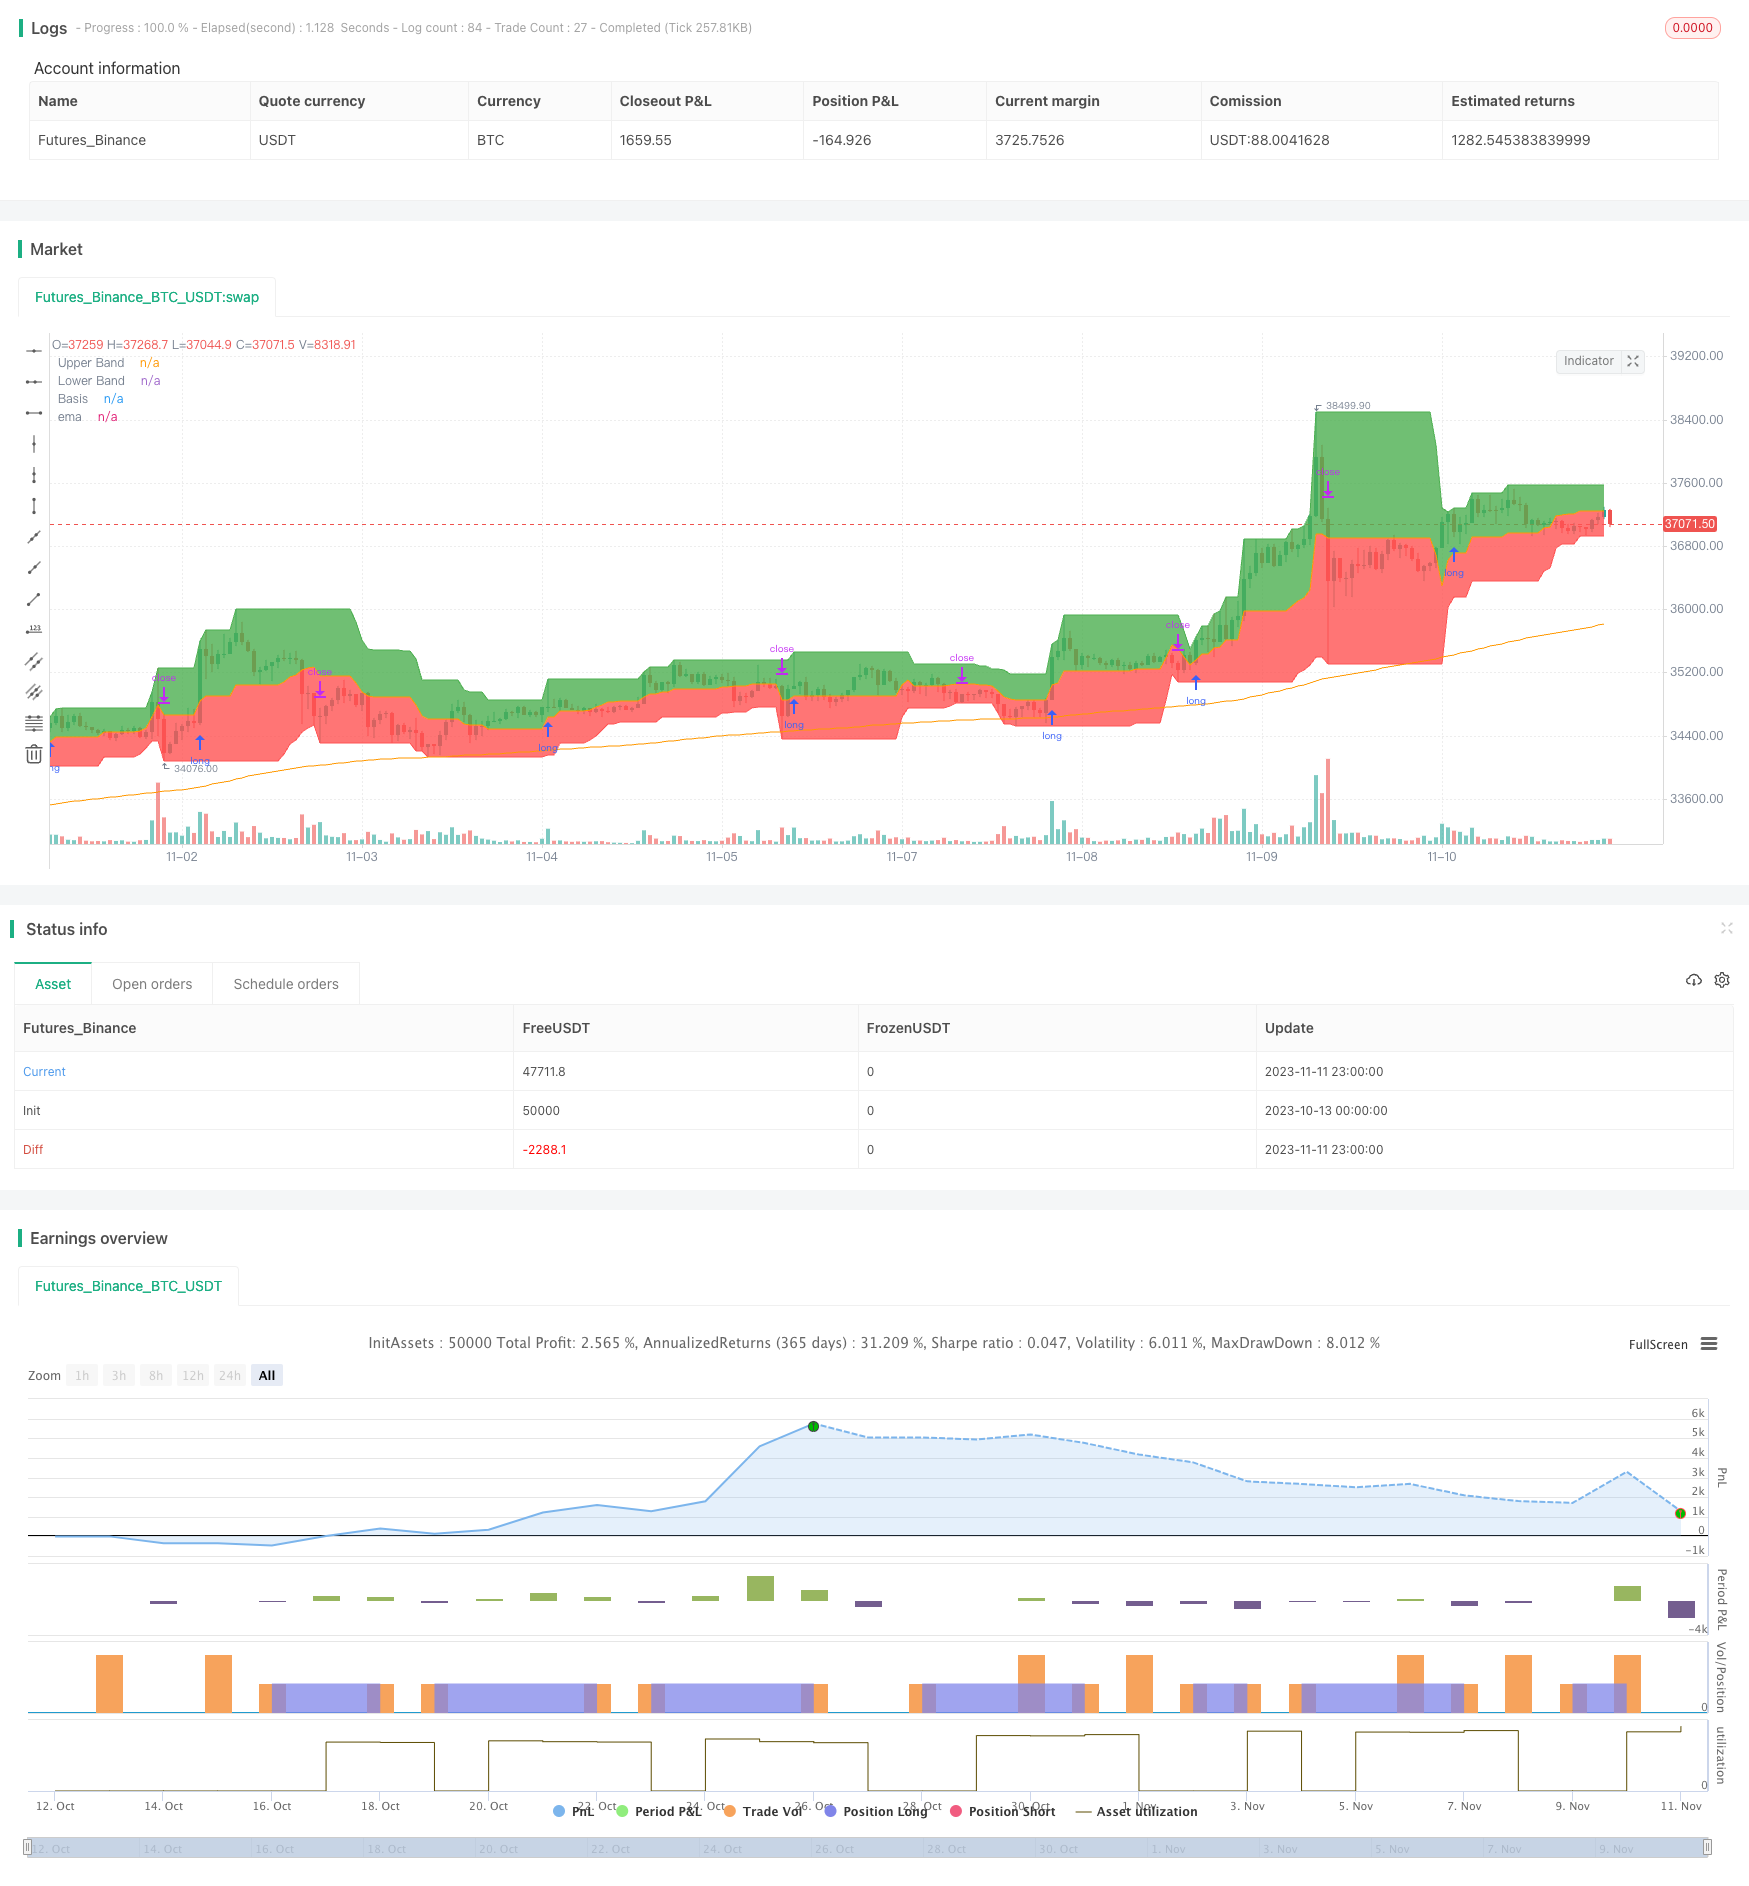
Overview
This strategy utilizes the dynamic channel indicator to determine market direction based on channel breakouts, aiming to capture trend directionality. It mainly calculates the highest high and lowest low over a certain period to form upper and lower channels, generating trading signals when the price breaks through the channels.
Strategy Logic
The strategy uses the input function to set the channel period length to 20 days. It then calculates the highest high over the past 20 days as the upper band, and the lowest low over the past 20 days as the lower band.
The channel is filled with color. The area above the upper band is filled with green, and the area below the lower band is filled with red, forming a dynamic channel.
The 200-day moving average ema(close,200) is also plotted as a reference to determine the overall trend.
The strategy uses the ema as the benchmark to judge the major trend. When close is above the 200-day line, it indicates an uptrend. When close is below, it indicates a downtrend.
In an uptrend, if the closing price close breaks through the upper band, a long signal is generated. In a downtrend, if close breaks the lower band, a short signal is generated.
The long stop loss is set at the lower band or middle line based on the long/short rules. The short stop loss is set at the upper band or middle line.
Advantage Analysis
The dynamic channel adapts to changing market trends.
Trading signals are generated based on breakouts, following the trend trading principle.
The major trend is determined by moving average, combined with channel breakouts.
Flexible stop loss placement based on market conditions.
Risk Analysis
Wrong judgement of the major trend may deviate from the market.
Improper channel period setting increases incorrect trading.
Stop loss being too close to the channel may increase being stopped out.
Breakout signals have some lag, possibly missing the best entry point.
Solutions:
Use multiple indicators to judge the major trend, reducing errors.
Optimize channel period parameters for different market rhythms.
Adjust stop loss position to have enough buffer.
Add filters to screen entry signals.
Optimization Directions
Add more indicators to judge the major trend, improving accuracy.
Incorporate volume indicators to avoid false breakouts.
Optimize channel period parameters for different products.
Implement dynamic trailing stop loss.
Add filters to improve signal quality and avoid unnecessary trades.
Conclusion
This strategy follows the trend trading principle overall, using dynamic channels to determine volatility range and generating signals from breakouts. It can effectively track trend changes and is a reliable trend following strategy. But major trend judgement and stop loss mechanisms need further optimization and filtering conditions should be added to improve robustness. The strategy suits mid-to-long term trend tracking, and can be combined with other strategies in a portfolio to hedge risks.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 20 | length |
| v_input_2 | 0 | Long Entry: Higher High | Basis |
| v_input_3 | 0 | Short Entry: Lower Low | Basis |
| v_input_4 | 0 | LONG SL: Lower Low | Basis |
| v_input_5 | 0 | SHORT SL: Higher High | Basis |
Source Pine Script
/*backtest
start: 2023-10-13 00:00:00
end: 2023-11-12 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © pratyush_trades

//@version=4
strategy("Donchian Indexes", overlay=true)

length = input(20)
longRule = input("Higher High", "Long Entry", options=["Higher High", "Basis"])
shortRule = input("Lower Low", "Short Entry", options=["Lower Low", "Basis"])
longSL=input("Lower Low", "LONG SL", options=["Lower Low", "Basis"])
shortSL=input("Higher High", "SHORT SL", options=["Higher High", "Basis"])

hh = highest(high, length)
ll = lowest(low, length)

up = plot(hh, 'Upper Band', color = color.green)
dw = plot(ll, 'Lower Band', color = color.red)
mid = (hh + ll) / 2
midPlot = plot(mid, 'Basis', color = color.orange)
fill(up, midPlot, color=color.green, transp = 95)
fill(dw, midPlot, color=color.red, transp = 95)
plot(ema(close,200), "ema", color=color.orange)

if (close>ema(close,200))
    if (not na(close[length]))
        strategy.entry("Long", strategy.long, stop=longRule=='Basis' ? mid : hh)

if (close<ema(close,200))
    if (not na(close[length]))
        strategy.entry("Short", strategy.short, stop=shortRule=='Basis' ? mid : ll)

if (strategy.position_size>0)
    strategy.exit(id="Longs Exit",stop=longSL=='Basis' ? mid : ll)

if (strategy.position_size<0)
    strategy.exit(id="Shorts Exit",stop=shortSL=='Basis' ? mid : hh)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-13. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Channel-Breakout-Strategy-431895.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Donchian Channel and Larry Williams Large Trade Index StrategyPine Script · Breakout · 1m
- Momentum Breakout Trading Strategy 435896Pine Script · Breakout · 1d
- Multi Indicator Short Term Algorithmic Trading StrategyPine Script · Breakout · 4h
- Multi Indicator Trend Breakout Strategy with Dynamic Stop LossPine Script · Breakout · 1d
- Trend Following Strategy with MACD and Donchian ChannelPine Script · Breakout · 1h
- Triple Dragon SystemPine Script · Breakout · 1h