Dynamic Channel Breakthrough Strategy
This strategy uses the Keltner Channel indicator, combined with moving average lines, to set dynamic breakout buy and sell prices to achieve low-buy-high-sell breakthrough operations. The strategy can automatically…
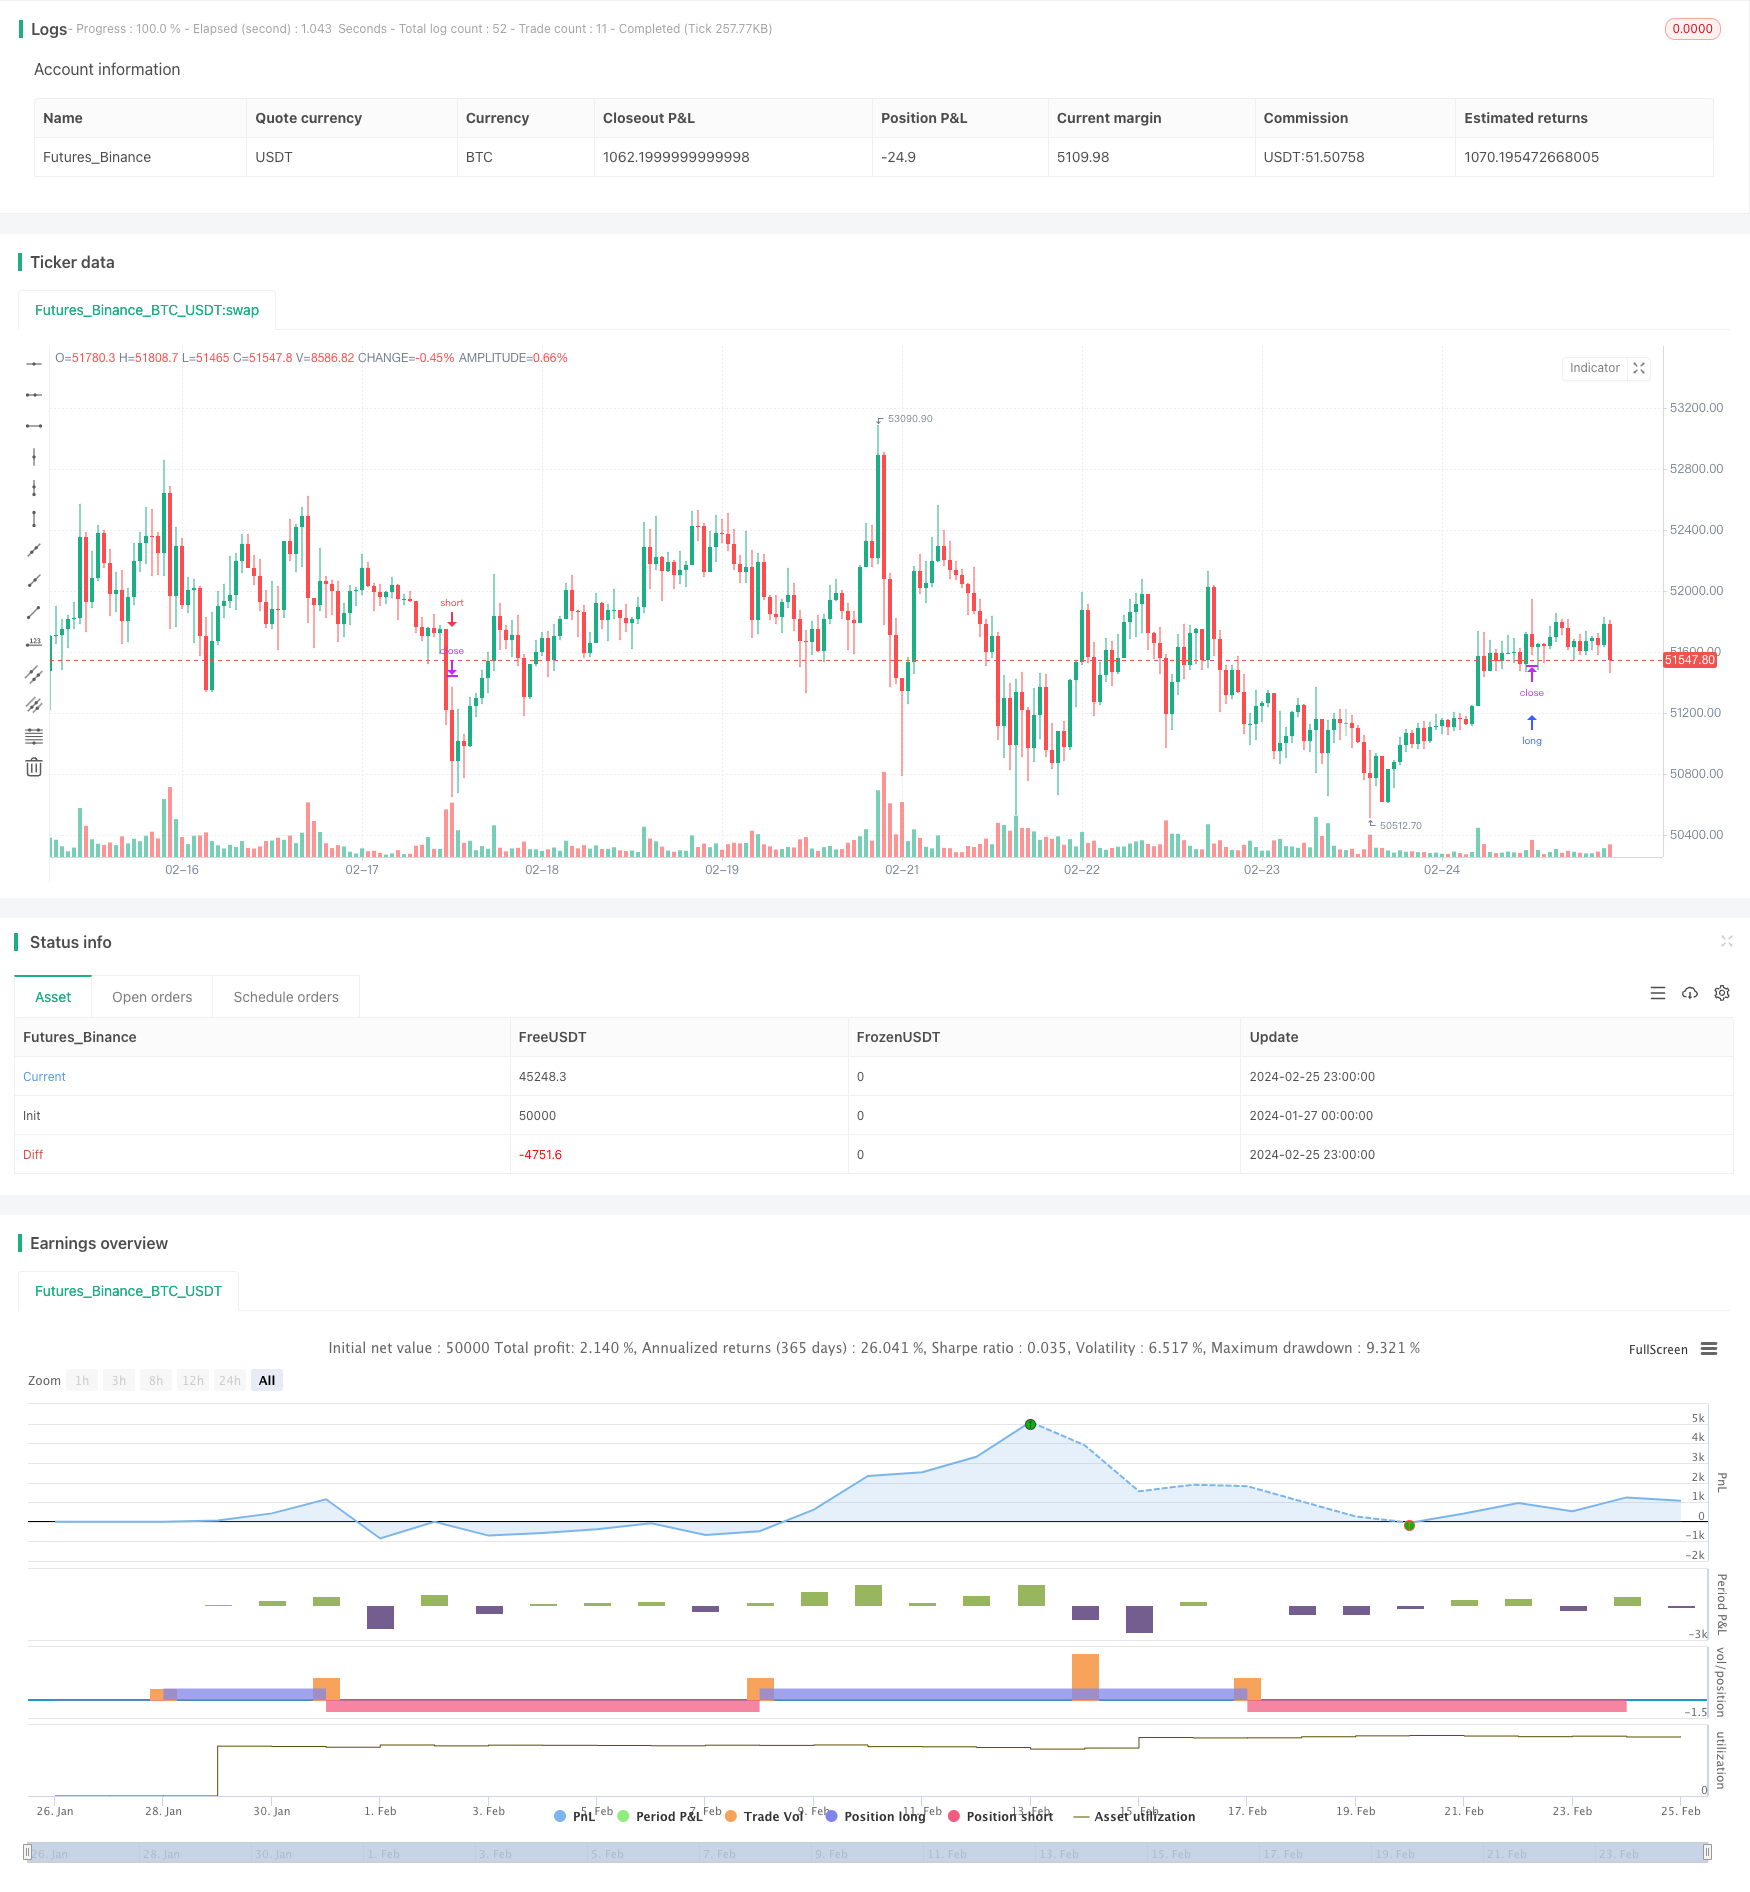
Overview
This strategy uses the Keltner Channel indicator, combined with moving average lines, to set dynamic breakout buy and sell prices to achieve low-buy-high-sell breakthrough operations. The strategy can automatically identify channel breakout buy and sell opportunities.
Strategy Principle
- Calculate channel median: Use exponential moving average to calculate the price median of the channel
- Calculate channel bandwidth: Use the moving average of true volatility, average true volatility or price amplitude to calculate channel bandwidth
- Channel upper and lower rail: Median ± N times channel bandwidth
- Entry order: When the price touches the upper rail, set the breakthrough buy price and wait for the breakthrough; when the price touches the lower rail, set the breakthrough sell price and wait for the breakthrough
- Exit order: Stop loss when price falls back to median after buying, or when highest price exceeds entry price; Stop loss when price bounces back to median after selling, or when lowest price is lower than entry price
Advantage Analysis
- Using dynamic channels can quickly capture changes in market trends
- Using median is conducive to judging the direction of price trends
- N times bandwidth setting makes the channel range reasonable to avoid frequent position adjustments
- Using breakthrough mechanisms conforms to trend theory and follows the trend
- Setting stop loss conditions strictly controls risks
Risk Analysis
- The selection of the method for calculating the median line will affect the matching effect of the channel range and prices
- Excessive large or small N multiples will affect the strategy's rate of return
- Breakthrough buys and sells tend to form false signals and should be strictly stopped out
Optimization Directions
- Try different median line calculation methods to find the optimal parameters
- Test different N values to find the optimal multiplier
- Increase the breakthrough amplitude to avoid false signals
- Optimize stop loss logic to strictly control single loss
Summary
The overall strategy uses scientific and reasonable methods to judge price trends and directions through dynamic channel indicators, sets reasonable parameters to capture breakthrough signals, achieves low-buy-high-sell, and gains excess returns. At the same time, continuously optimize the risks of the strategy so that it can run stably in various markets.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 20 | length |
| v_input_float_1 | 2 | Multiplier |
| v_input_1_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | true | Use Exponential MA |
| v_input_string_1 | 0 | Bands Style: Average True Range | True Range | Range |
| v_input_3 | 10 | ATR Length |
Source Pine Script
/*backtest
start: 2024-01-27 00:00:00
end: 2024-02-26 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy(title="Keltner Strategy", overlay=true)
length = input.int(20, minval=1)
mult = input.float(2.0, "Multiplier")
src = input(close, title="Source")
exp = input(true, "Use Exponential MA")
BandsStyle = input.string("Average True Range", options = ["Average True Range", "True Range", "Range"], title="Bands Style")
atrlength = input(10, "ATR Length")
esma(source, length)=>
	s = ta.sma(source, length)
	e = ta.ema(source, length)
	exp ? e : s
ma = esma(src, length)
rangema = BandsStyle == "True Range" ? ta.tr(true) : BandsStyle == "Average True Range" ? ta.atr(atrlength) : ta.rma(high - low, length)
upper = ma + rangema * mult
lower = ma - rangema * mult
crossUpper = ta.crossover(src, upper)
crossLower = ta.crossunder(src, lower)
bprice = 0.0
bprice := crossUpper ? high+syminfo.mintick : nz(bprice[1])
sprice = 0.0
sprice := crossLower ? low -syminfo.mintick : nz(sprice[1])
crossBcond = false
crossBcond := crossUpper ? true
     : na(crossBcond[1]) ? false : crossBcond[1]
crossScond = false
crossScond := crossLower ? true
     : na(crossScond[1]) ? false : crossScond[1]
cancelBcond = crossBcond and (src < ma or high >= bprice )
cancelScond = crossScond and (src > ma or low <= sprice )
if (cancelBcond)
	strategy.cancel("KltChLE")
if (crossUpper)
	strategy.entry("KltChLE", strategy.long, stop=bprice, comment="KltChLE")
if (cancelScond)
	strategy.cancel("KltChSE")
if (crossLower)
	strategy.entry("KltChSE", strategy.short, stop=sprice, comment="KltChSE")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Channel-Breakthrough-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual Breakout Volatility Channel StrategyPine Script · Breakout · 1h
- Flexible Long Short Trading Strategy Based on Keltner ChannelsPine Script · Breakout · 1d
- Quantitative Trading Price Breakthrough StrategyPine Script · Breakout · 1d
- Integrated Ichimoku Keltner Trading System Based on Moving Average StrategyPine Script · Breakout · 1h
- Keltner Channel Pullback StrategyPine Script · Breakout · 1h
- Multi Technical Indicator Trend Following Channel Breakout Trading Strategy with Candlestick Pattern Filtering SystemPine Script · Breakout · 1h