Strategy vault / Mean reversion
Dynamic Liquidity Cascade Capture Strategy
This strategy is a quantitative trading system specifically designed to capture extreme market volatility periods. It monitors the deviation between price and moving averages to identify potential market liquidity…
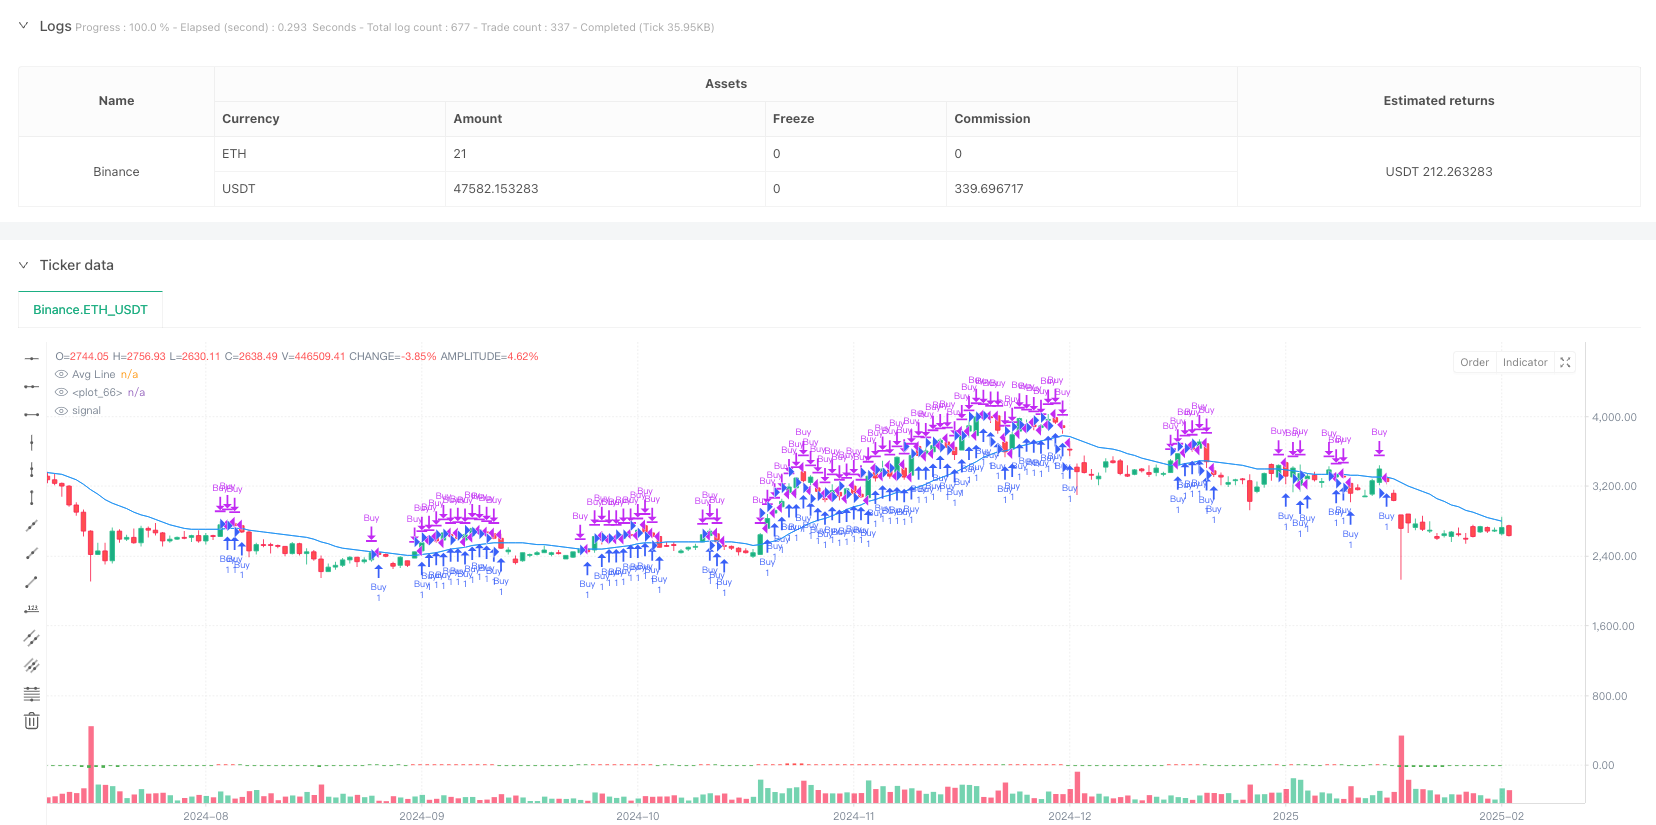
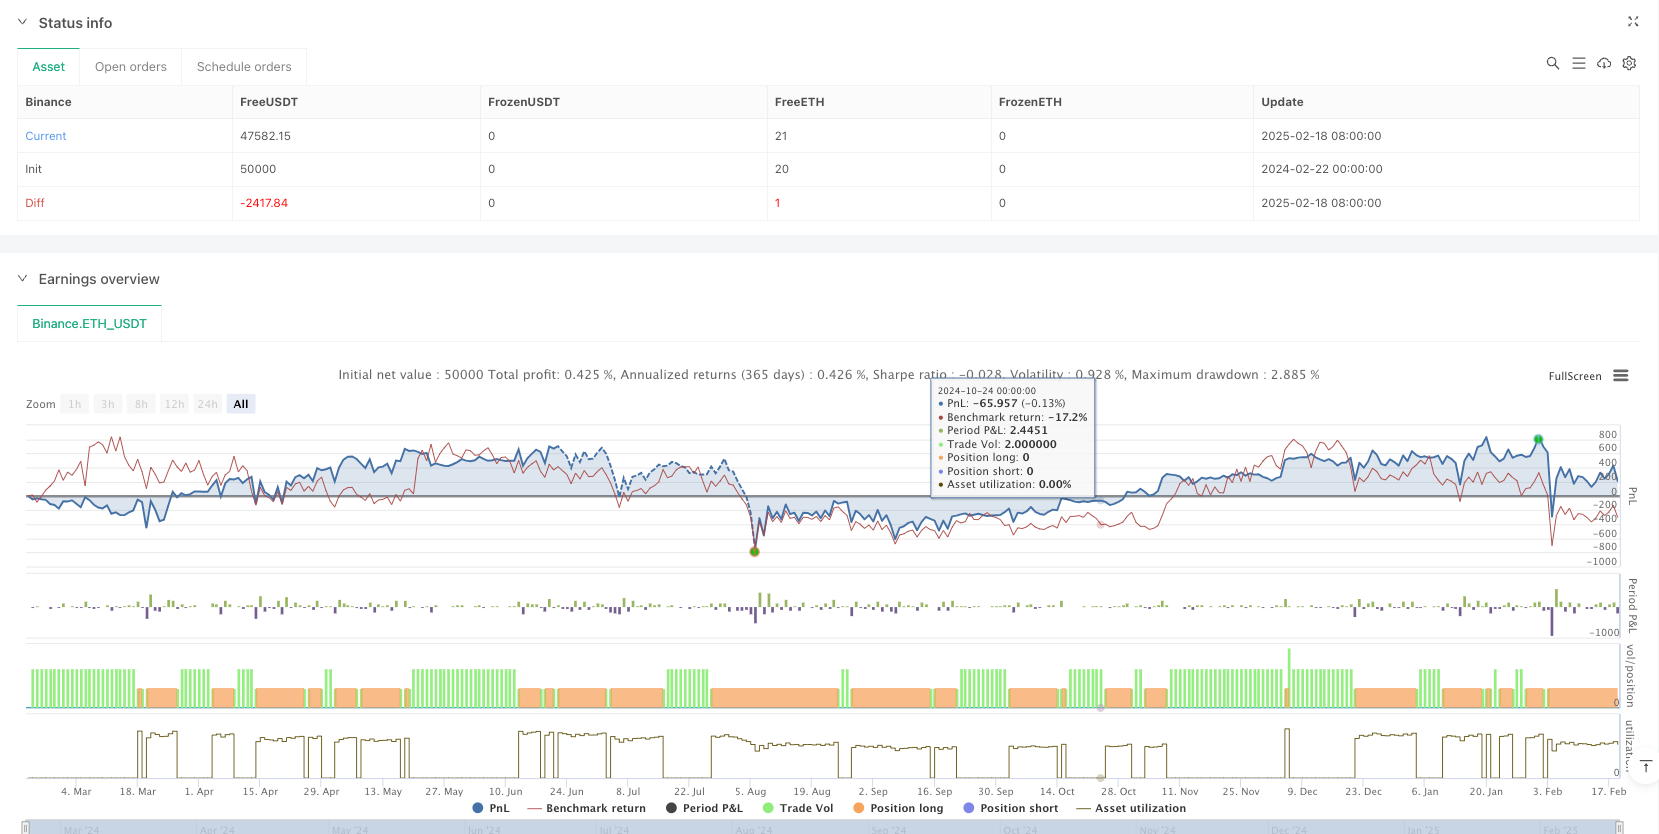
Overview
This strategy is a quantitative trading system specifically designed to capture extreme market volatility periods. It monitors the deviation between price and moving averages to identify potential market liquidity exhaustion situations and capture market reversal opportunities. The strategy incorporates moving average combinations, volatility tracking, and dynamic stop-loss mechanisms to build a complete trading system.
Strategy Principles
The core of the strategy is to identify market anomalies by calculating the deviation between price and moving averages. Specific implementation includes:
- Using a combination of 15-period Simple Moving Average (SMA) and 30-period Exponential Moving Average (EMA) as benchmark prices
- Calculating the percentage deviation between current price and moving average combination
- Determining historical extremes through 89-period highs and lows
- Entering long positions when three consecutive long-side liquidity exhaustion signals occur
- Implementing a triple exit mechanism: technical rebound, reverse liquidity exhaustion signals, and trailing stop-loss
Strategy Advantages
- Precise Market Timing: Multiple indicator confirmation improves entry accuracy
- Comprehensive Risk Control: Multi-layered stop-loss mechanism effectively controls downside risk
- High Adaptability: Strategy automatically adjusts stop-loss range based on market volatility
- Strong Execution: Clear entry and exit conditions reduce subjective judgment
- High Systematization: Entire trading process is based on quantitative indicators, easy to automate
Strategy Risks
- False Signal Risk: May generate incorrect liquidity exhaustion signals in sideways markets
- Slippage Risk: May face significant execution slippage under extreme market conditions
- Parameter Sensitivity: Strategy performance is sensitive to moving average periods and stop-loss multipliers
- Market Environment Dependency: Strategy returns may be suboptimal in low volatility environments
- Technical Risk: System stability must be maintained to avoid signal delays or losses
Strategy Optimization Directions
- Incorporate Volume Indicators: Confirm liquidity exhaustion signals through volume analysis
- Optimize Parameter Adaptivity: Dynamically adjust strategy parameters based on market volatility states
- Add Market Environment Filters: Pause trading in unsuitable market conditions
- Enhance Stop-Loss Mechanism: Consider adding volatility-based dynamic stop-loss
- Improve Signal Confirmation: Add more technical indicators to filter false signals
Summary
The Dynamic Liquidity Cascade Capture Strategy is a quantitative trading system focused on capturing extreme market situations. Through scientific indicator combinations and strict risk control, the strategy can capture trading opportunities during intense market volatility. While certain risks exist, through continuous optimization and improvement, the strategy has the potential to maintain stable performance across various market environments.
Source Pine Script
/*backtest
start: 2024-02-22 00:00:00
end: 2025-02-19 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Binance","currency":"ETH_USDT"}]
*/

//@version=5
strategy("Liquidation Cascade Strategy", overlay=true)

// Paramètres de l'indicateur de liquidation
var float lastHigh = na
var float lastLow = na
var float lastPriceLow = na
var float lastPriceHigh = na
var bool shortLiq = na
var bool longLiq = na

src = close
maLength1 = 15
maLength2 = 30
ma1 = ta.sma(src, maLength1)
ma2 = ta.ema(src, maLength2)
avgLine = (ma1 + ma2) / 2
distVal = ((src - avgLine) / avgLine) * 100

ph = ta.highest(distVal, 89)
pl = ta.lowest(distVal, 89)

if ph == distVal and ph > 0
    lastHigh := distVal
    lastPriceHigh := high

if pl == distVal and pl < 0
    lastLow := distVal
    lastPriceLow := low

shortLiq := not na(lastHigh) and lastHigh == distVal and distVal > 0
longLiq := not na(lastLow) and lastLow == distVal and distVal < 0

// Condition d'achat : 3 liquidations longues consécutives
buyCondition = ta.valuewhen(longLiq, longLiq, 0) and ta.valuewhen(longLiq, longLiq, 1) and ta.valuewhen(longLiq, longLiq, 2)
if (buyCondition)
    strategy.entry("Buy", strategy.long)

// Conditions de vente
var float entryPrice = na
var bool positionOpen = false

// Mise à jour du prix d'entrée
if (buyCondition)
    entryPrice := close
    positionOpen := true

// 1. Vente sur rebond technique (distVal > -1%)
sellCondition1 = distVal > -1 and positionOpen

// 2. Vente sur liquidation courte
sellCondition2 = shortLiq and positionOpen

// 3. Trailing Stop (2x ATR)
atr = ta.atr(14)
trailingStop = close - 2 * atr
sellCondition3 = close < trailingStop and positionOpen

// Exécution des ventes
if (sellCondition1 or sellCondition2 or sellCondition3)
    strategy.close("Buy")
    positionOpen := false

// Visualisation
plot(avgLine, color=color.blue, title="Avg Line")
plot(distVal, color=distVal > 0 ? color.red : color.green, style=plot.style_columns)Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Liquidity-Cascade-Capture-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trend Following and Cloud Reversal Composite Trading StrategyPine Script · Mean reversion · 1d
- Bidirectional Moving Average Reversion Trading StrategyPine Script · Mean reversion · 1h
- Comprehensive Strategy of Multiple Candlestick PatternsPine Script · Mean reversion · 1h
- Customizable Non Repainting HTF MACD MFI Scalable Bot StrategyPine Script · Mean reversion · 1d
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d