Strategy vault / Trend following
Dynamic Moving Average Retracement Martin Strategy
The Dynamic Moving Average Retracement Martin strategy is a frequent trading strategy that combines moving average crossovers and pullback signals to generate entry and exit signals. The strategy uses the crossover…
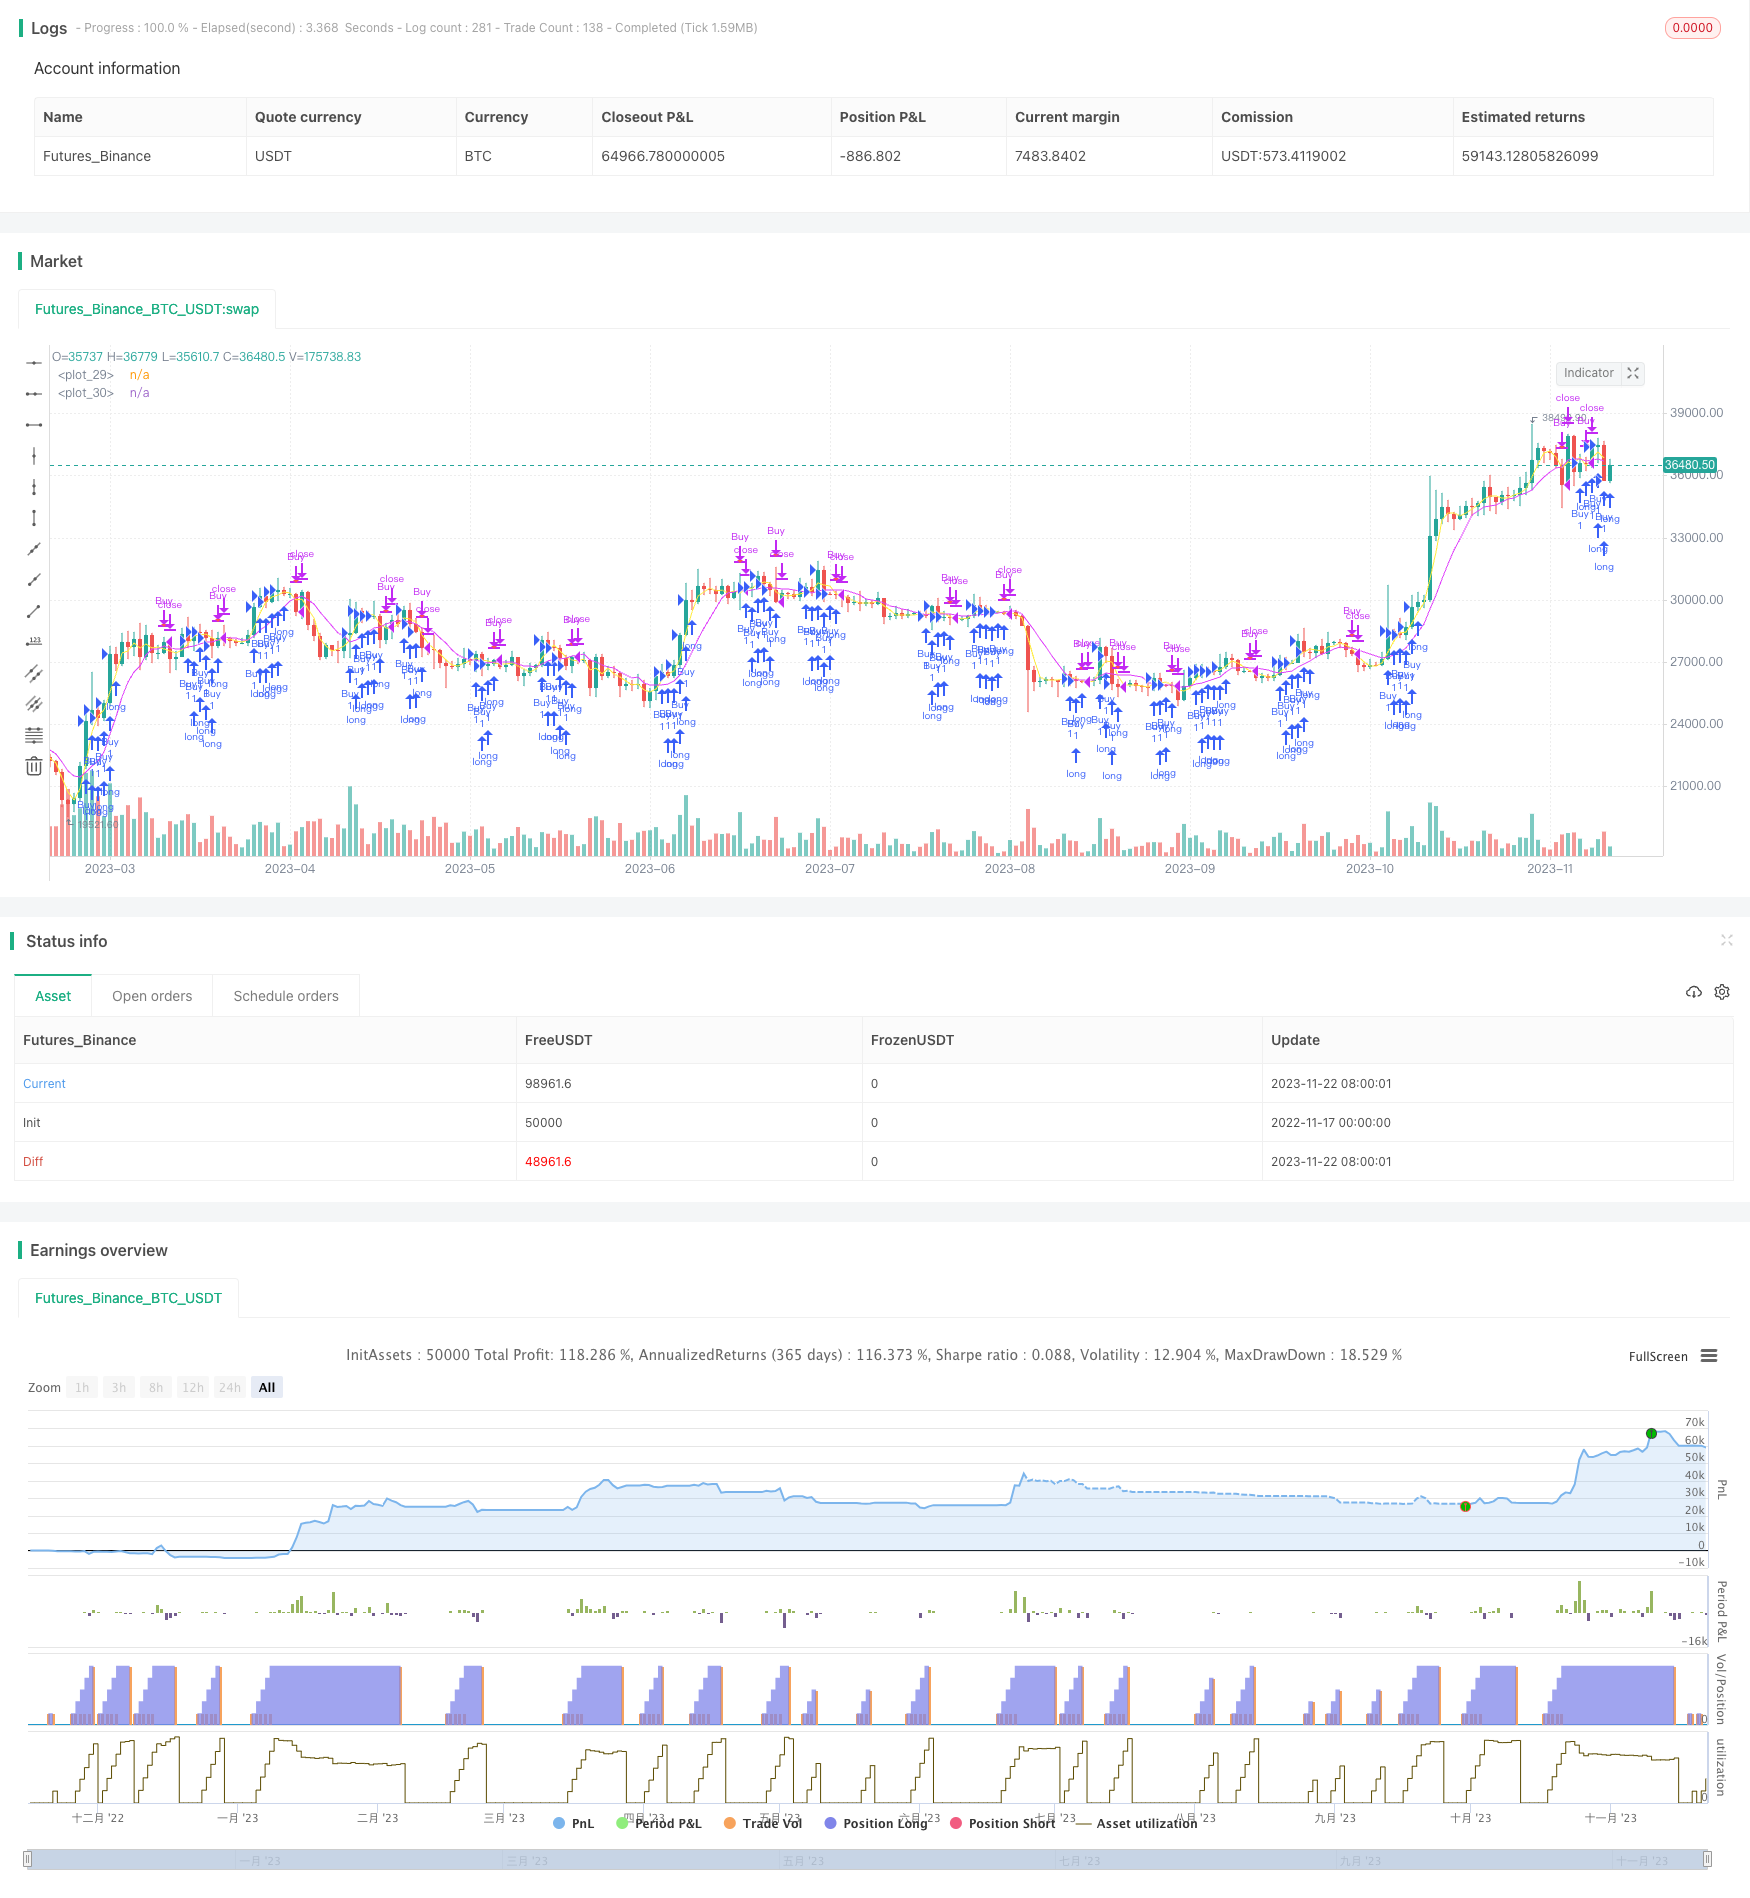
Overview
The Dynamic Moving Average Retracement Martin strategy is a frequent trading strategy that combines moving average crossovers and pullback signals to generate entry and exit signals. The strategy uses the crossover and divergence of 3-day and 8-day simple moving averages to capture short-term trends, and adopts stops and take profits to control risks. This strategy allows choosing trading directions according to different market conditions.
Strategy Logic
The strategy uses 3-day and 8-day simple moving averages and their crossover signals. A long signal is generated when the 3-day MA crosses above the 8-day MA, and a short signal is generated when the 3-day MA crosses below the 8-day MA. Long signals will trigger long entry and short signals will trigger short entry.
If there is no position, the strategy will determine entry based on crossover signals. After entry, the stop loss price and take profit price will be calculated based on the latest close price, stop loss percentage and take profit percentage. For example, when holding a long position, the stop loss price is the latest close price minus the stop loss percentage multiplied by the 8-day MA; the take profit price is the latest close price plus the take profit percentage multiplied by the 8-day MA.
If there is an existing long position, when the price triggers the take profit or stop loss, if a pullback signal of the 8-day MA occurs, the position will be closed. At this time, the stop loss price and take profit price will be reset to 0. The logic for handling short positions is similar.
The strategy also plots entry and exit points on the chart. For example, a long entry is plotted as an upward triangle and a long exit as a downward triangle. This helps to visually judge entries and exits.
Advantage Analysis
The advantages of this strategy are:
- Captures short-term trends using moving average crossover signals, allowing frequent trading.
- The stop loss mechanism can control single loss.
- Take profit setting can lock in partial profits.
- Trading directions can be selected to suit different stages.
- Visualizes entry and exit points on chart for clarity.
Risk Analysis
The main risks of this strategy are:
- Short-term MA strategies tend to be whipsawed.
- Possibility of lagging signals from moving averages.
- Consecutive losses may lead to aggravated losses.
- Incorrectly set stop loss percentage may be too loose or too tight.
Risks can be reduced by reasonably widening stop loss percentage, optimizing MA parameters, introducing additional filter conditions, etc. Also, correctly assessing personal tolerance and avoiding overtrading is important.
Optimization Directions
This strategy can be optimized from the following aspects:
- Test more MA combinations to find optimal parameters.
- Add other indicators like RSI, KD etc. to improve signal quality.
- Adjust stop loss percentage according to different products and timeframes.
- Add position sizing control such as fixed quantity or fixed capital.
- Add entry order rules.
- Optimize and evaluate stop loss or take profit levels.
Summary
The Dynamic Moving Average Retracement Martin strategy is a short-term trading strategy. It captures short-term trends formed by moving average crossovers, and manages risks with proper stops and take profits. The frequent trading nature gives it profit opportunities as well as risks. By optimizing parameters, filtering signals and controlling risks, this strategy can be further improved for more reliability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 1.03 | Take Profit |
| v_input_2 | 0.95 | Stop Loss |
| v_input_string_1 | 0 | Trading Mode: Long | Short | BiDir |
Source Pine Script
/*backtest
start: 2022-11-17 00:00:00
end: 2023-11-23 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

    // ____  __    ___   ________ ___________  ___________ __  ____ ___
   // / __ )/ /   /   | / ____/ //_/ ____/   |/_  __<  / // / / __ |__ \
  // / __  / /   / /| |/ /   / ,< / /   / /| | / /  / / // /_/ / / __/ /
 // / /_/ / /___/ ___ / /___/ /| / /___/ ___ |/ /  / /__  __/ /_/ / __/
// /_____/_____/_/  |_\____/_/ |_\____/_/  |_/_/  /_/  /_/  \____/____/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © blackcat1402
//@version=5
strategy('[blackcat] L1 MartinGale Scalping Strategy', overlay=true, pyramiding = 5)

// Define input variables
takeProfit = input(1.03, title='Take Profit')
stopLoss = input(0.95, title='Stop Loss')
inputTradingMode = input.string(defval='Long', options=['Long', 'Short', 'BiDir'], title='Trading Mode')

//The purpose of this rule is to forbid short entries, only long etries will be placed. The rule affects the following function: 'entry'.
strategy.risk.allow_entry_in(inputTradingMode == 'Long' ? strategy.direction.long : inputTradingMode == 'Short' ? strategy.direction.short : strategy.direction.all)

// Define strategy logic
entryPrice = 0.0
stopPrice = 0.0
takeProfitPrice = 0.0
stopLossPrice = 0.0

// Define SMA crossover and crossunder signals
sma3 = ta.sma(close, 3)
sma8 = ta.sma(close, 8)
plot(sma3, color=color.yellow)
plot(sma8, color=color.fuchsia)
crossoverSignal = ta.crossover(sma3, sma8)
crossunderSignal = ta.crossunder(sma3, sma8)
crossoverState = sma3 > sma8
crossunderState = sma3 < sma8

if strategy.position_size == 0
    if crossoverState
        strategy.entry('Buy', strategy.long)
        entryPrice := close
        stopPrice := close - stopLoss * sma8[1]
        takeProfitPrice := close + takeProfit * sma8[1]
        stopLossPrice := stopPrice
        stopLossPrice
    if crossunderState
        strategy.entry('Sell', strategy.short)
        entryPrice := close
        stopPrice := close + stopLoss *  sma8[1]
        takeProfitPrice := close - takeProfit *  sma8[1]
        stopLossPrice := stopPrice
        stopLossPrice

if strategy.position_size > 0
    if (close > takeProfitPrice or close < stopLossPrice) and crossunderState
        strategy.close('Buy')
        entryPrice := 0.0
        stopPrice := 0.0
        takeProfitPrice := 0.0
        stopLossPrice := 0.0
        stopLossPrice
    else
        strategy.entry('Buy', strategy.long)
        entryPrice := close
        stopPrice := close - stopLoss *  sma8[1]
        takeProfitPrice := close + takeProfit *  sma8[1]
        stopLossPrice := stopPrice
        stopLossPrice

if strategy.position_size < 0
    if (close > takeProfitPrice or close < stopLossPrice) and crossoverState
        strategy.close('Sell')
        entryPrice := 0.0
        stopPrice := 0.0
        takeProfitPrice := 0.0
        stopLossPrice := 0.0
        stopLossPrice
    else
        strategy.entry('Sell', strategy.short)
        entryPrice := close
        stopPrice := close + stopLoss *  sma8[1]
        takeProfitPrice := close - takeProfit *  sma8[1]
        stopLossPrice := stopPrice
        stopLossPrice

// Plot entry and exit points
plotshape(strategy.position_size > 0 and crossoverSignal, 'Buy Entry', shape.triangleup, location.belowbar, color.new(color.green, 0), size=size.small)
plotshape(strategy.position_size > 0 and (close >= takeProfitPrice or close <= stopLossPrice), 'Buy Exit', shape.triangledown, location.abovebar, color.new(color.red, 0), size=size.small)
plotshape(strategy.position_size < 0 and crossunderSignal, 'Sell Entry', shape.triangledown, location.abovebar, color.new(color.red, 0), size=size.small)
plotshape(strategy.position_size < 0 and (close >= takeProfitPrice or close <= stopLossPrice), 'Sell Exit', shape.triangleup, location.belowbar, color.new(color.green, 0), size=size.small)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Moving-Average-Retracement-Martin-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m