Strategy vault / Trend following
Dynamic Pivot Points with Golden Cross Optimization System
This strategy is a quantitative trading system that combines pivot point theory and moving average crossover signals in technical analysis. The strategy identifies key support and resistance levels in the market…
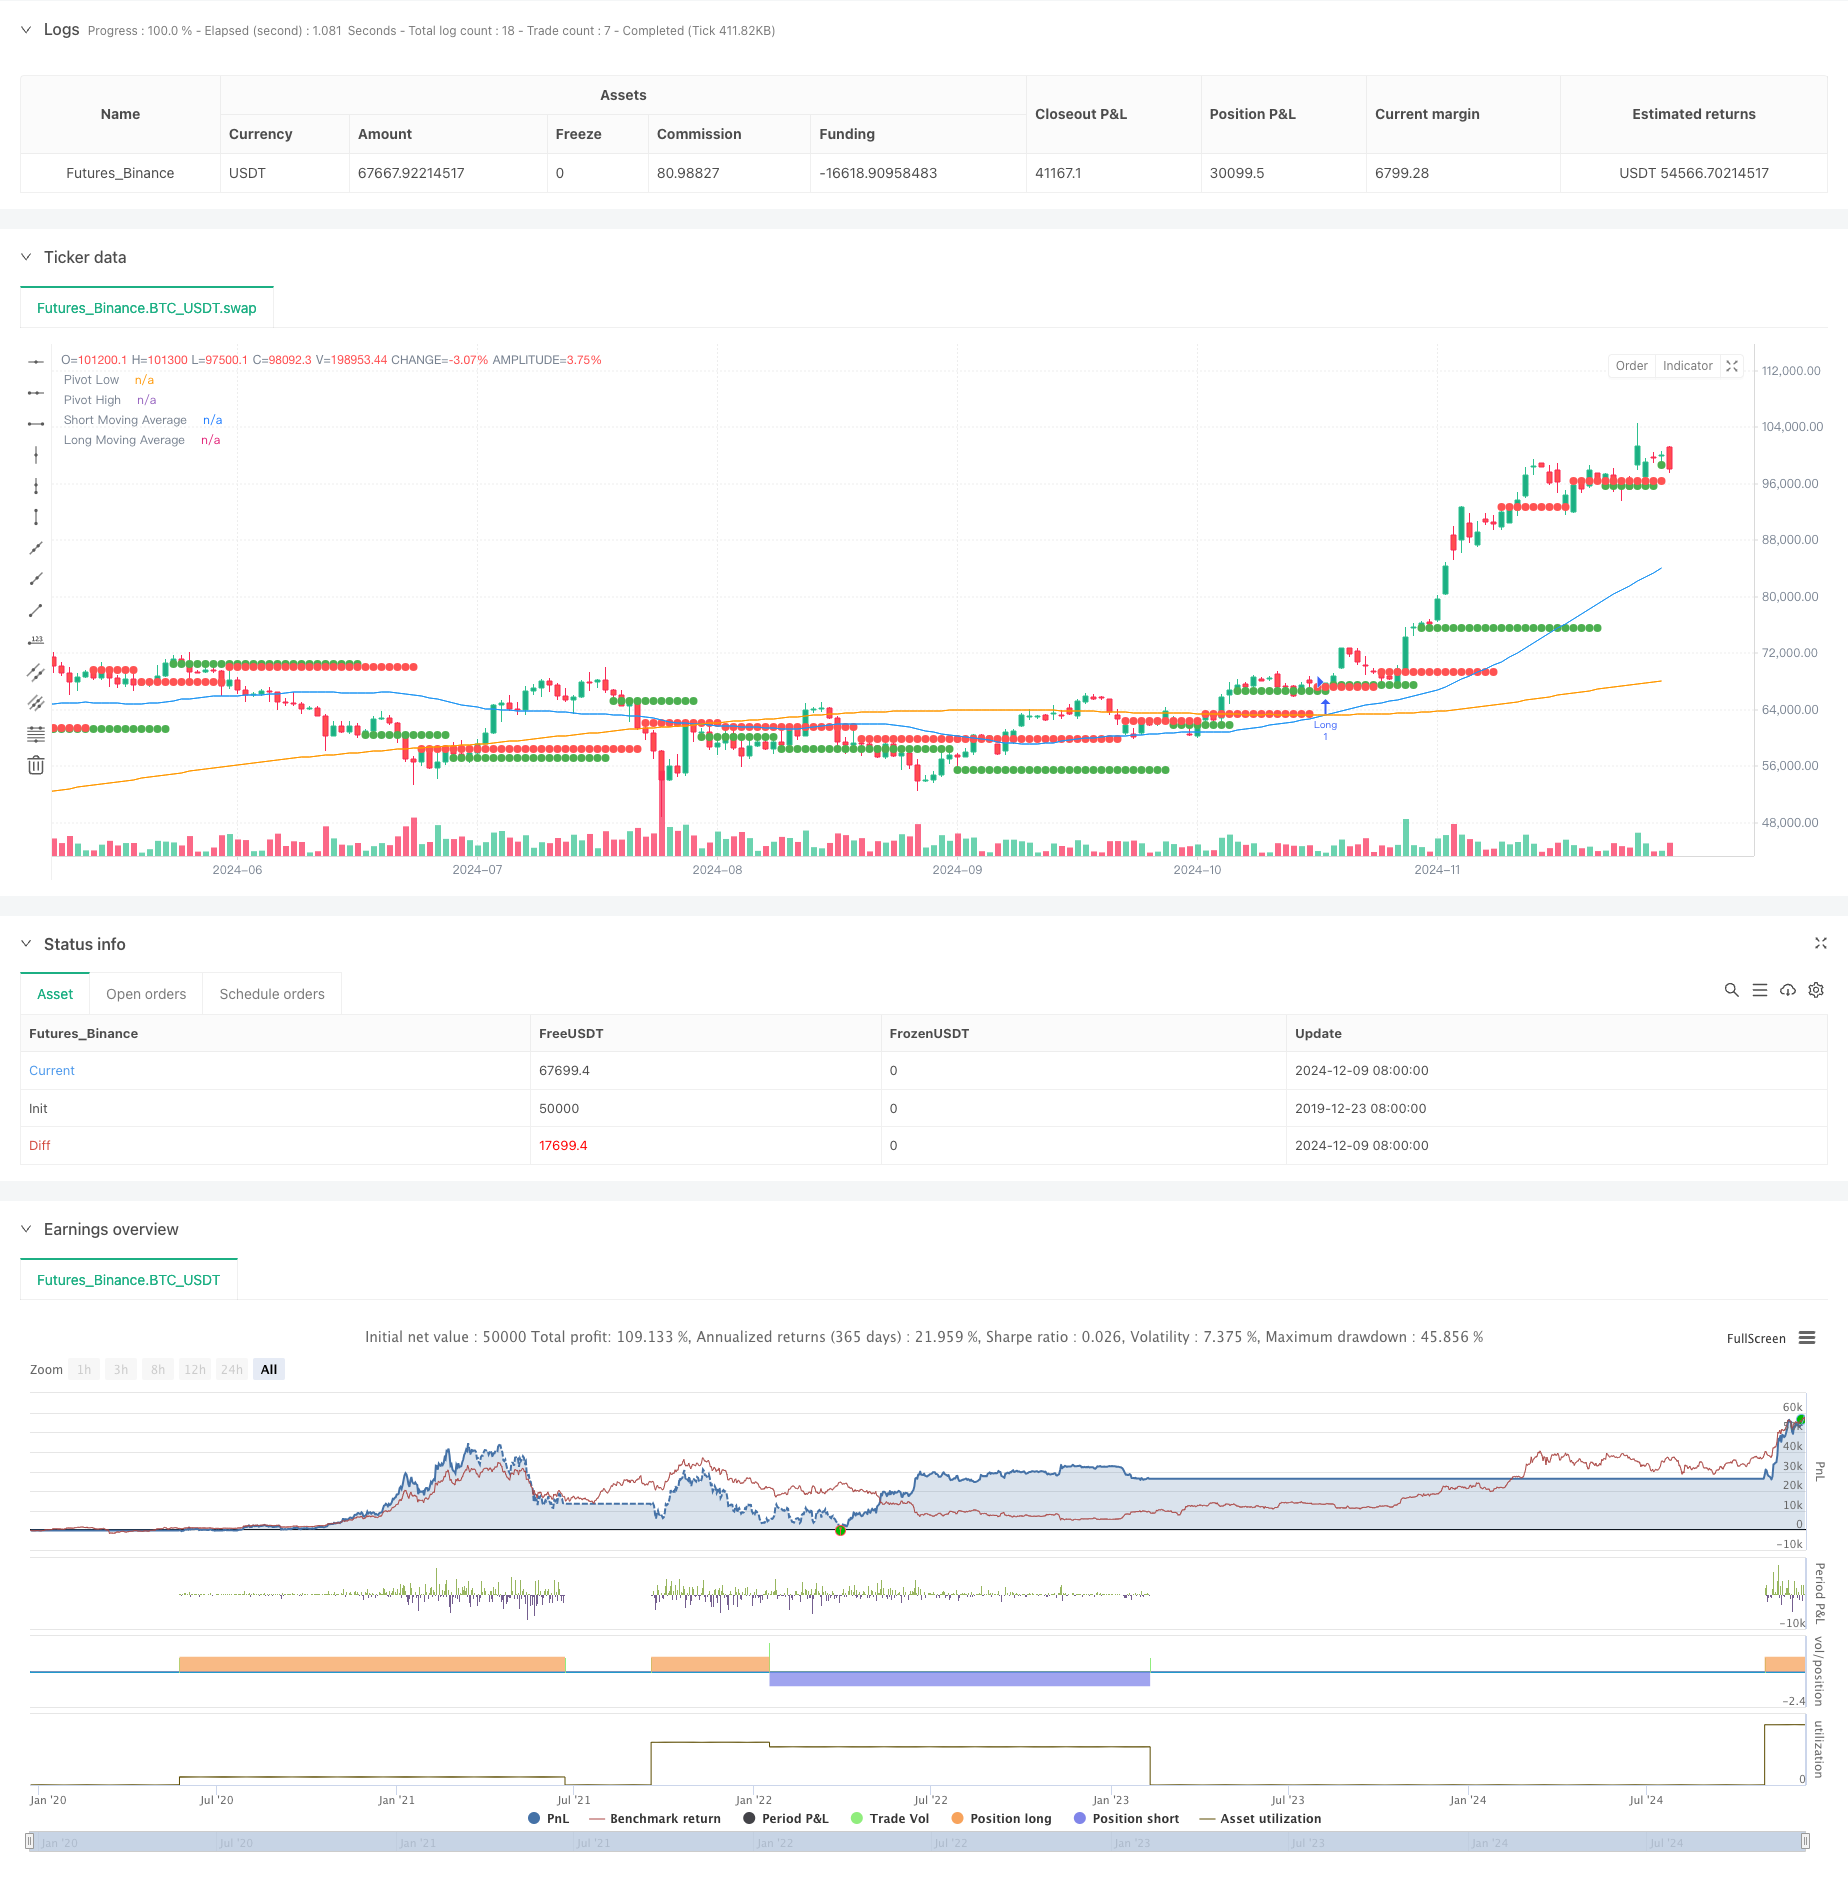
Overview
This strategy is a quantitative trading system that combines pivot point theory and moving average crossover signals in technical analysis. The strategy identifies key support and resistance levels in the market, combined with crossover signals from short-term and long-term moving averages to capture trading opportunities during market trend changes. The system uses 50-day and 200-day moving averages as primary indicators, optimizing entry and exit timing through dynamic pivot point tracking.
Strategy Principles
The core logic of the strategy is based on two main components: pivot point analysis and moving average crossover signals. The system uses a 5-period cycle for pivot point calculation, dynamically identifying market highs and lows through ta.pivothigh and ta.pivotlow functions. Meanwhile, it generates golden cross and death cross signals using the crossover of 50-day and 200-day simple moving averages. Long signals are generated when the short-term moving average crosses above the long-term moving average and price breaks above recent pivot highs; short signals are generated when the short-term moving average crosses below the long-term moving average and price breaks below recent pivot lows.
Strategy Advantages
- High signal reliability: Combines pivot points and moving average crossovers for double confirmation, significantly improving trading signal reliability.
- Strong dynamic adaptability: Dynamic pivot point calculation allows the strategy to adapt to different market environments.
- Comprehensive risk control: Uses long-term moving average as a trend filter, effectively reducing false breakout risks.
- Clear execution logic: Entry and exit conditions are well-defined, facilitating live trading and backtesting verification.
- Large parameter optimization space: Key parameters can be optimized according to different market characteristics.
Strategy Risks
- Choppy market risk: May generate frequent false breakout signals during consolidation phases.
- Lag risk: Moving averages have inherent lag, potentially causing delayed entry and exit timing.
- Parameter sensitivity: Choice of pivot point period and moving average periods significantly impacts strategy performance.
- Market environment dependency: Strategy performs better in strong trend markets but may underperform in ranging markets.
- Drawdown control risk: Requires additional stop-loss mechanisms to control maximum drawdown.
Strategy Optimization Directions
- Introduce volatility filtering: Recommend adding ATR indicator for dynamic position sizing and stop-loss placement.
- Optimize pivot point calculation: Consider using adaptive periods for pivot point calculation to improve accuracy.
- Add trend strength confirmation: Suggest incorporating ADX or similar trend strength indicators to filter weak market signals.
- Improve money management: Recommend dynamic position sizing based on market volatility.
- Enhance exit mechanism: Can add trailing stops to protect profits.
Summary
The strategy builds a logically rigorous and risk-controlled quantitative trading system by combining classical technical analysis methods. Its core advantage lies in improving trading reliability through multiple signal confirmations, while attention must be paid to adaptability in different market environments. Through the suggested optimization directions, the strategy's stability and profitability can be further enhanced. The strategy is suitable for markets with clear trends, and investors need to optimize parameters according to specific market characteristics when implementing.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-12-10 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Pivot Points & Golden Crossover Strategy", overlay=true)

// Inputs
length_short = input.int(50, title="Short Moving Average (Golden Cross)")
length_long = input.int(200, title="Long Moving Average (Golden Cross)")
pivot_length = input.int(5, title="Pivot Point Length")
lookback_pivots = input.int(20, title="Lookback Period for Pivots")

// Moving Averages
short_ma = ta.sma(close, length_short)
long_ma = ta.sma(close, length_long)

// Pivot Points
pivot_high = ta.valuewhen(ta.pivothigh(high, pivot_length, pivot_length), high, 0)
pivot_low = ta.valuewhen(ta.pivotlow(low, pivot_length, pivot_length), low, 0)

// Calculate golden crossover
golden_crossover = ta.crossover(short_ma, long_ma)
death_cross = ta.crossunder(short_ma, long_ma)

// Entry and Exit Conditions
long_entry = golden_crossover and close > pivot_high
short_entry = death_cross and close < pivot_low

// Exit conditions
long_exit = ta.crossunder(short_ma, long_ma)
short_exit = ta.crossover(short_ma, long_ma)

// Plot Moving Averages
plot(short_ma, color=color.blue, title="Short Moving Average")
plot(long_ma, color=color.orange, title="Long Moving Average")

// Plot Pivot Levels
plot(pivot_high, color=color.red, linewidth=1, style=plot.style_circles, title="Pivot High")
plot(pivot_low, color=color.green, linewidth=1, style=plot.style_circles, title="Pivot Low")

// Strategy Execution
if (long_entry)
    strategy.entry("Long", strategy.long)
if (long_exit)
    strategy.close("Long")

if (short_entry)
    strategy.entry("Short", strategy.short)
if (short_exit)
    strategy.close("Short")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Pivot-Points-with-Golden-Cross-Optimization-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Factor Trend Price Action Strategy with Dynamic Risk Management SystemPine Script · Trend following · 2h
- Multi Indicator Dynamic Trend Following Strategy Based on EMA and SMAPine Script · Trend following · 1d
- Trend Following Strategy Based on PMax IndicatorPine Script · Trend following · 5m
- Trend Tracking and Short term Trading Strategy Based on ADX IndicatorPine Script · Trend following · 1d
- Triple Supertrend Ichimoku Cloud Quantitative Trading StrategyPine Script · Trend following · 1d