Dynamic Position Size and Trailing Stop SMA Rebound Strategy
This strategy is an automated trading system based on moving average crossovers and dynamic position management. It utilizes 50-day and 200-day Simple Moving Averages (SMA) as primary indicators, combined with…
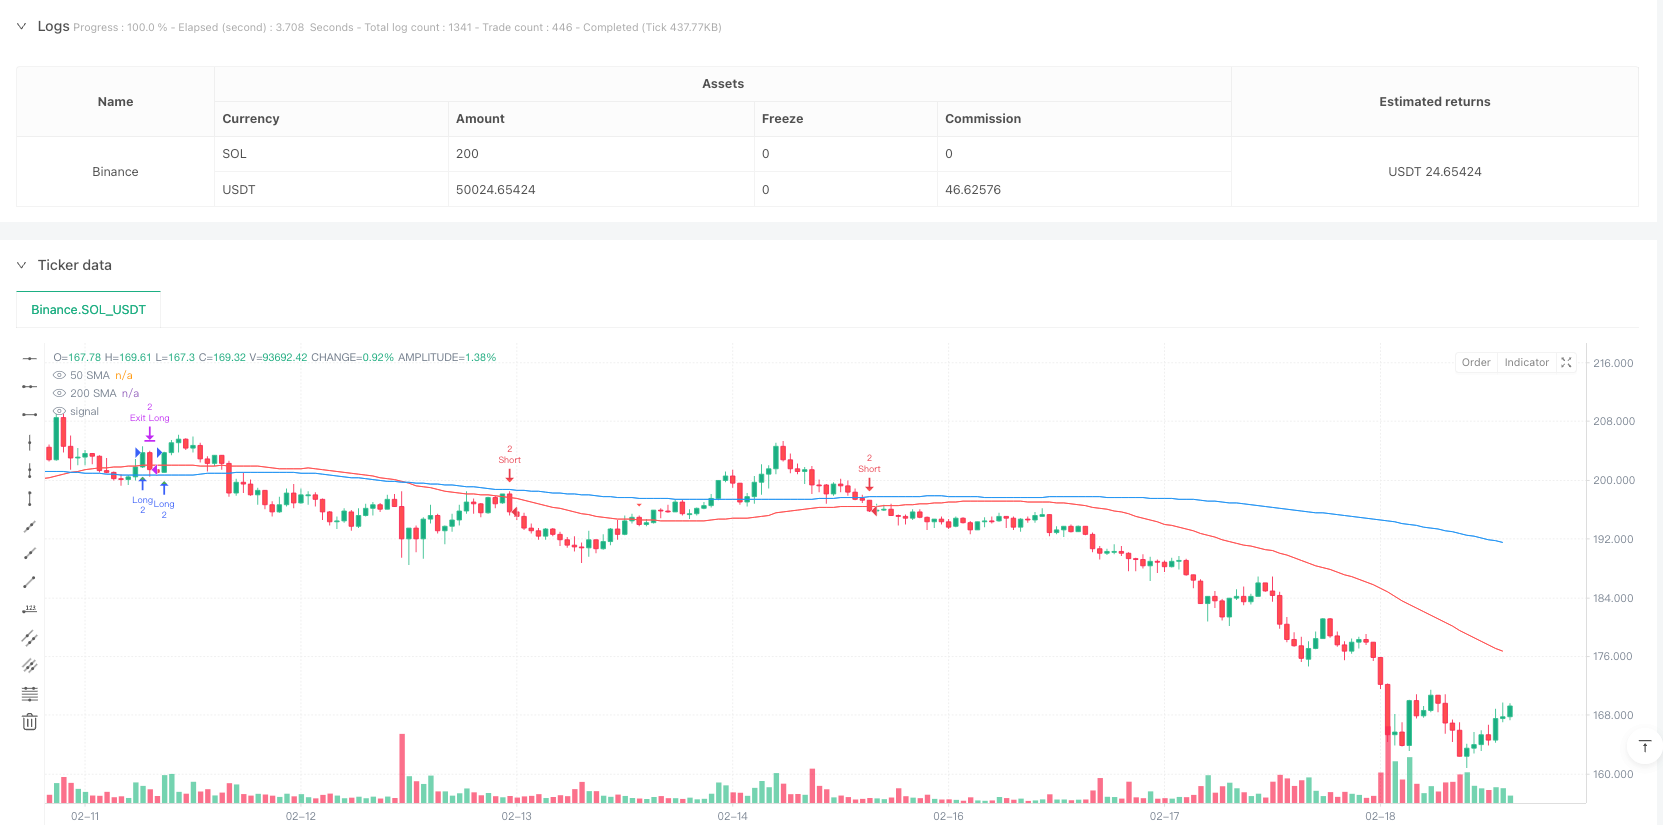
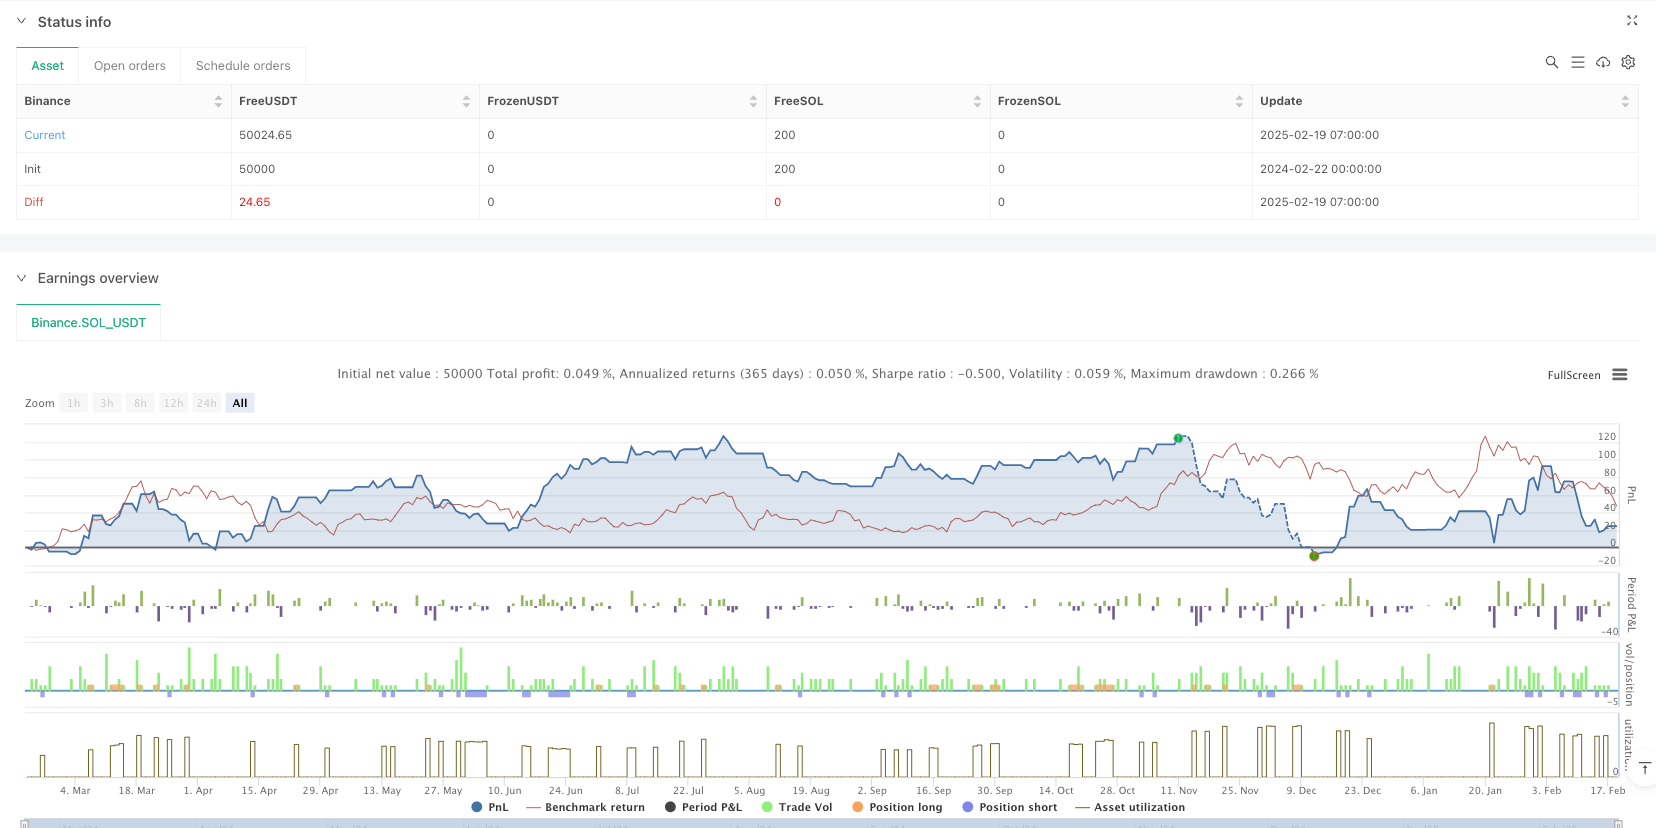
Overview
This strategy is an automated trading system based on moving average crossovers and dynamic position management. It utilizes 50-day and 200-day Simple Moving Averages (SMA) as primary indicators, combined with dynamic position sizing and trailing stop mechanisms to identify trading opportunities in market trends. The core of the strategy lies in determining market direction through price-MA relationships while employing money management and risk control to ensure trading stability.
Strategy Principles
The strategy operates on the following core principles:
- Entry signals are based on price crossovers with the 50-day MA, while using the relative position of 50-day and 200-day MAs to judge the broader trend
- Long signals are triggered when price breaks above the MA from below; short signals occur in the opposite scenario
- Position management employs a dynamic adjustment mechanism, increasing position size when account profits exceed 4000
- Stop-loss uses a trailing stop mechanism, dynamically adjusting stop positions as profits increase
- Risk-reward ratio is set at 1:2.5, ensuring expected returns exceed risks for each trade
Strategy Advantages
- Clear and explicit trading logic, combining technical indicators and price action for entry timing
- Dynamic position management allows for increased trading size during profitable periods, improving capital efficiency
- Trailing stop mechanism effectively locks in profits and prevents significant drawdowns
- Includes trading session filters, operating only during major trading sessions to avoid low liquidity risks
- Comprehensive risk control mechanisms including stop-loss, profit targets, and position management
Strategy Risks
- May trigger frequent false breakout signals in ranging markets, leading to consecutive stops
- Dynamic position sizing could result in larger losses during sudden market reversals
- Reliance on moving averages may lead to delayed reactions in rapidly volatile markets
- Fixed risk-reward ratio might miss potential larger trend opportunities
- Trading time restrictions could miss important market opportunities
Strategy Optimization Directions
- Introduce volatility indicators to dynamically adjust parameters in different market conditions
- Consider adding market sentiment indicators to improve entry signal accuracy
- Optimize trailing stop parameters for better adaptation to different market environments
- Add multiple timeframe analysis to enhance system stability
- Incorporate volume analysis to improve signal reliability
Summary
The strategy builds a relatively complete trading system by combining moving average systems, dynamic position management, and trailing stop mechanisms. Its strengths lie in clear trading logic and comprehensive risk control mechanisms, though there are areas for optimization. Through continuous improvement and optimization, the strategy shows promise for better performance in actual trading.
Source Pine Script
/*backtest
start: 2024-02-22 00:00:00
end: 2025-02-19 08:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Binance","currency":"SOL_USDT"}]
*/

//@version=5
strategy("15m - Rebound 50SMA with Dynamic Lots & Trailing Stop, RRR 2:1, Date Filter (Closed Bars Only)",
     overlay=true,
     initial_capital=50000,
     default_qty_type=strategy.fixed,
     default_qty_value=1,
     pyramiding=0,
     calc_on_order_fills=true)

// ===== INPUTS =====
sma50Period  = input.int(50, "50 SMA Period", minval=1)
sma200Period = input.int(200, "200 SMA Period", minval=1)

// ===== CALCULATE SMAs =====
sma50  = ta.sma(close, sma50Period)
sma200 = ta.sma(close, sma200Period)

// ===== PLOT SMAs =====
plot(sma50, color=color.red, title="50 SMA")
plot(sma200, color=color.blue, title="200 SMA")

// ===== DEFINE TRADING SESSIONS =====
// Trading is allowed 15 minutes after market open:
//   - New York: 09:45–16:00 (America/New_York)
//   - London:   08:15–16:00 (Europe/London)
nySession     = not na(time("15", "0945-1600", "America/New_York"))
londonSession = not na(time("15", "0815-1600", "Europe/London"))
inSession     = nySession or londonSession

// ===== DEFINE DATE RANGE =====
// Only allow orders on or after January 1, 2024.
// (We include seconds in the timestamp for proper parsing.)
startDate   = timestamp("UTC", 2024, 1, 1, 0, 0, 0)
inDateRange = time >= startDate

// ===== DEFINE ENTRY CONDITIONS =====
// ----- LONG ENTRY CONDITION -----
// A long entry is triggered when:
//   - The previous candle closed below the 50 SMA and the current candle closes above it,
//   - And the 50 SMA is above the 200 SMA.
longCondition = (close[1] < sma50[1]) and (close > sma50) and (sma50 > sma200)

// ----- SHORT ENTRY CONDITION -----
// A short entry is triggered when:
//   - The previous candle closed above the 50 SMA and the current candle closes below it,
//   - And the 50 SMA is below the 200 SMA.
shortCondition = (close[1] > sma50[1]) and (close < sma50) and (sma50 < sma200)

// ===== DEBUG PLOTS =====
plotshape(longCondition and barstate.isconfirmed, title="Long Signal", location=location.belowbar, color=color.green, style=shape.triangleup, size=size.tiny)
plotshape(shortCondition and barstate.isconfirmed, title="Short Signal", location=location.abovebar, color=color.red, style=shape.triangledown, size=size.tiny)

// ===== VARIABLES FOR STOP LOSS MANAGEMENT =====
// For long positions.
var float initialLongStop = na   // Set at entry: low of the rebound candle.
var float trailStopLong   = na   // Updated trailing stop for long.
// For short positions.
var float initialShortStop = na  // Set at entry: high of the rebound candle.
var float trailStopShort   = na  // Updated trailing stop for short.

// ===== DYNAMIC LOT SIZE =====
// If current profit (strategy.equity - 50000) exceeds 4000, lot size becomes 3; otherwise, 2.
lotSize = (strategy.equity - 50000 > 4000) ? 3 : 2

// ===== ENTRY LOGIC (EXECUTED ON CONFIRMED BARS) =====
if barstate.isconfirmed and inSession and inDateRange and longCondition and strategy.position_size <= 0
    initialLongStop := low
    trailStopLong   := initialLongStop
    if strategy.position_size < 0
        strategy.close("Short", comment="Close Short before Long")
    // Submit a market order entry (no offset).
    strategy.entry("Long", strategy.long, qty=lotSize, comment="Enter Long")

if barstate.isconfirmed and inSession and inDateRange and shortCondition and strategy.position_size >= 0
    initialShortStop := high
    trailStopShort   := initialShortStop
    if strategy.position_size > 0
        strategy.close("Long", comment="Close Long before Short")
    // Submit a market order entry (no offset).
    strategy.entry("Short", strategy.short, qty=lotSize, comment="Enter Short")

// ===== TRAILING STOP LOGIC & EXIT ORDERS (ON CLOSED BARS) =====

if barstate.isconfirmed and strategy.position_size > 0
    // For Long Positions:
    floatingProfitLong = (close - strategy.position_avg_price) / syminfo.mintick
    newTrailLong = trailStopLong  // Default: no change.
    if floatingProfitLong >= 20 and floatingProfitLong < 30
        newTrailLong := initialLongStop + 5 * syminfo.mintick
    else if floatingProfitLong >= 31 and floatingProfitLong < 40
        newTrailLong := initialLongStop + 10 * syminfo.mintick
    else if floatingProfitLong >= 41 and floatingProfitLong < 50
        newTrailLong := initialLongStop + 15 * syminfo.mintick
    // Update trailing stop only if the new value is more favorable.
    trailStopLong := math.max(trailStopLong, newTrailLong)

    longRisk = strategy.position_avg_price - trailStopLong
    tpLong   = strategy.position_avg_price + 2.5 * longRisk
    strategy.exit("Exit Long", from_entry="Long", stop=trailStopLong, limit=tpLong)

if barstate.isconfirmed and strategy.position_size < 0
    // For Short Positions:
    floatingProfitShort = (strategy.position_avg_price - close) / syminfo.mintick
    newTrailShort = trailStopShort  // Default: no change.
    if floatingProfitShort >= 20 and floatingProfitShort < 30
        newTrailShort := initialShortStop - 5 * syminfo.mintick
    else if floatingProfitShort >= 31 and floatingProfitShort < 40
        newTrailShort := initialShortStop - 10 * syminfo.mintick
    else if floatingProfitShort >= 41 and floatingProfitShort < 50
        newTrailShort := initialShortStop - 15 * syminfo.mintick
    // Update trailing stop only if the new value is more favorable.
    trailStopShort := math.min(trailStopShort, newTrailShort)

    shortRisk = trailStopShort - strategy.position_avg_price
    tpShort = strategy.position_avg_price - 2.5 * shortRisk
    strategy.exit("Exit Short", from_entry="Short", stop=trailStopShort, limit=tpShort)
Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Position-Size-and-Trailing-Stop-SMA-Rebound-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h
- Adaptive Trading Strategy Based on ADX IndicatorPine Script · Breakout · 1d
- Average Line Breakthrough StrategyPine Script · Breakout · 1d
- BB Breakout StrategyPine Script · Breakout · 1d