Strategy vault / Mean reversion
Dynamic Position Sizing Quant Strategy
The core idea of this strategy is to dynamically adjust the position size of each trade based on account equity. It can automatically increase position size when profitable and decrease position size when losing…
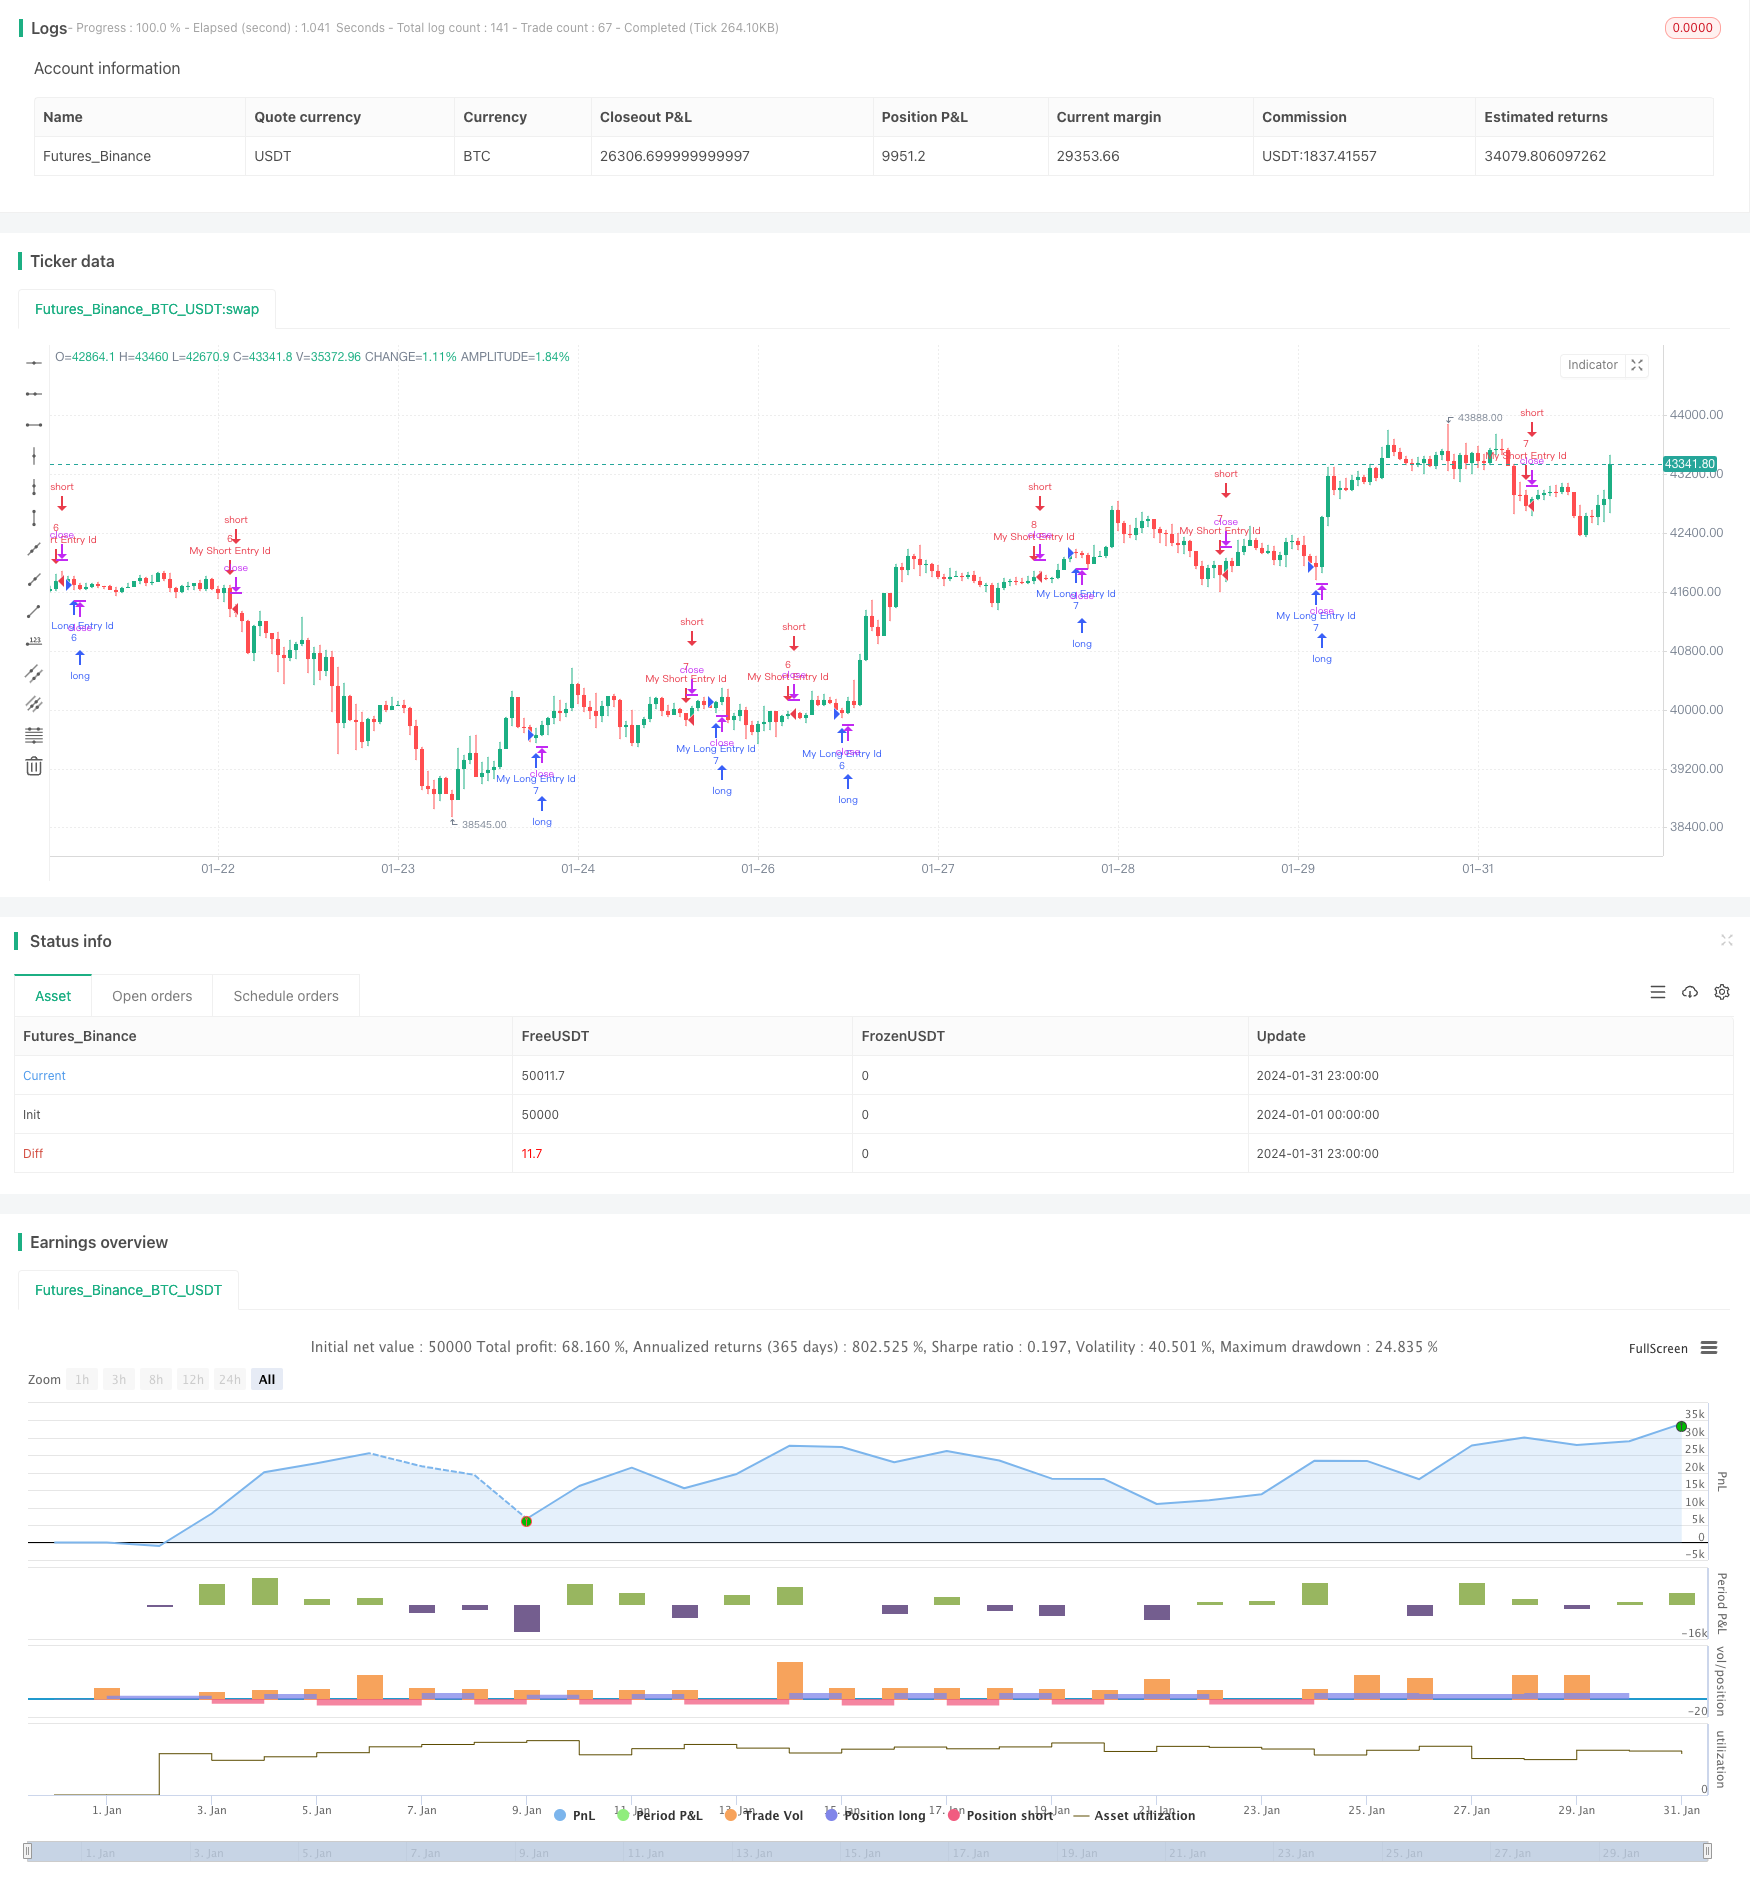
Overview
The core idea of this strategy is to dynamically adjust the position size of each trade based on account equity. It can automatically increase position size when profitable and decrease position size when losing, thereby achieving the automatic leverage effect of compounding.
Strategy Logic
The strategy achieves dynamic position sizing through the following key steps:
- Set parameters like leverage ratio, max position size as constraints
- Calculate benchmark position size by dividing account equity by leverage ratio
- Compare benchmark size with max size setting, take the smaller one as actual size
- Adjust position size to the calculated actual size when opening positions
- Position size will change in real-time with PnL changes and account equity fluctuations
The above steps ensure reasonable position sizing, avoid over-leverage risks, while linking size to equity to achieve auto-compounding as profits increase.
Advantages
The strategy has the following advantages:
- Achieves dynamic position sizing without manual intervention
- Links position size to equity to achieve compounding effect automatically
- Sets leverage and max size as risk limits
- Simple and clear logic, easy to understand and customize
- Easy to incorporate into other strategies, highly extensible
Risks
There are also some risks:
- Magnified losses when position size increases, risk of missing reversals
- Frequent adjustments in extreme market conditions due to real-time linkage to equity
- Inappropriate max size setting can lead to over-leverage
- Excessive leverage multiplying risks
Risks can be mitigated through prudent parameter settings, capital buffering etc.
Enhancement Opportunities
The strategy can be enhanced in the following ways:
- Add slippage to smooth adjustments
- Optimize position sizing formula by incorporating other factors
- Statically lock sizes in specific market conditions
- Set minimum step size for adjustments to avoid excessive changes
- Add conditional rules to prevent unnecessary adjustments
The above enhancements can make the strategy behavior more stable and controllable, avoiding sensitivity and frequent position size changes.
Conclusion
The strategy achieves equity-based dynamic position sizing to automatically magnify profits. It sets leverage and max size as risk controls, with simple and clear logic for ease of understanding and customization. We also analyzed its pros and cons and risks, along with some optimization suggestions. Overall, it provides a flexible and practical approach to achieve automated compound growth in trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10000 | leverage |
| v_input_2 | 25 | max position size |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of Tendies Heist LLC, 2021
//@version=4
strategy("Tendies Heist Auto Compounding Example", overlay=true)


leverage = input(10000)

maxps = input(25, "max position size")
strategy.risk.max_position_size(maxps)

balance = max(1,floor(strategy.equity / leverage))

o        = 1
ps       = true
size     = 0.
balance2 = size[1] < balance
balance3 = size[1] > balance
l        = balance3
w        = balance2

if ps
    size := w ? size[1]+o : l ? size[1]-o : nz(size[1],o)
if size > maxps
    size := maxps

longCondition = crossover(sma(close, 14), sma(close, 28))
if (longCondition)
    strategy.entry("My Long Entry Id", strategy.long,qty=size)

shortCondition = crossunder(sma(close, 14), sma(close, 28))
if (shortCondition)
    strategy.entry("My Short Entry Id", strategy.short,qty=size)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Position-Sizing-Quant-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 3 10 Oscillator Profile Flagging StrategyPine Script · Mean reversion · 1d
- A Trend Reversal Strategy Based on Moving Averages Price Patterns and VolumePine Script · Mean reversion · 1d
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d