Strategy vault / Machine learning
Dynamic Price Swing Oscillator Strategy
The Dynamic Price Swing Oscillator is a strategy for identifying price trends. It combines moving averages, price channels and Fibonacci retracements to implement dynamic entry and exit. The advantage of this…
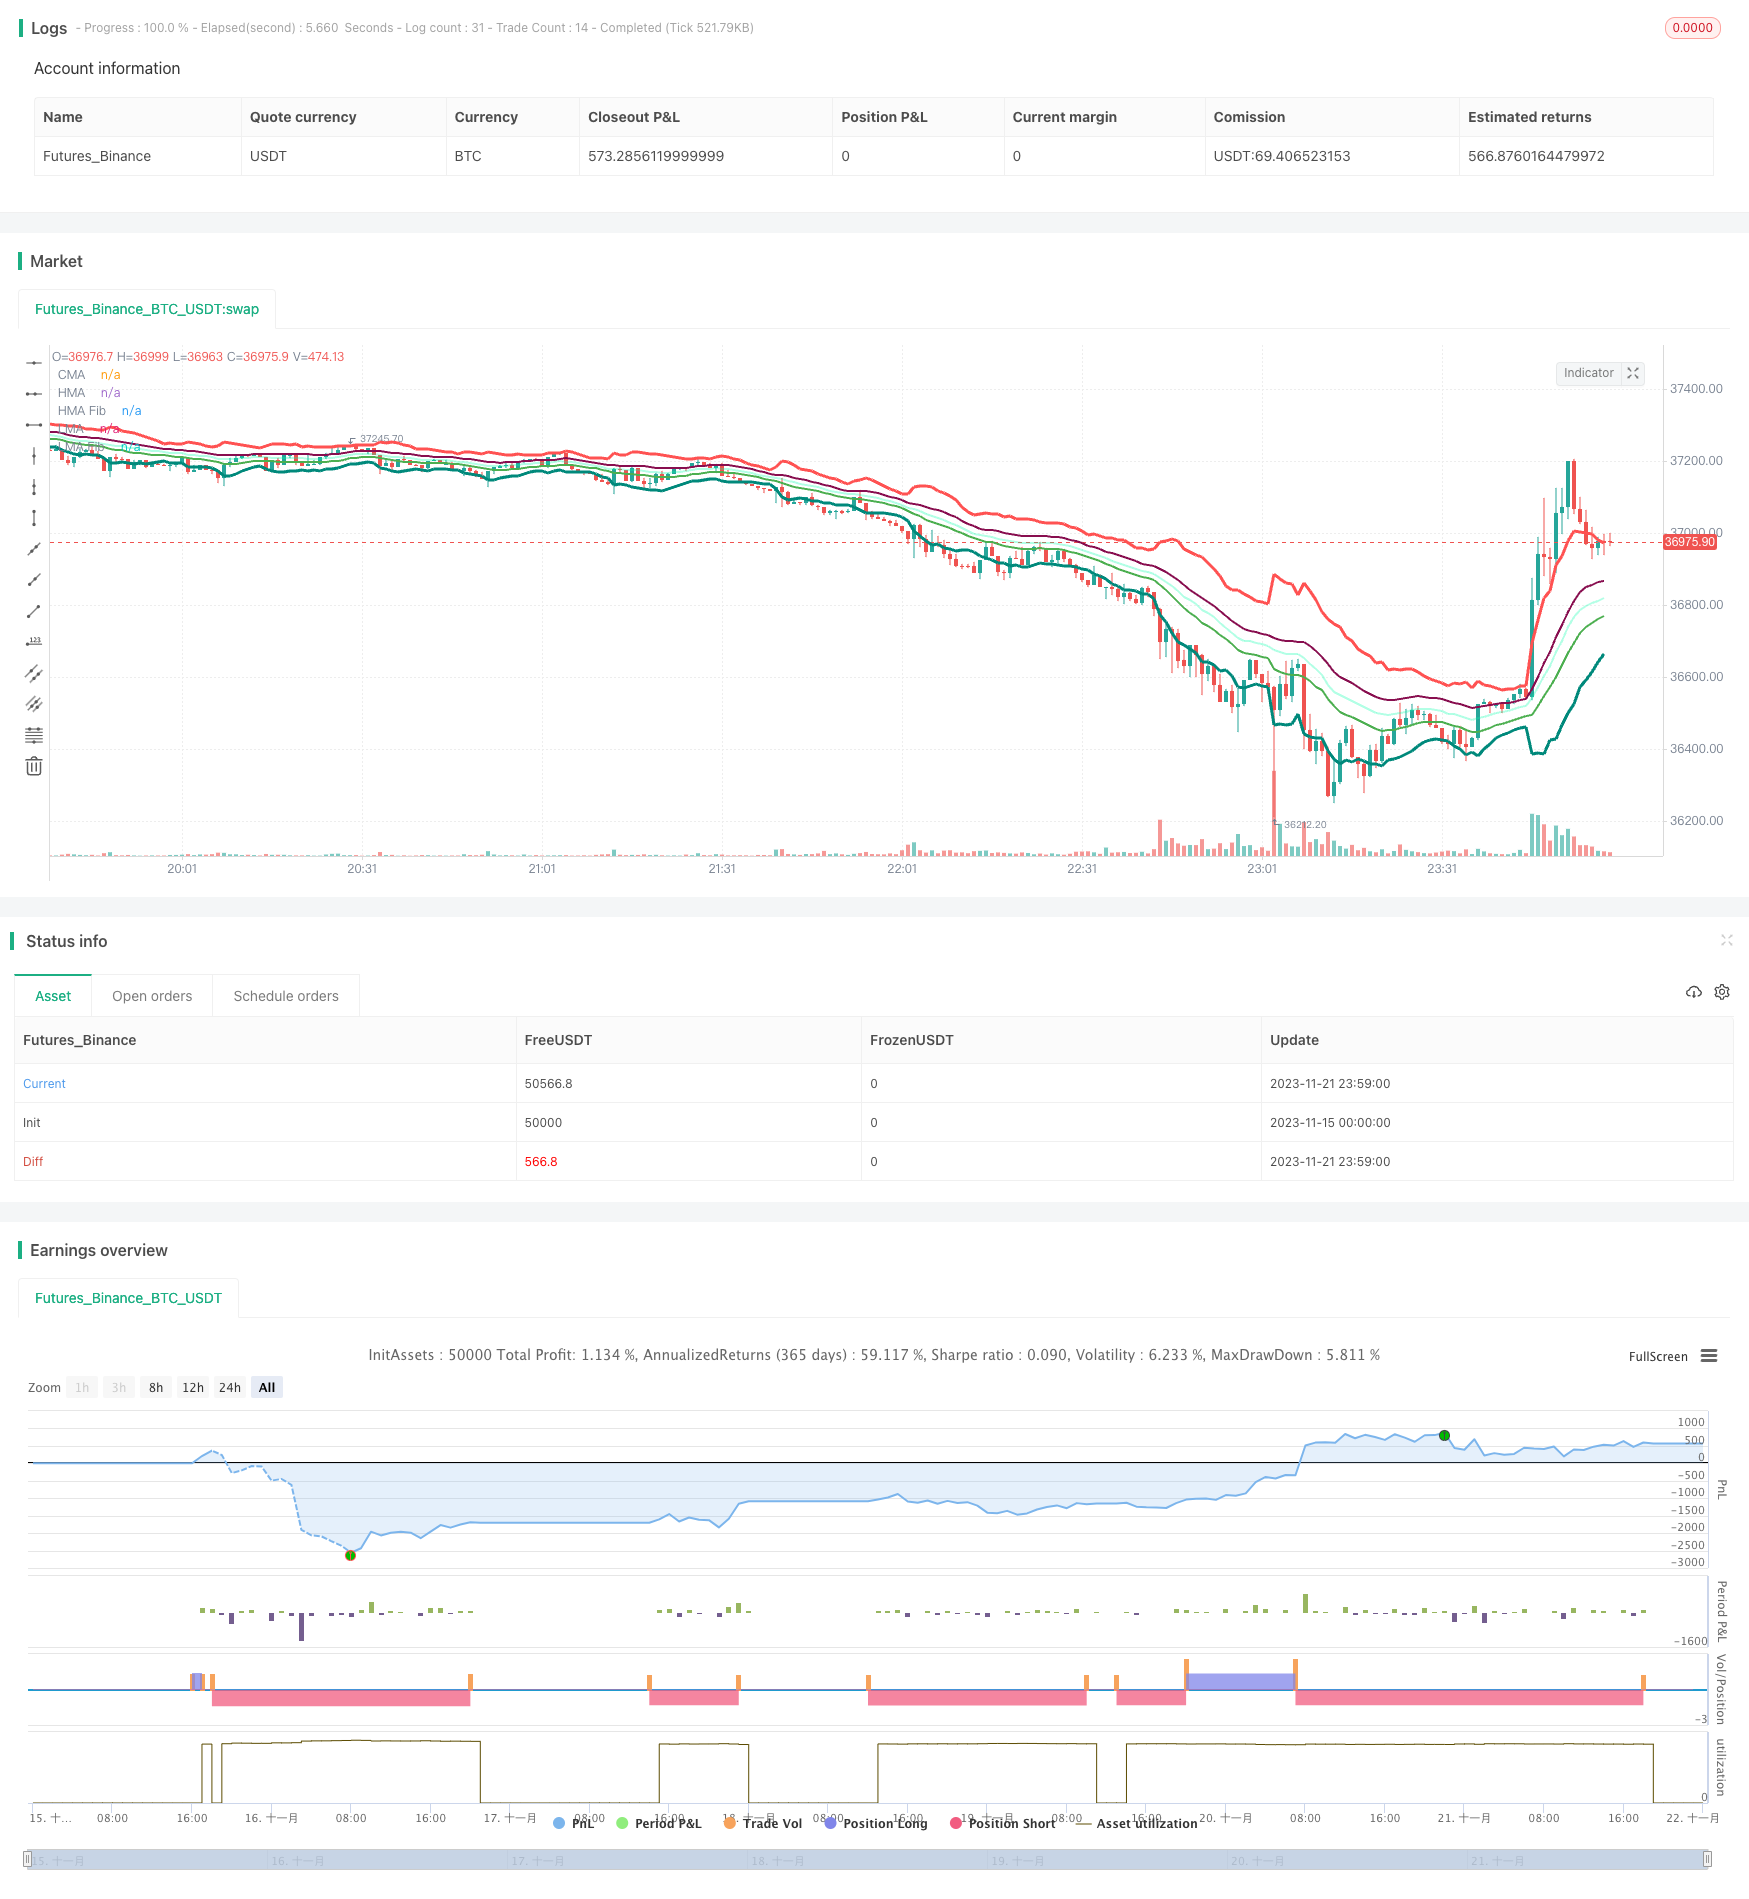
Overview
The Dynamic Price Swing Oscillator is a strategy for identifying price trends. It combines moving averages, price channels and Fibonacci retracements to implement dynamic entry and exit. The advantage of this strategy is that it can identify changes in price trends for flexible operation.
Principles
The strategy is mainly built on the following principles:
Use fast EMA and slow EMA to determine the direction of the price trend to prevent trading against the trend
Use price upper and lower channel limits to determine breakout signals, go short when the price breaks through the upper limit channel, and go long when it breaks through the lower limit channel
Use moving average crossovers as judgment signals, go long on golden crosses, and go short on death crosses
Use Fibonacci retracement lines as judgment signals, go short when the price breaks through the Fibonacci upper limit line, and go long when it breaks through the lower limit line
After determining based on these indicators to enter the market, stop loss and take profit exit mechanisms are set.
Advantage Analysis
The biggest advantage of this strategy is that it combines multiple indicators to identify changes in price trends. The main advantages are:
Using fast and slow EMAs to determine the major trend prevents trading against the trend and can reduce losses
Price channel judgments can capture price breakout opportunities with greater profit potential
Moving average crossover judgments are simple and practical, easy to implement
Fibonacci retracements add another way of judging to make the strategy more three-dimensional
Risk Analysis
Some risks of this strategy need to be noted:
Improper parameter settings for fast and slow EMAs can lead to misjudgments
Improper timing of breaking through the upper and lower limits of the price channel may lead to loss orders
The choice of moving average crosses also needs to be prudent
Improper width settings of the Fibonacci retracement bands will also affect the judgment effect
These risks can be reduced through parameter optimization.
Optimization Directions
There are some directions that can be optimized for this strategy:
Test and optimize parameters such as EMA cycle, channel width, and moving average period
Add judgment rules for other technical indicators such as RSI and Bollinger Bands
Combine trading volume energy indicators such as OBV to determine the reliability of breakouts
Use machine learning and other technologies to automatically find the optimal parameters
Conclusion
The Dynamic Price Swing Oscillator is a highly flexible and adaptable strategy. It can dynamically adapt to price changes and trade after determining breakouts through multiple indicator judgments. Although there are some risks, they can be reduced by continuous optimization to improve the stability and profitability of the strategy. The strategy is worth in-depth research.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | timestamp(22 June 2021 00:00 -0500) | Start Time |
| v_input_2 | timestamp(31 December 2021 00:00 -0600) | End Time |
| v_input_3 | true | Long/Short for Mixed Market, Long for Bull, Short for Bear |
| v_input_4 | 0 | Trade Types: Long/Short | Long Only | Short Only |
| v_input_5 | 10 | Stop Loss % |
| v_input_6 | 20 | Target Profit % |
| v_input_7 | 2 | Stop Trading After This Many Losing Days |
| v_input_8 | 10 | Maximum % of Equity Lost to Halt Trading |
| v_input_9 | true | Number of bars to look back on to calculate price swings. |
| v_input_10 | 5 | Max Lookback Period |
| v_input_11_high | 0 | High Source: high | close | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_12_low | 0 | Low Source: low | high | close | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_13 | true | Trend uses Fast and Slow EMA to prevent going the wrong direction |
| v_input_14 | 14 | RSI Length |
| v_input_15 | 12 | EMA Fast Length |
| v_input_16 | 26 | EMA Slow Length |
| v_input_17 | true | Use Average Price Channel Only |
| v_input_18 | false | Use Price Moving Average Only |
| v_input_19 | false | Use Price Fibonacci Average Only |
Source Pine Script
/*backtest
start: 2023-11-15 00:00:00
end: 2023-11-22 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
//@version=4

// ██████╗██████╗ ███████╗ █████╗ ████████╗███████╗██████╗     ██████╗ ██╗   ██╗
//██╔════╝██╔══██╗██╔════╝██╔══██╗╚══██╔══╝██╔════╝██╔══██╗    ██╔══██╗╚██╗ ██╔╝
//██║     ██████╔╝█████╗  ███████║   ██║   █████╗  ██║  ██║    ██████╔╝ ╚████╔╝
//██║     ██╔══██╗██╔══╝  ██╔══██║   ██║   ██╔══╝  ██║  ██║    ██╔══██╗  ╚██╔╝
//╚██████╗██║  ██║███████╗██║  ██║   ██║   ███████╗██████╔╝    ██████╔╝   ██║
// ╚═════╝╚═╝  ╚═╝╚══════╝╚═╝  ╚═╝   ╚═╝   ╚══════╝╚═════╝     ╚═════╝    ╚═╝

//███████╗ ██████╗ ██╗     ██╗   ██╗████████╗██╗ ██████╗ ███╗   ██╗███████╗ ██╗ █████╗ ███████╗ █████╗
//██╔════╝██╔═══██╗██║     ██║   ██║╚══██╔══╝██║██╔═══██╗████╗  ██║██╔════╝███║██╔══██╗╚════██║██╔══██╗
//███████╗██║   ██║██║     ██║   ██║   ██║   ██║██║   ██║██╔██╗ ██║███████╗╚██║╚██████║    ██╔╝╚█████╔╝
//╚════██║██║   ██║██║     ██║   ██║   ██║   ██║██║   ██║██║╚██╗██║╚════██║ ██║ ╚═══██║   ██╔╝ ██╔══██╗
//███████║╚██████╔╝███████╗╚██████╔╝   ██║   ██║╚██████╔╝██║ ╚████║███████║ ██║ █████╔╝   ██║  ╚█████╔╝
//╚══════╝ ╚═════╝ ╚══════╝ ╚═════╝    ╚═╝   ╚═╝ ╚═════╝ ╚═╝  ╚═══╝╚══════╝ ╚═╝ ╚════╝    ╚═╝   ╚════╝


strategy(shorttitle='DPS',title='Dynamic Price Swing', overlay=true, scale=scale.left, initial_capital = 1000, process_orders_on_close=true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, commission_type=strategy.commission.percent, commission_value=0.18, calc_on_every_tick=true)


// -----------------  Strategy Inputs -------------------------------------------------------------
//Backtest dates with auto finish date of today
start = input(defval = timestamp("22 June 2021 00:00 -0500"), title = "Start Time")
finish = input(defval = timestamp("31 December 2021 00:00 -0600"), title = "End Time")
window()  => true       // create function "within window of time"

// Strategy Selection - Long, Short, or Both
stratinfo = input(true, "Long/Short for Mixed Market, Long for Bull, Short for Bear")
strat = input(title="Trade Types", defval="Long/Short", options=["Long Only", "Long/Short", "Short Only"])
strat_val = strat == "Long Only" ? 1 : strat == "Long/Short" ? 0 : -1

// Risk Management Inputs
sl= input(10.0, "Stop Loss %", minval = 0, maxval = 100, step = 0.01)
stoploss = sl/100
tp = input(20.0, "Target Profit %", minval = 0, maxval = 100, step = 0.01)
TargetProfit = tp/100
ld = input(2, "Stop Trading After This Many Losing Days", type=input.integer, minval=0, maxval=100, step=1)
// strategy.risk.max_cons_loss_days(count=ld)
ml = input(10, "Maximum % of Equity Lost to Halt Trading", type=input.integer, minval=1, maxval=100, step=1)
// strategy.risk.max_drawdown(value=ml, type=strategy.percent_of_equity)

// Price Movement Inputs
PriceInfo = input(true, "Number of bars to look back on to calculate price swings.")
lkbk = input(5,"Max Lookback Period")
high_source = input(high,"High Source")
low_source= input(low,"Low Source")

// Trend Inputs
TrendInfo = input(true, "Trend uses Fast and Slow EMA to prevent going the wrong direction")
length = input(14, "RSI Length", minval=1)
fastLength = input(12, minval=1, title="EMA Fast Length")
slowLength = input(26, minval=1, title="EMA Slow Length")

// Trigger Selection
usePrice = input(true, "Use Average Price Channel Only")
useMA = input(false, "Use Price Moving Average Only")
useFib = input(false, "Use Price Fibonacci Average Only")


// Trend Direction Calculation
rsi_ema = ema(rsi(close, length), length)
emaA = ema(rsi_ema, fastLength)
emaFast = 2 * emaA - ema(emaA, fastLength)
emaB = ema(rsi_ema, slowLength)
emaSlow = 2 * emaB - ema(emaB, slowLength)


bullishRule =emaFast > emaSlow and rsi_ema >=rsi_ema[1]
bearishRule =emaFast < emaSlow and rsi_ema <= rsi_ema[1]


// Price Channel

lasthigh = highest(high_source, lkbk)
lastlow = lowest(low_source, lkbk)


// Fibonacci and Moving Average
MA1 = sma(close,5),HA1 = sma(high,5),LA1 = sma(low,5),
MA2 = sma(close,8),HA2 = sma(high,8),LA2 = sma(low,8),
MA3 = sma(close,13),HA3 = sma(high,13),LA3 = sma(low,13),
MA4 = sma(close,21),HA4 = sma(high,21),LA4 = sma(low,21),
MA5 = sma(close,34),HA5 = sma(high,34),LA5 = sma(low,34),
MA6 = sma(close,55),HA6 = sma(high,55),LA6 = sma(low,55),
MA7 = sma(close,89),HA7 = sma(high,89),LA7 = sma(low,89),

CMA = (MA1+MA2+MA3+MA4+MA5+MA6+MA7)/7,
HMA = (HA1+HA2+HA3+HA4+HA5+HA6+HA7)/7,
HMA2 = CMA + (atr(lkbk)*1.618)

LMA = (LA1+LA2+LA3+LA4+LA5+LA6+LA7)/7,
LMA2 = CMA - (atr(lkbk)*1.618)


plot(CMA, title="CMA", color=color.new(#00ffaa, 70), linewidth=2)
plot(HMA, title="HMA", color=color.maroon, linewidth=2)
plot(HMA2, title="HMA Fib", color=color.red, linewidth=3)
plot(LMA, title="LMA", color=color.green, linewidth=2)
plot(LMA2, title="LMA Fib", color=color.teal, linewidth=3)


// -------------------------------- Entry and Exit Logic ------------------------------------

// Entry Logic

Channel_Sell = close >= lasthigh[1] and bearishRule and window()
Channel_Buy =  close <= lastlow[1] and bullishRule and window()

MA_Sell = high>HMA and window()
MA_Buy = low<LMA and window()

Fib_Sell = high>HMA2 and window()
Fib_Buy = low<LMA2 and window()

qty = strategy.equity/close


// Strategy Entry and Exit with built in Risk Management
if(strategy.opentrades==0 and strat_val>-1)
    GoLong = usePrice ? Channel_Buy : useMA ? MA_Buy : useFib ? Fib_Buy : false
    if (GoLong)
        strategy.entry("LONG", strategy.long, qty)

if(strategy.opentrades==0 and strat_val<1)
    GoShort = usePrice ? Channel_Sell : useMA ? MA_Sell : useFib ? Fib_Sell : false
    if (GoShort)
        strategy.entry("SHORT", strategy.short, qty)


longStopPrice  = strategy.position_avg_price * (1 - stoploss)
longTakePrice  = strategy.position_avg_price * (1 + TargetProfit)
shortStopPrice = strategy.position_avg_price * (1 + stoploss)
shortTakePrice = strategy.position_avg_price * (1 - TargetProfit)

if (strategy.position_size > 0)
    strategy.exit(id="Exit Long", from_entry = "LONG", stop = longStopPrice, limit = longTakePrice)

if (strategy.position_size < 0)
    strategy.exit(id="Exit Short", from_entry = "SHORT", stop = shortStopPrice, limit = shortTakePrice)

CloseShort= usePrice ? Channel_Buy : useMA ? MA_Buy : useFib ? Fib_Buy : false
CloseLong = usePrice ? Channel_Sell : useMA ? MA_Sell : useFib ? Fib_Sell : false

if(CloseLong and strategy.position_size > 0)
    strategy.close("LONG")


if(CloseShort and strategy.position_size < 0)
    strategy.close("SHORT")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Price-Swing-Oscillator-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX EFI 50 Moving Average Channel Pullback StrategyPine Script · Machine learning · 1h
- Bollinger Bands ATR Trailing Stop StrategyPine Script · Machine learning · 1m
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- Dual Moving Average Matching Strategy Based on Bollinger BandsPine Script · Machine learning · 1h
- EMA and RSI Quantitative Trading StrategyPine Script · Machine learning · 1h
- High Frequency Hybrid Technical Analysis Quantitative StrategyPine Script · Machine learning · 15m