Strategy vault / Trend following
Dynamic Re entry Buy only Strategy
This strategy is a buy-only trading system that generates buy signals based on moving average crossovers and the Weekly Commodity Channel Index (CCI) or Weekly Average Directional Index (ADX). It produces buy signals…
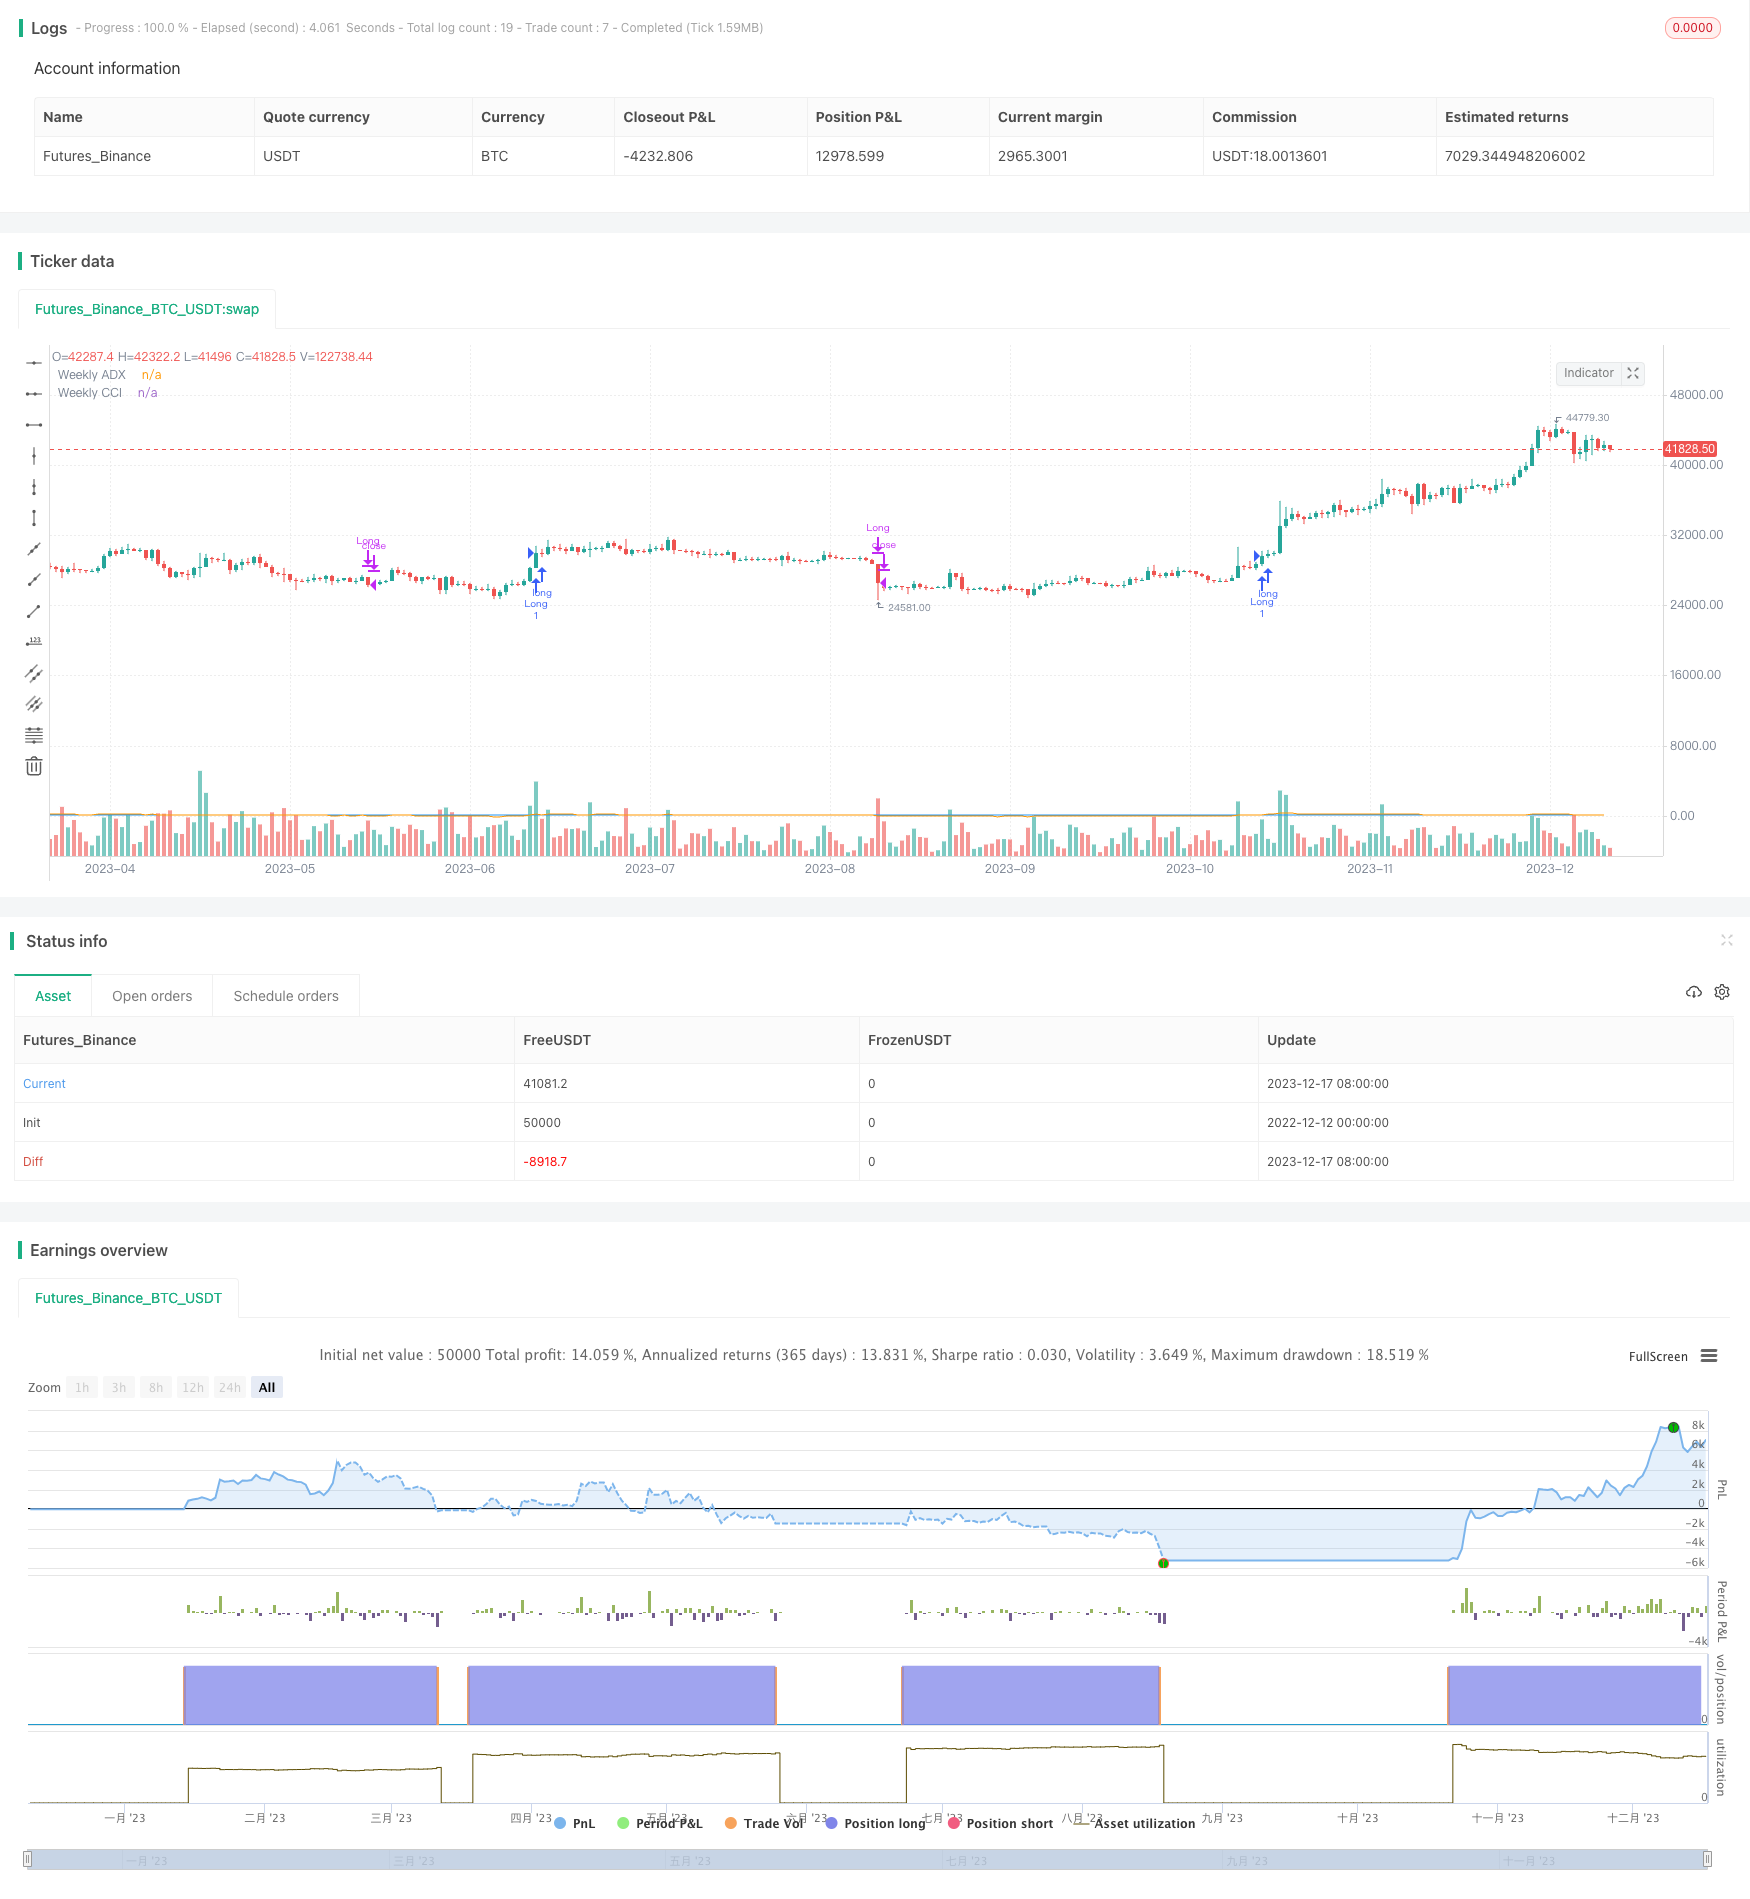
Overview
This strategy is a buy-only trading system that generates buy signals based on moving average crossovers and the Weekly Commodity Channel Index (CCI) or Weekly Average Directional Index (ADX). It produces buy signals when the fast moving average crosses above the slow moving average and when the Weekly CCI and/or Weekly ADX meet specified conditions.
The strategy also allows for dynamic re-entry, which means it can open new long positions if the price goes above the three moving averages after an exit. However, the strategy will exit the long position if the price closes below the third moving average.
Strategy Principle
The script defines the conditions for generating buy signals. It checks two conditions for a valid buy signal:
- The fast moving average crosses above the slow moving average
- The user can choose to filter trades using Weekly CCI or Weekly ADX
Dynamic Re-entry: If there is no active long position and the price is above all three moving averages, a new long position is opened.
Exit Condition: If the closing price drops below the third moving average, the script closes the long position.
Advantage Analysis
The advantages of this strategy include:
- Using multiple technical indicators to filter signals reduces false signals
- The dynamic re-entry mechanism maximizes the capture of trends
- Being long-only avoids the risks of shorting
Risk Analysis
The risks of this strategy include:
- There is some risk of whipsaws
- Long holding times could be too long, requiring stops
- Poor parameter settings may cause too frequent trading
Solutions:
- Use better parameter combinations and indicator combinations to filter
- Set reasonable stop losses
- Adjust parameters to ensure stability
Optimization Directions
This strategy can be optimized by:
- Testing more technical indicator combinations to find better entry timing
- Optimizing parameters to find the best parameter combinations
- Adding stop loss mechanisms to control single loss
- Adding position sizing to increase/decrease positions based on market conditions
Summary
This dynamic re-entry buy-only strategy integrates multiple technical indicators to determine entry timing and adopts a dynamic re-entry design to track trends in real-time. Being long-only avoids shorting risks. Through parameter optimization, stop losses, and position sizing, this strategy can be implemented in live trading to control risk while capturing excess returns.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 20 | Fast Moving Average Length |
| v_input_2 | 30 | Slow Moving Average Length |
| v_input_3 | 100 | Third Moving Average Length |
| v_input_4 | 14 | CCI Period for Weekly CCI |
| v_input_5 | true | Use CCI for Entry |
| v_input_6 | true | Use ADX for Entry |
| v_input_7 | 14 | ADX Length |
| v_input_8 | 25 | ADX Threshold |
Source Pine Script
/*backtest
start: 2022-12-12 00:00:00
end: 2023-12-18 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Buy Only Strategy with Dynamic Re-Entry and Exit", overlay=true)

// Input Parameters
fast_length = input(20, title="Fast Moving Average Length")
slow_length = input(30, title="Slow Moving Average Length")
third_ma_length = input(100, title="Third Moving Average Length")
cci_period = input(14, title="CCI Period for Weekly CCI")
use_cci = input(true, title="Use CCI for Entry")
use_adx = input(true, title="Use ADX for Entry")
adx_length = input(14, title="ADX Length")
adx_threshold = input(25, title="ADX Threshold")

// Calculate Moving Averages
fast_ma = ta.sma(close, fast_length)
slow_ma = ta.sma(close, slow_length)
third_ma = ta.sma(close, third_ma_length)

// Weekly Commodity Channel Index (CCI) with user-defined period
weekly_cci = request.security(syminfo.tickerid, "W", ta.cci(close,  cci_period))

// Weekly Average Directional Index (ADX)
dirmov = hlc3
plus = ta.change(dirmov) > 0 ? ta.change(dirmov) : 0
minus = ta.change(dirmov) < 0 ? -ta.change(dirmov) : 0
trur = ta.rma(ta.tr, adx_length)
plusDI = ta.rma(plus, adx_length) / trur * 100
minusDI = ta.rma(minus, adx_length) / trur * 100
sum = plusDI + minusDI
DX = sum == 0 ? 0 : math.abs(plusDI - minusDI) / sum * 100
ADX = ta.rma(DX, adx_length)

// Entry Conditions (Buy Only and Weekly CCI > 100 and/or Weekly ADX > 25)
cci_condition = use_cci ? (weekly_cci > 100) : false
adx_condition = use_adx ? (ADX > adx_threshold) : false
long_condition = ta.crossover(fast_ma, slow_ma) and (cci_condition or adx_condition)

// Exit Condition and Dynamic Re-Entry
exit_condition = close < third_ma
re_entry_condition = close > fast_ma and close > slow_ma and close > third_ma and weekly_cci > 100

// Entry and Exit Signals
strategy.entry("Long", strategy.long, when=long_condition)
strategy.close("Long", when=exit_condition)

// Dynamic Re-Entry and Exit
if strategy.position_size == 0 and re_entry_condition
    strategy.entry("Long", strategy.long)

if strategy.position_size > 0 and close < third_ma
    strategy.close("Long")

// Plot Weekly CCI and ADX for reference
plot(weekly_cci, title="Weekly CCI", color=color.orange)
plot(ADX, title="Weekly ADX", color=color.blue)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Re-entry-Buy-only-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- Trend Following Strategy Based on Moving Average Crossover 430022Pine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Bollinger Band Trend ChaserPine Script · Trend following · 1d
- Dynamic Multi Indicator Trend Recognition Strategy with Triple Sync AnalysisPine Script · Trend following · 1d