Strategy vault / Trend following
Dynamic Risk Controlled Supertrend Engulfing Pattern Strategy
This is an advanced trading strategy that combines the Supertrend indicator with engulfing candlestick patterns. The strategy identifies engulfing patterns in the market and confirms them with the Supertrend…
Overview
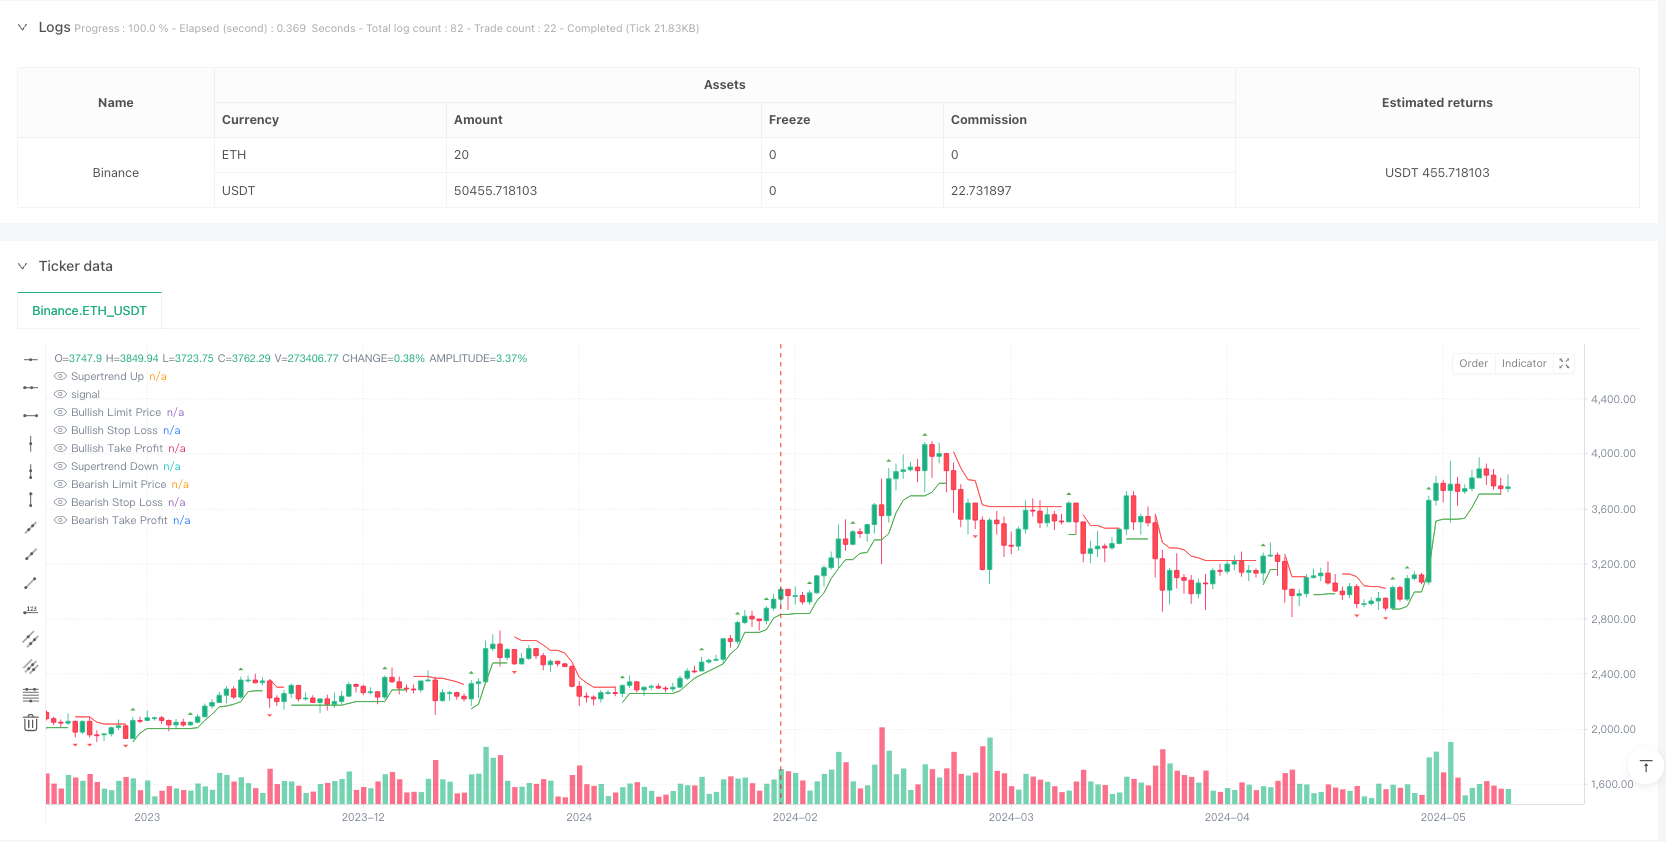
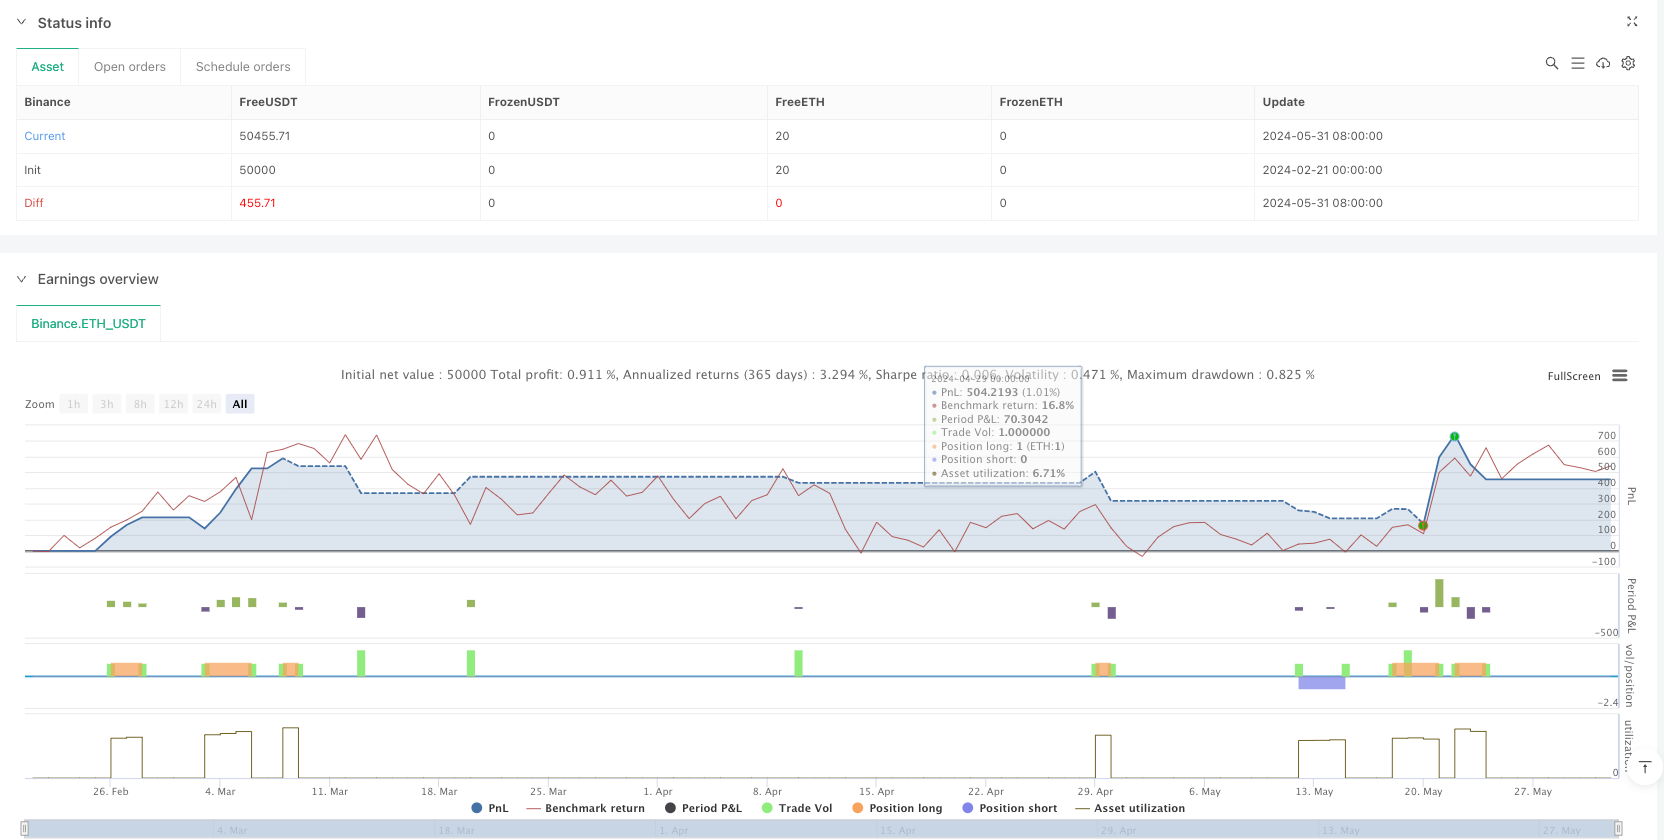
This is an advanced trading strategy that combines the Supertrend indicator with engulfing candlestick patterns. The strategy identifies engulfing patterns in the market and confirms them with the Supertrend indicator's trend direction to achieve precise trade signal filtering. It also incorporates dynamic stop-loss and take-profit settings to effectively control risk while ensuring profit potential.
Strategy Principles
The strategy is based on the following core principles:
- Uses ATR (Average True Range) to calculate the Supertrend indicator for determining overall market trend.
- Filters effective engulfing patterns through Boring Candle Threshold and Engulfing Candle Threshold settings.
- Only enters trades when Supertrend trend direction aligns with engulfing pattern direction.
- Employs dynamic stop-loss and take-profit levels calculated proportionally from entry price.
- Implements position management ensuring only one trade direction at a time.
Strategy Advantages
- Strict signal quality control through dual confirmation (trend + pattern).
- Introduction of boring candle and engulfing thresholds effectively filters false signals.
- ATR-based dynamic Supertrend calculation provides good market adaptability.
- Comprehensive stop-loss and profit management mechanism.
- Excellent visualization of trade signals, stop-loss levels, and profit targets.
Strategy Risks
- May generate frequent false breakout signals in ranging markets.
- Fixed stop-loss and take-profit settings might not suit all market conditions.
- Potential for significant drawdowns during trend reversals.
- Sensitivity to parameter settings may lead to poor strategy performance.
- Slippage risks in markets with lower liquidity.
Optimization Directions
- Consider incorporating volume indicators for signal confirmation.
- Implement dynamic ATR multiplier adjustment mechanism.
- Develop dynamic stop-loss and take-profit ratios based on market volatility.
- Add time filters to avoid trading during unsuitable periods.
- Consider adding trend strength filters to improve trade quality.
Summary
This is a well-designed strategy with clear logic that achieves good signal quality control through combined technical indicators and pattern analysis. The strategy features comprehensive risk management mechanisms and excellent visualization, making it suitable for live testing and optimization. Traders should pay attention to parameter optimization and market environment selection during practical application.
Source Pine Script
/*backtest
start: 2024-02-21 00:00:00
end: 2024-06-01 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Binance","currency":"ETH_USDT"}]
*/

//@version=5
strategy('Strategy Engulfing', overlay=true)

// Inputs
Periods = input(title='ATR Period', defval=5)
src = input(hl2, title='Source')
Multiplier = input.float(title='ATR Multiplier', step=0.1, defval=1.0)
highlighting = input(title='Highlighter On/Off?', defval=true)
boringThreshold = input.int(5, title='Boring Candle Threshold (%)', minval=1, maxval=100, step=1)
engulfingThreshold = input.int(50, title='Engulfing Candle Threshold (%)', minval=1, maxval=100, step=1)
OpenPosisi = input.int(2000, title='OpenPosisi (Pips)', minval=-25000)
stoploss = input.int(10000, title='Stop Loss (Pips)', minval=-25000)
takeprofit = input.int(20000, title='Take Profit (Pips)', minval=-25000)

// ATR Calculation
atr = ta.atr(Periods)

// Supertrend Calculation
up = src - Multiplier * atr
up := close[1] > nz(up[1]) ? math.max(up, nz(up[1])) : up
dn = src + Multiplier * atr
dn := close[1] < nz(dn[1]) ? math.min(dn, nz(dn[1])) : dn
trend = 1
trend := nz(trend[1], trend)
trend := trend == -1 and close > dn[1] ? 1 : trend == 1 and close < up[1] ? -1 : trend

// Plotting Supertrend
plot(trend == 1 ? up : na, color=color.new(color.green, 0), linewidth=1, style=plot.style_linebr, title='Supertrend Up')
plot(trend == -1 ? dn : na, color=color.new(color.red, 0), linewidth=1, style=plot.style_linebr, title='Supertrend Down')

// Engulfing Candlestick
isBoringCandle = math.abs(open[1] - close[1]) <= (high[1] - low[1]) * boringThreshold / 100
isEngulfingCandle = math.abs(open - close) * 100 / math.abs(high - low) <= engulfingThreshold

bullEngulfing = strategy.opentrades == 0 and trend == 1 and close[1] < open[1] and close > open[1] and not isBoringCandle and not isEngulfingCandle
bearEngulfing = strategy.opentrades == 0 and trend == -1 and close[1] > open[1] and close < open[1] and not isBoringCandle and not isEngulfingCandle

// Calculate Limit Price
limitbull = bullEngulfing ? close + OpenPosisi * syminfo.mintick : na
limitbear = bearEngulfing ? close - OpenPosisi * syminfo.mintick : na

// Calculate Stop Loss
bullishStopLoss = bullEngulfing ? limitbull - stoploss * syminfo.mintick : na
bearishStopLoss = bearEngulfing ? limitbear + stoploss * syminfo.mintick : na

// Calculate Take Profit
bullishTakeProfit = bullEngulfing ? limitbull + takeprofit * syminfo.mintick : na
bearishTakeProfit = bearEngulfing ? limitbear - takeprofit * syminfo.mintick : na


// Alerts for Engulfing Candles (Trigger Immediately)
if bullEngulfing
    alert('Bullish Engulfing Candle Formed!')

if bearEngulfing
    alert('Bearish Engulfing Candle Formed!')

// Plot shapes
plotshape(bullEngulfing, style=shape.triangleup, location=location.abovebar, color=color.new(color.green, 0))
plotshape(bearEngulfing, style=shape.triangledown, location=location.belowbar, color=color.new(color.red, 0))


plot(limitbull, title='Bullish Limit Price', color=color.new(color.purple, 0), style=plot.style_linebr, linewidth=1)
plot(limitbear, title='Bearish Limit Price', color=color.new(color.purple, 0), style=plot.style_linebr, linewidth=1)
plot(bullishStopLoss, title='Bullish Stop Loss', color=color.new(color.red, 0), style=plot.style_linebr, linewidth=1)
plot(bearishStopLoss, title='Bearish Stop Loss', color=color.new(color.red, 0), style=plot.style_linebr, linewidth=1)
plot(bullishTakeProfit, title='Bullish Take Profit', color=color.new(color.blue, 0), style=plot.style_linebr, linewidth=1)
plot(bearishTakeProfit, title='Bearish Take Profit', color=color.new(color.blue, 0), style=plot.style_linebr, linewidth=1)

// Label Stop Loss and Take Profit
label.new(bullEngulfing ? bar_index : na, bullishStopLoss, text='SL: ' + str.tostring(bullishStopLoss), color=color.red, textcolor=color.white, style=label.style_label_up, size=size.tiny)
label.new(bearEngulfing ? bar_index : na, bearishStopLoss, text='SL: ' + str.tostring(bearishStopLoss), color=color.red, textcolor=color.white, style=label.style_label_down, size=size.tiny)
label.new(bullEngulfing ? bar_index : na, bullishTakeProfit, text='TP: ' + str.tostring(bullishTakeProfit), color=color.green, textcolor=color.white, style=label.style_label_down, size=size.tiny)
label.new(bearEngulfing ? bar_index : na, bearishTakeProfit, text='TP: ' + str.tostring(bearishTakeProfit), color=color.green, textcolor=color.white, style=label.style_label_up, size=size.tiny)


// Strategy execution
if bullEngulfing
    strategy.entry('BUY', strategy.long, stop=limitbull)
    strategy.exit('TP/SL', from_entry='BUY', limit=bullishTakeProfit, stop=bullishStopLoss)

if bearEngulfing
    strategy.entry('SELL', strategy.short, stop=limitbear)
    strategy.exit('TP/SL', from_entry='SELL', limit=bearishTakeProfit, stop=bearishStopLoss)
Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Risk-Controlled-Supertrend-Engulfing-Pattern-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced Supertrend Indicator Trading Mechanism Optimization StrategyPine Script · Trend following · 1d
- Dynamic Trend Following SuperTrend Triple Enhancement StrategyPine Script · Trend following · 1d
- Heiken Ashi and Super Trend Combination StrategyPine Script · Trend following · 1d
- Multi Indicator Dynamic Trend Following Strategy Based on EMA and SMAPine Script · Trend following · 1d
- Multi Period SuperTrend Dynamic Trading StrategyPine Script · Trend following · 1d
- Precision Trading Strategy and Risk Management System Based on SuperTrend IndicatorPine Script · Trend following · 1d