Dynamic Take Profit Smart Trailing Strategy
This strategy is an intelligent trading system based on price drop signals, combining dynamic take-profit and trailing stop-loss features. The strategy identifies potential buying opportunities by monitoring price…
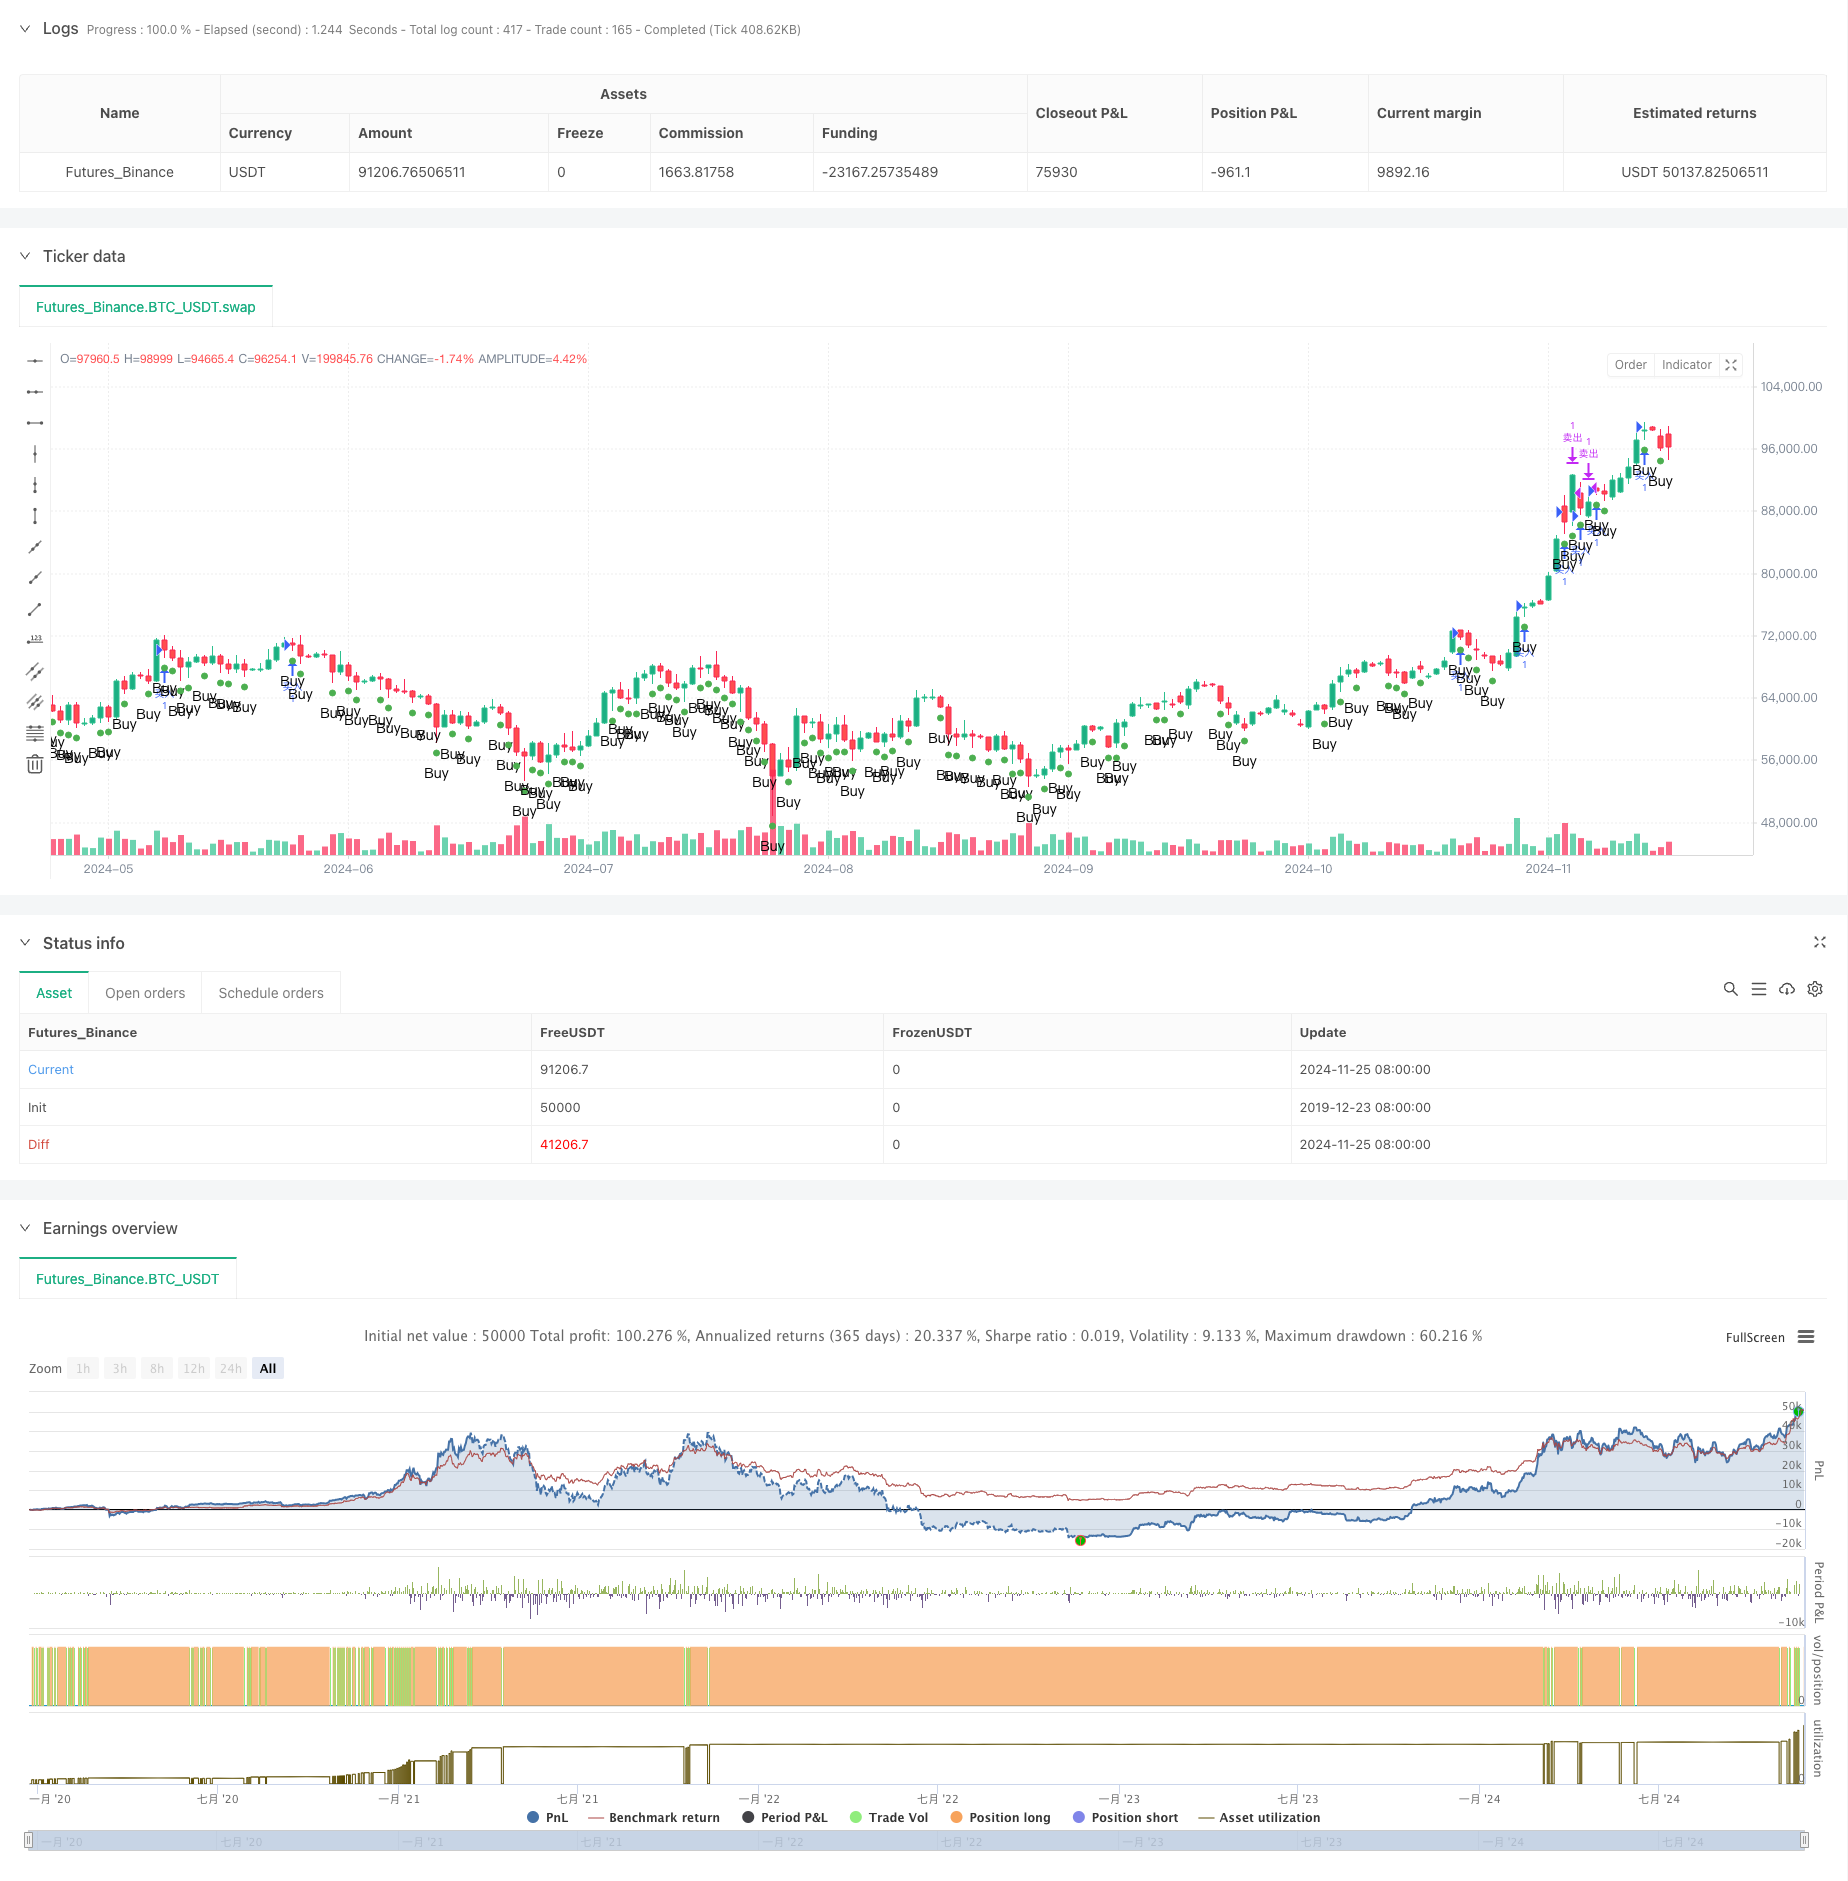
Overview
This strategy is an intelligent trading system based on price drop signals, combining dynamic take-profit and trailing stop-loss features. The strategy identifies potential buying opportunities by monitoring price drops while employing flexible profit-taking schemes and trailing stop mechanisms to protect profits. The core idea is to enter positions during significant price drops and maximize returns through intelligent position management.
Strategy Principles
The strategy operates through three core components: First, it identifies buy signals by setting a price drop percentage threshold (default -0.98%), triggering when a candle's low price falls below the opening price multiplied by (1 + drop percentage). Second, it uses a fixed percentage (default 1.23%) as the target profit for setting take-profit levels. Finally, it incorporates a trailing stop mechanism (default 0.6%) to protect profits during price retracements. The strategy includes visualization components, displaying buy signals through various marker shapes.
Strategy Advantages
- Precise Signal Identification: Accurately identifies potential buying opportunities through precise price drop calculations, avoiding false signals.
- Comprehensive Risk Management: Combines fixed take-profit and trailing stop-loss, ensuring profit potential while effectively controlling risk.
- Flexible Parameters: Main parameters can be adjusted according to market conditions and trading requirements, providing high adaptability.
- Excellent Visualization: Buy signals are clearly visible, facilitating quick judgment and decision-making.
- Clear Execution Logic: Entry and exit conditions are well-defined, eliminating uncertainty from subjective judgment.
Strategy Risks
- False Breakout Risk: Frequent false signals may occur in ranging markets. Consider adding volume indicators for confirmation.
- Stop-Loss Setting Risk: Too tight trailing stops may result in premature exits, while too loose stops might sacrifice profits. Adjustment based on actual volatility is necessary.
- Market Environment Dependency: Strategy performs better in trending markets but may incur losses due to frequent trading in ranging markets.
- Parameter Sensitivity: Strategy effectiveness is sensitive to parameter settings, requiring backtesting to find optimal combinations.
Strategy Optimization Directions
- Signal Filtering: Add volume and volatility indicators as auxiliary conditions to improve signal quality.
- Dynamic Parameter Adjustment: Dynamically adjust take-profit and stop-loss parameters based on market volatility.
- Timeframe Optimization: Incorporate multiple timeframe analysis to enhance signal reliability.
- Position Management: Introduce dynamic position sizing based on signal strength and market conditions.
- Market Environment Assessment: Add market condition evaluation to adapt parameters to different market states.
Summary
This strategy builds a complete trading system by combining price drop signal identification, dynamic take-profit, and trailing stop-loss mechanisms. Its strengths lie in accurate signal identification and comprehensive risk management, though attention must be paid to false breakouts and parameter sensitivity risks. The strategy's stability and profitability can be further enhanced by adding auxiliary indicators and optimizing parameter adjustment mechanisms. It provides a valuable strategic framework suitable for in-depth research and optimization.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-26 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Price Drop Buy Signal Strategy", overlay=true)

// Input Parameters
percentDrop = input.float(defval=-0.98, title="Price Drop Percentage", minval=-100, step=0.01) / 100
plotShapeStyle = input.string("shape_triangle_up", "Shape", options=["shape_xcross", "shape_cross", "shape_triangle_up", "shape_triangle_down", "shape_flag", "shape_circle", "shape_arrow_up", "shape_arrow_down", "shape_label_up", "shape_label_down", "shape_square", "shape_diamond"], tooltip="Choose the shape of the buy signal marker")
targetProfit = input.float(1.23, title="Target Profit Percentage", step=0.01) / 100
trailingStopPercent = input.float(0.6, title="Trailing Stop Percentage", step=0.01) / 100

// Calculate EachKLine price change
priceDrop = open * (1.0 + percentDrop)
isBuySignal = low <= priceDrop

// At currentKMark buy signals below the line (optional))
plotshape(series=isBuySignal, location=location.belowbar, color=color.green, style=plotShapeStyle, size=size.small, title="Buy Signal", text="Buy")

// Display Information
if bar_index == na
    label.new(x=bar_index, y=na, text=str.tostring(percentDrop * 100, format.mintick) + "% Drop", xloc=xloc.bar_index, yloc=yloc.price, style=label.style_label_down, color=color.new(color.green, 0))
else
    label.delete(na)

// Strategy Logic
if (isBuySignal)
    strategy.entry("buy", strategy.long)

// Target selling price
if (strategy.position_size > 0)
    targetSellPrice = strategy.position_avg_price * (1 + targetProfit)
    strategy.exit("sell", from_entry="buy", limit=targetSellPrice, trail_offset=strategy.position_avg_price * trailingStopPercent)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Take-Profit-Smart-Trailing-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Channel Breakout StrategyPine Script · Breakout · 1d
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h