Strategy vault / Trend following
Dynamic Trading Theory Exponential Moving Average and Cumulative Volume Period Crossover Strategy
This strategy is a trading system that combines Exponential Moving Average (EMA) and Cumulative Volume Period (CVP). It captures market trend reversal points by analyzing the crossover between price EMA and…
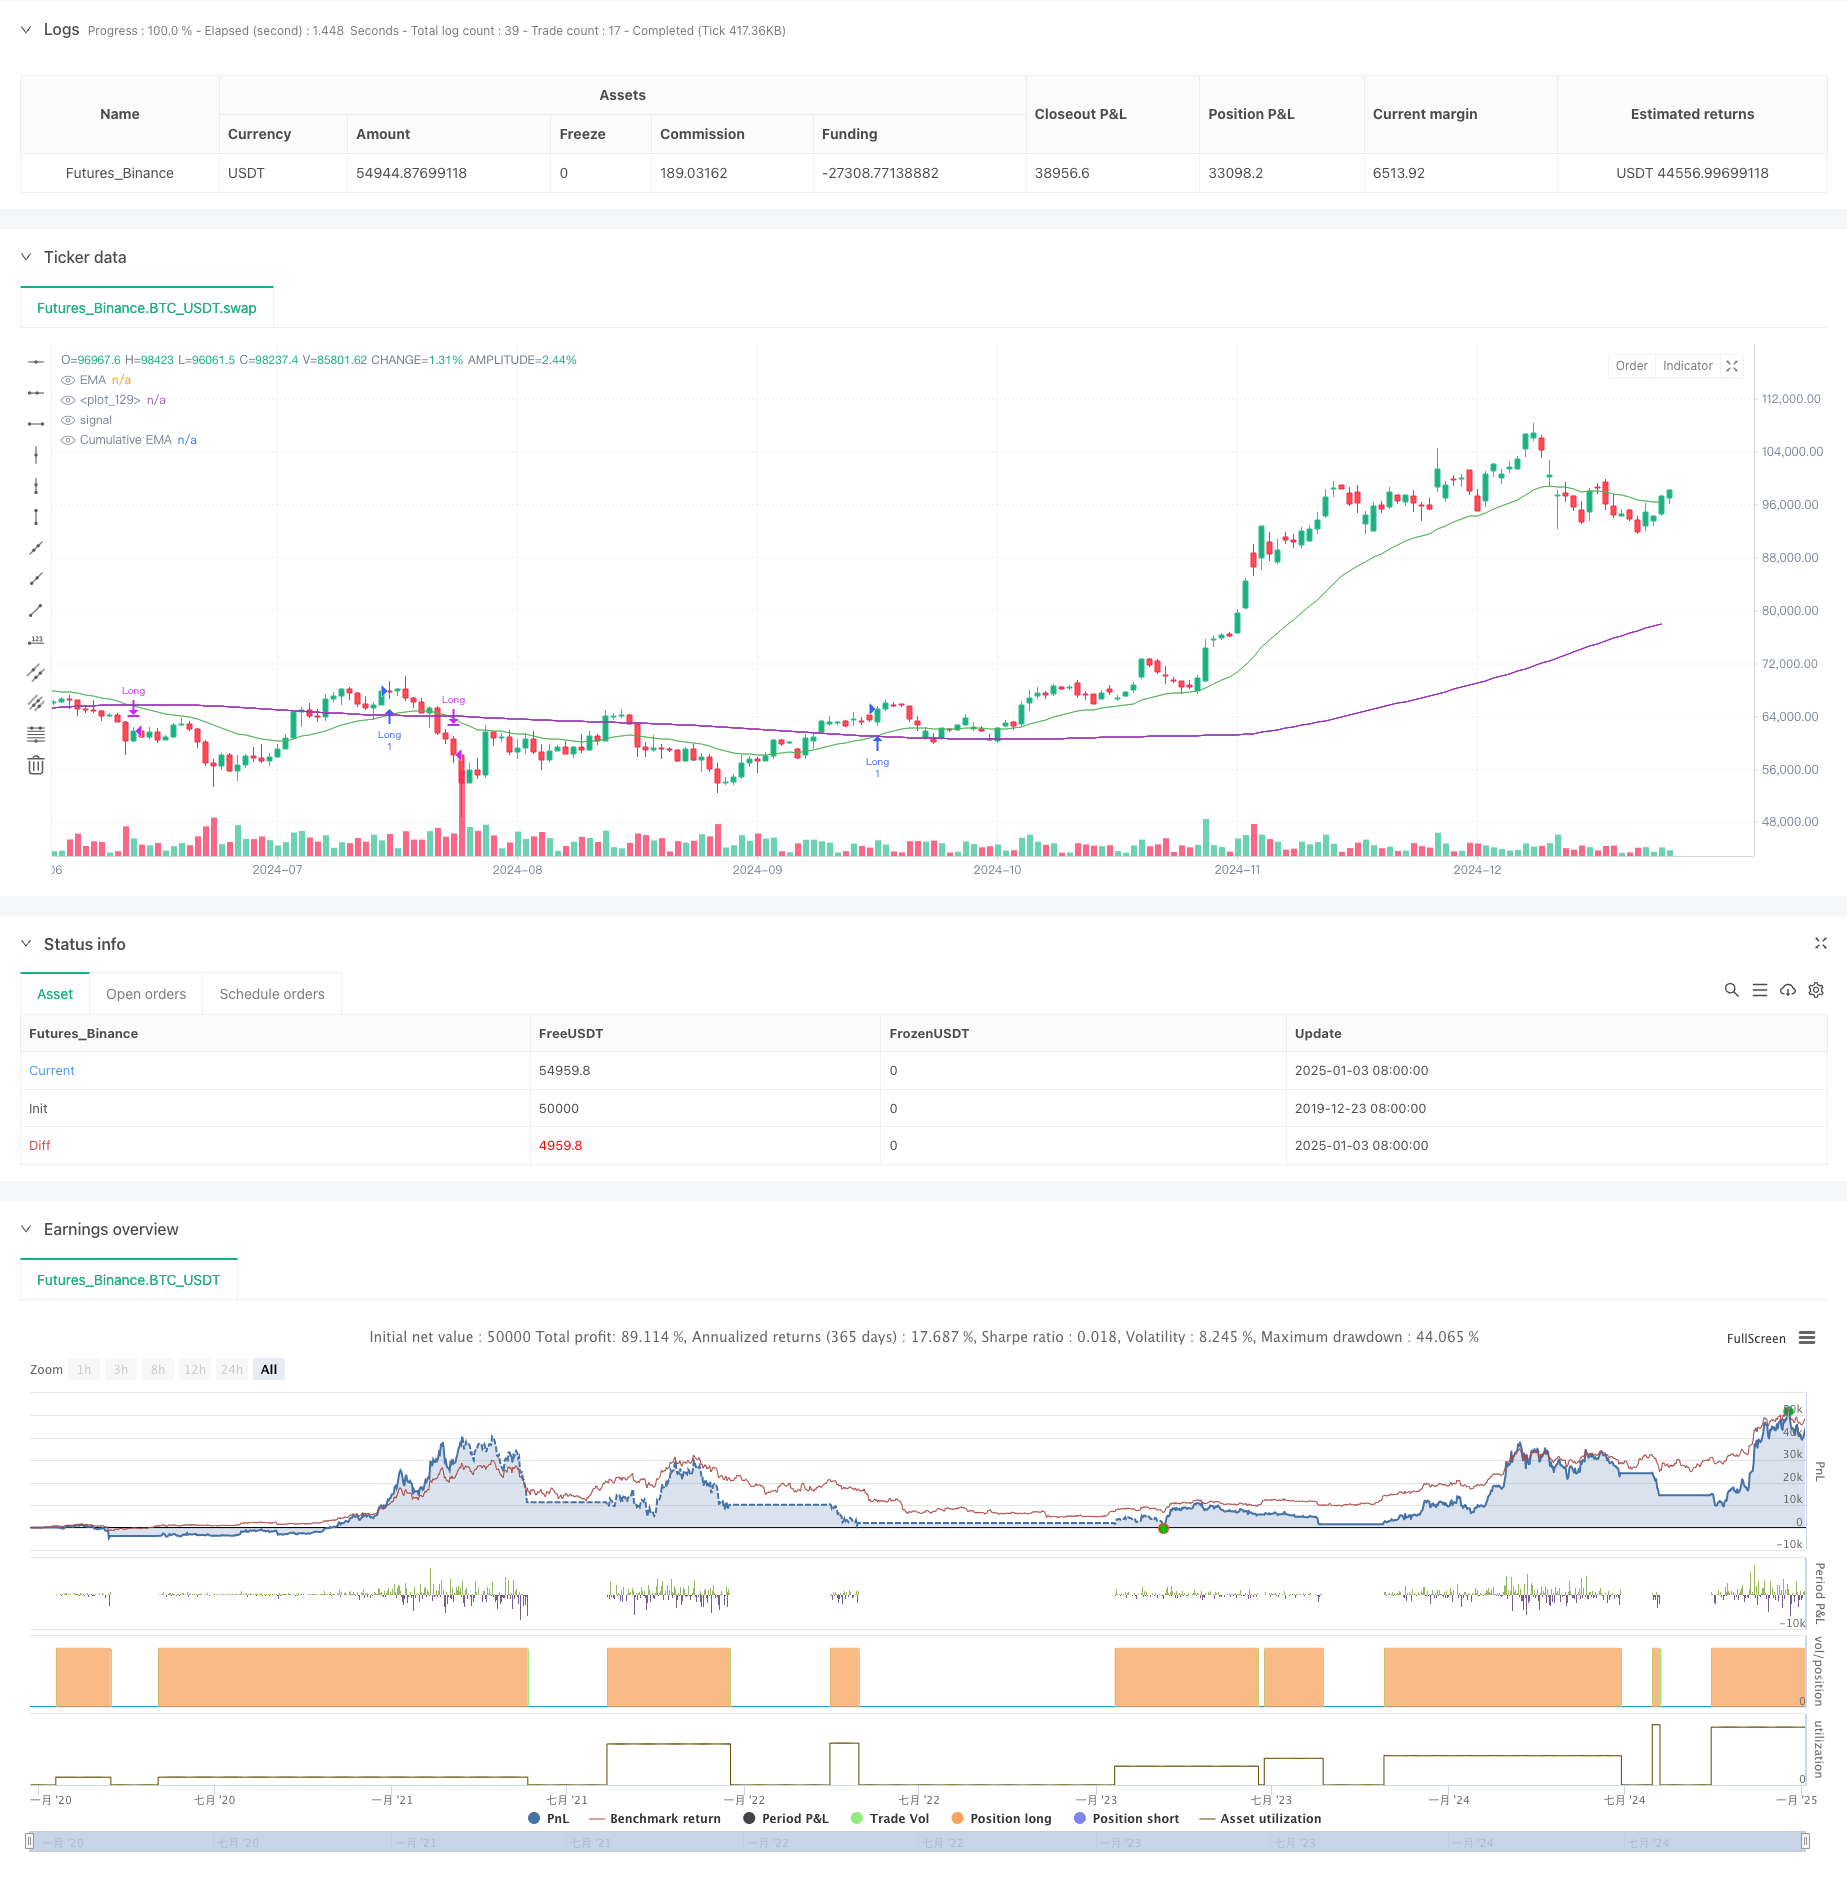
Overview
This strategy is a trading system that combines Exponential Moving Average (EMA) and Cumulative Volume Period (CVP). It captures market trend reversal points by analyzing the crossover between price EMA and cumulative volume-weighted price. The strategy includes a built-in time filter for limiting trading sessions and supports automatic position closing at the end of trading periods. It offers two different exit methods: reverse crossover exit and custom CVP exit, providing strong flexibility and adaptability.
Strategy Principle
The core logic of the strategy is based on the following key calculations:
- Calculate Average Price (AVWP): Multiply the arithmetic mean of high, low, and close prices with volume.
- Calculate Cumulative Volume Period value: Sum up volume-weighted prices over the set period and divide by cumulative volume.
- Calculate EMA of closing price and EMA of CVP separately.
- Generate long signals when price EMA crosses above CVP's EMA; generate short signals when price EMA crosses below CVP's EMA.
- Exit signals can be either reverse crossover signals or signals based on custom CVP periods.
Strategy Advantages
- Robust Signal System: Combines price trend and volume information for more accurate market direction judgment.
- High Adaptability: Can adapt to different market environments by adjusting EMA and CVP periods.
- Complete Risk Management: Built-in time filter prevents trading during unsuitable periods.
- Flexible Exit Mechanism: Provides two different exit methods to choose based on market characteristics.
- Good Visualization: Strategy provides clear graphical interface including signal markers and trend area filling.
Strategy Risks
- Lag Risk: EMA has inherent lag, which may cause slight delays in entry and exit timing.
- Oscillation Risk: May generate false signals in sideways markets.
- Parameter Sensitivity: Different parameter combinations may lead to significant performance variations.
- Liquidity Risk: CVP calculations may be inaccurate in low liquidity markets.
- Time Zone Dependency: Strategy uses New York time for time filtering, requiring attention to different market trading hours.
Strategy Optimization Directions
- Introduce Volatility Filter: Adjust strategy parameters based on market volatility to improve adaptability.
- Optimize Time Filter: Add multiple time windows for more precise trading session control.
- Add Volume Quality Assessment: Introduce volume analysis indicators to filter low-quality volume signals.
- Dynamic Parameter Adjustment: Develop adaptive parameter system to automatically adjust EMA and CVP periods based on market conditions.
- Add Market Sentiment Indicators: Combine with other technical indicators to confirm trading signals.
Summary
This is a quantitative trading strategy with complete structure and clear logic. By combining the advantages of EMA and CVP, it creates a trading system that can both capture trends and focus on risk control. The strategy is highly customizable and suitable for use in different market environments. Through the implementation of optimization suggestions, there is room for further performance improvement.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2025-01-04 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
// © sapphire_edge

// # ========================================================================= #
// #
// #        _____                   __    _              ______    __
// #      / ___/____ _____  ____  / /_  (_)_______     / ____/___/ /___ ____
// #      \__ \/ __ `/ __ \/ __ \/ __ \/ / ___/ _ \   / __/ / __  / __ `/ _ \
// #     ___/ / /_/ / /_/ / /_/ / / / / / /  /  __/  / /___/ /_/ / /_/ /  __/
// #    /____/\__,_/ .___/ .___/_/ /_/_/_/   \___/  /_____/\__,_/\__, /\___/
// #              /_/   /_/                                     /____/
// #
// # ========================================================================= #

strategy(shorttitle="⟡Sapphire⟡ EMA/CVP", title="[Sapphire] EMA/CVP Strategy", initial_capital= 50000, currency= currency.USD,default_qty_value = 1,commission_type= strategy.commission.cash_per_contract,overlay= true )

// # ========================================================================= #
// #                       // Settings Menu //
// # ========================================================================= #

// --------------------    Main Settings    -------------------- //
groupEMACVP = "EMA / Cumulative Volume Period"
tradeDirection = input.string(title='Trade Direction', defval='LONG', options=['LONG', 'SHORT'], group=groupEMACVP)
emaLength = input.int(25, title='EMA Length', minval=1, maxval=200, group=groupEMACVP)
cumulativePeriod = input.int(100, title='Cumulative Volume Period', minval=1, maxval=200, step=5, group=groupEMACVP)
exitType = input.string(title="Exit Type", defval="Crossover", options=["Crossover", "Custom CVP" ], group=groupEMACVP)
cumulativePeriodForClose = input.int(50, title='Cumulative Period for Close Signal', minval=1, maxval=200, step=5, group=groupEMACVP)
showSignals = input.bool(true, title="Show Signals", group=groupEMACVP)
signalOffset = input.int(5, title="Signal Vertical Offset", group=groupEMACVP)

// --------------------    Time Filter Inputs    -------------------- //
groupTimeOfDayFilter = "Time of Day Filter"
useTimeFilter1  = input.bool(false, title="Enable Time Filter 1", group=groupTimeOfDayFilter)
startHour1      = input.int(0, title="Start Hour (24-hour format)", minval=0, maxval=23, group=groupTimeOfDayFilter)
startMinute1    = input.int(0, title="Start Minute", minval=0, maxval=59, group=groupTimeOfDayFilter)
endHour1        = input.int(23, title="End Hour (24-hour format)", minval=0, maxval=23, group=groupTimeOfDayFilter)
endMinute1      = input.int(45, title="End Minute", minval=0, maxval=59, group=groupTimeOfDayFilter)
closeAtEndTimeWindow = input.bool(false, title="Close Trades at End of Time Window", group=groupTimeOfDayFilter)

// --------------------    Trading Window    -------------------- //
isWithinTradingWindow(startHour, startMinute, endHour, endMinute) =>
    nyTime            = timestamp("America/New_York", year, month, dayofmonth, hour, minute)
    nyHour            = hour(nyTime)
    nyMinute          = minute(nyTime)
    timeInMinutes     = nyHour * 60 + nyMinute
    startInMinutes    = startHour * 60 + startMinute
    endInMinutes      = endHour * 60 + endMinute
    timeInMinutes    >= startInMinutes and timeInMinutes <= endInMinutes

timeCondition =  (useTimeFilter1 ? isWithinTradingWindow(startHour1, startMinute1, endHour1, endMinute1) : true)

// Check if the current bar is the last one within the specified time window
isEndOfTimeWindow() =>
    nyTime            = timestamp("America/New_York", year, month, dayofmonth, hour, minute)
    nyHour            = hour(nyTime)
    nyMinute          = minute(nyTime)
    timeInMinutes     = nyHour * 60 + nyMinute
    endInMinutes      = endHour1 * 60 + endMinute1
    timeInMinutes == endInMinutes

// Logic to close trades if the time window ends
if timeCondition and closeAtEndTimeWindow and isEndOfTimeWindow()
    strategy.close_all(comment="Closing trades at end of time window")

// # ========================================================================= #
// #                       // Calculations //
// # ========================================================================= #

avgPrice = (high + low + close) / 3
avgPriceVolume = avgPrice * volume

cumulPriceVolume = math.sum(avgPriceVolume, cumulativePeriod)
cumulVolume = math.sum(volume, cumulativePeriod)
cumValue = cumulPriceVolume / cumulVolume

cumulPriceVolumeClose = math.sum(avgPriceVolume, cumulativePeriodForClose)
cumulVolumeClose = math.sum(volume, cumulativePeriodForClose)
cumValueClose = cumulPriceVolumeClose / cumulVolumeClose

emaVal = ta.ema(close, emaLength)
emaCumValue = ta.ema(cumValue, emaLength)

// # ========================================================================= #
// #                       // Signal Logic //
// # ========================================================================= #

// Strategy Entry Conditions
longEntryCondition = ta.crossover(emaVal, emaCumValue) and tradeDirection == 'LONG'
shortEntryCondition = ta.crossunder(emaVal, emaCumValue) and tradeDirection == 'SHORT'

// User-Defined Exit Conditions
longExitCondition = false
shortExitCondition = false

if exitType == "Crossover"
    longExitCondition := ta.crossunder(emaVal, emaCumValue)
    shortExitCondition := ta.crossover(emaVal, emaCumValue)

if exitType == "Custom CVP"
    emaCumValueClose = ta.ema(cumValueClose, emaLength)
    longExitCondition := ta.crossunder(emaVal, emaCumValueClose)
    shortExitCondition := ta.crossover(emaVal, emaCumValueClose)

// # ========================================================================= #
// #                       // Strategy Management //
// # ========================================================================= #

// Strategy Execution
if longEntryCondition and timeCondition
    strategy.entry('Long', strategy.long)
    label.new(bar_index, high - signalOffset, "◭", style=label.style_label_up, color = color.rgb(119, 0, 255, 20), textcolor=color.white)

if shortEntryCondition and timeCondition
    strategy.entry('Short', strategy.short)
    label.new(bar_index, low + signalOffset, "⧩", style=label.style_label_down, color = color.rgb(255, 85, 0, 20), textcolor=color.white)

if strategy.position_size > 0 and longExitCondition
    strategy.close('Long')

if strategy.position_size < 0 and shortExitCondition
    strategy.close('Short')

// # ========================================================================= #
// #                         // Plots and Charts //
// # ========================================================================= #

plot(emaVal, title='EMA', color=color.new(color.green, 25))
plot(emaCumValue, title='Cumulative EMA', color=color.new(color.purple, 35))
fill(plot(emaVal), plot(emaCumValue), color=emaVal > emaCumValue ? #008ee6 : #d436a285, title='EMA and Cumulative Area', transp=70)
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Trading-Theory-Exponential-Moving-Average-and-Cumulative-Volume-Period-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- ATR and T3 Moving Average StrategyPine Script · Trend following · 5m