Strategy vault / Trend following
Dynamic Trend Following ATR Multi Period Trading Strategy
This strategy is a dynamic trend following system based on the ATR (Average True Range) indicator, combining multi-period analysis and portfolio management capabilities. The strategy tracks the relative position…
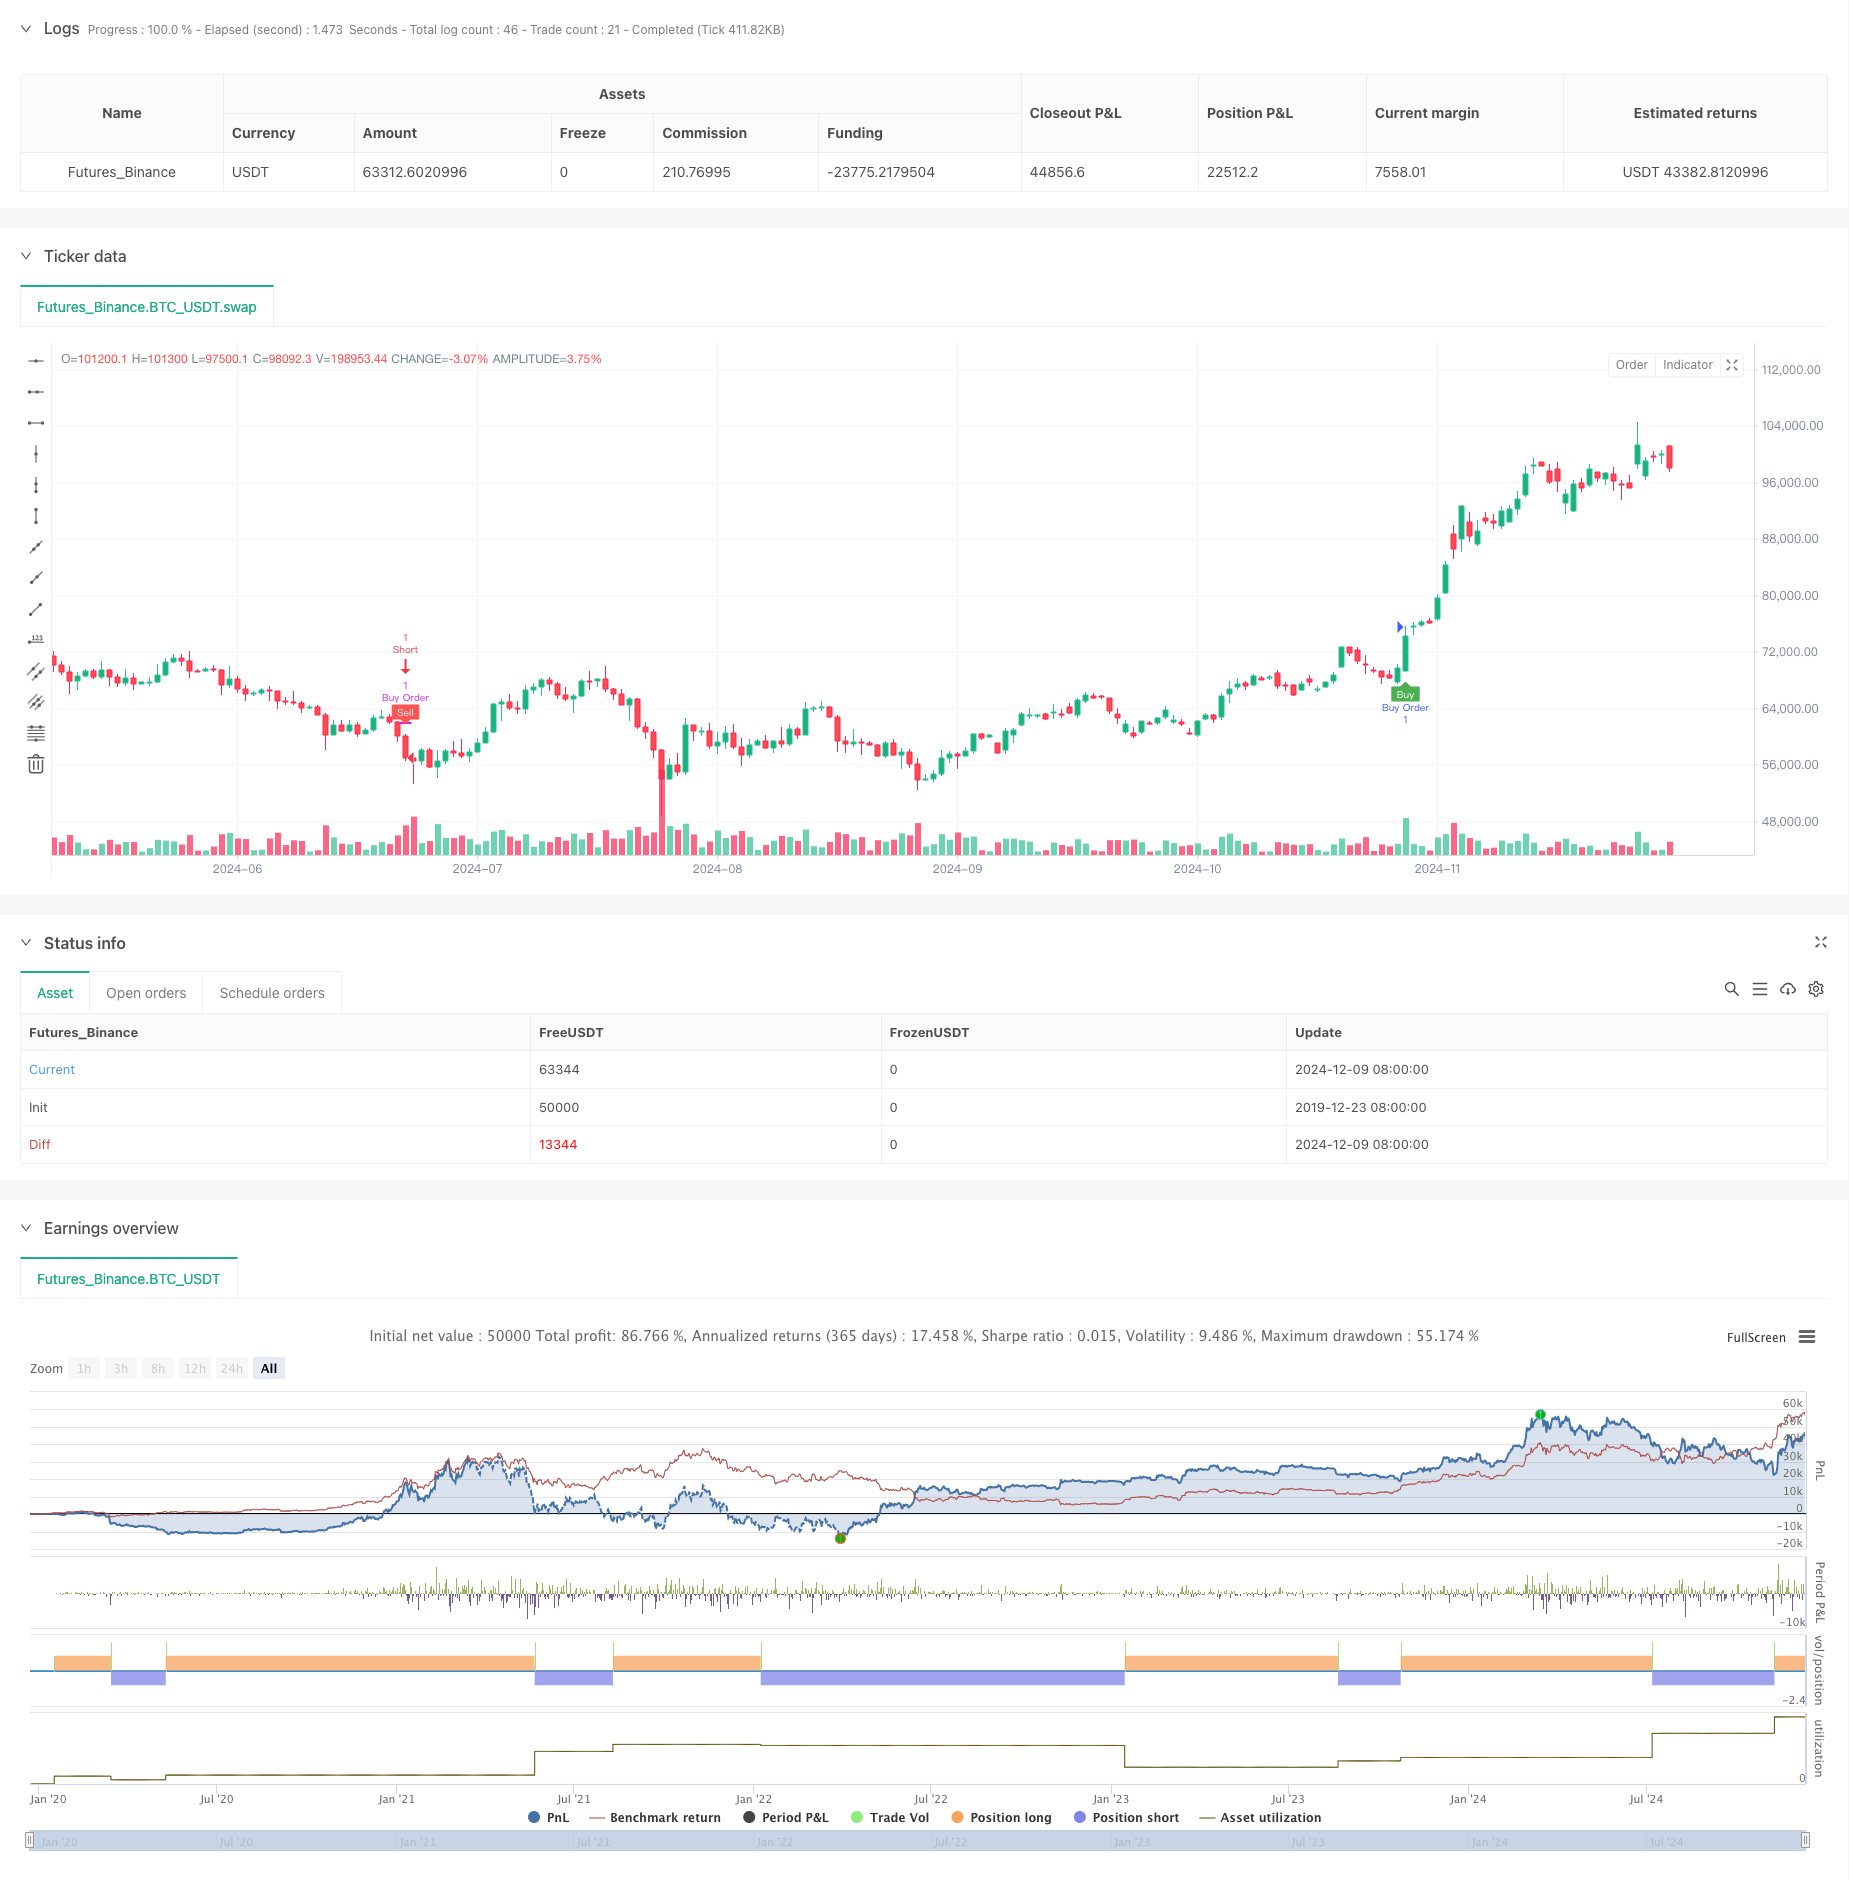
Overview
This strategy is a dynamic trend following system based on the ATR (Average True Range) indicator, combining multi-period analysis and portfolio management capabilities. The strategy tracks the relative position between price and ATR channel to capture trend changes across different timeframes while dynamically managing positions according to user-defined trading quantities. The strategy design balances trend following stability with trading timing flexibility.
Strategy Principle
The core logic of the strategy is based on the following key elements:
- Uses ATR indicator to establish dynamic stop-loss channel, with channel width determined by ATR period and sensitivity parameters
- Determines buy/sell signals through crossovers between EMA and ATR channel
- Supports operation across multiple timeframes from 5 minutes to 2 hours
- Incorporates portfolio tracking mechanism to dynamically adjust buy/sell quantities based on current positions
- Optional use of Heikin Ashi candles to reduce false signals
Strategy Advantages
- High Adaptability - Dynamically adjusts channel width through ATR to adapt to different market conditions
- Controlled Risk - Built-in stop-loss mechanism provides dynamic stop-loss levels through ATR channel
- Operational Flexibility - Supports multi-period analysis, allowing selection of appropriate timeframes for different instruments
- Position Management - Achieves dynamic position management through portfolio tracking
- Signal Stability - Optional smoothed candles to reduce noise and improve signal quality
Strategy Risks
- Trend Dependency - May generate frequent trades in ranging markets
- Lag - Use of moving averages and ATR introduces some signal delay
- Parameter Sensitivity - Strategy performance heavily influenced by choice of ATR period and sensitivity parameters
- Money Management - Requires appropriate setting of trade quantities to avoid over-position
- Market Adaptability - Performance may vary across different market conditions
Strategy Optimization Directions
- Signal Filtering
- Add trend strength confirmation indicators
- Introduce volume analysis
- Consider adding volatility filters
- Position Management
- Dynamically adjust position size based on volatility
- Implement scaled entry and exit
- Add maximum drawdown control
- Stop Loss Optimization
- Incorporate support/resistance levels for stop placement
- Implement trailing stops
- Optimize stop distance calculation method
Summary
This strategy is a complete trading system combining technical analysis and portfolio management. It provides stable trend following capabilities through ATR dynamic channels and multi-period analysis while considering position management needs in actual trading. Strategy optimization should focus on improving signal quality and enhancing risk control. Further practicality can be achieved through parameter optimization and feature expansion.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-12-10 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy(title='ADET GİRMELİ Trend İz Süren Stop Strategy', overlay=true, overlay=true,default_qty_type = strategy.fixed, default_qty_value = 1)

// Inputs
a = input(9, title='Key Value. "This changes the sensitivity"')
c = input(3, title='ATR Period')
h = input(false, title='Signals from Heikin Ashi Candles')

xATR = ta.atr(c)
nLoss = a * xATR

src = h ? request.security(ticker.heikinashi(syminfo.tickerid), timeframe.period, close, lookahead=barmerge.lookahead_off) : close

xATRTrailingStop = 0.0
iff_1 = src > nz(xATRTrailingStop[1], 0) ? src - nLoss : src + nLoss
iff_2 = src < nz(xATRTrailingStop[1], 0) and src[1] < nz(xATRTrailingStop[1], 0) ? math.min(nz(xATRTrailingStop[1]), src + nLoss) : iff_1
xATRTrailingStop := src > nz(xATRTrailingStop[1], 0) and src[1] > nz(xATRTrailingStop[1], 0) ? math.max(nz(xATRTrailingStop[1]), src - nLoss) : iff_2

pos = 0
iff_3 = src[1] > nz(xATRTrailingStop[1], 0) and src < nz(xATRTrailingStop[1], 0) ? -1 : nz(pos[1], 0)
pos := src[1] < nz(xATRTrailingStop[1], 0) and src > nz(xATRTrailingStop[1], 0) ? 1 : iff_3

xcolor = pos == -1 ? color.red : pos == 1 ? color.green : color.blue

ema = ta.ema(src, 1)
above = ta.crossover(ema, xATRTrailingStop)
below = ta.crossover(xATRTrailingStop, ema)

buy = src > xATRTrailingStop and above
sell = src < xATRTrailingStop and below

barbuy = src > xATRTrailingStop
barsell = src < xATRTrailingStop
// Alım ve Satım Sinyalleri
buySignal = src > xATRTrailingStop and above
sellSignal = src < xATRTrailingStop and below

// Kullanıcı girişi
sell_quantity = input.int(1, title="Sell Quantity", minval=1)
buy_quantity = input.int(1, title="Buy Quantity", minval=1)

// Portföy miktarı (örnek simülasyon verisi)
var portfolio_quantity = 0

// Sinyal üretimi (örnek sinyal, gerçek stratejinizle değiştirin)
indicator_signal = (src > xATRTrailingStop and above) ? "buy" :
                   (src < xATRTrailingStop and below) ? "sell" : "hold"

// Şartlara göre al/sat
if indicator_signal == "buy" and portfolio_quantity < buy_quantity
    strategy.entry("Buy Order", strategy.long, qty=buy_quantity)
    portfolio_quantity := portfolio_quantity + buy_quantity

if indicator_signal == "sell" and portfolio_quantity >= sell_quantity
    strategy.close("Buy Order", qty=sell_quantity)
    portfolio_quantity := portfolio_quantity - sell_quantity
// Plot buy and sell signals
plotshape(buy, title='Buy', text='Buy', style=shape.labelup, location=location.belowbar, color=color.new(color.green, 0), textcolor=color.new(color.white, 0), size=size.tiny)
plotshape(sell, title='Sell', text='Sell', style=shape.labeldown, location=location.abovebar, color=color.new(color.red, 0), textcolor=color.new(color.white, 0), size=size.tiny)

// Bar coloring
barcolor(barbuy ? color.rgb(6, 250, 14) : na)
barcolor(barsell ? color.red : na)

// Alerts
alertcondition(buy, 'UT Long', 'UT Long')
alertcondition(sell, 'UT Short', 'UT Short')

// Strategy Entry and Exit
if buy
    strategy.entry('Long', strategy.long)
if sell
    strategy.entry('Short', strategy.short)

// Optional Exit Conditions
if sell
    strategy.close('Long')
if buy
    strategy.close('Short')

// ///TARAMA///


// gurupSec = input.string(defval='1', options=['1', '2', '3', '4', '5','6','7'], group='Taraması yapılacak 40\'arlı gruplardan birini seçin', title='Grup seç')
// per = input.timeframe(defval='', title='PERİYOT',group = "Tarama yapmak istediğiniz periyotu seçin")
// loc = input.int(defval=20, title='Konum Ayarı', minval = -100,maxval = 200 , step = 5,  group='Tablonun konumunu belirleyin')


// func() =>
//     //ÖRNEK BİR FONKSİYON AŞAĞIDA YAZILMIŞTIR. SİZ DE İSTEDİĞİNİZ KOŞULLAR İÇİN TARAMA YAZABİLİRSİNİZ.
//     //rsi = ta.rsi(close,14)
//     //cond = rsi <= 30
//     //[close,cond]


//     ////value = ta.cci(close,length23)
//     cond = buySignal or sellSignal
//     [close,cond]


// c1 = input.symbol(title='1', defval='BIST:BRYAT',group = "1. Grup Hisseleri")
// c2 = input.symbol(title='2', defval='BIST:TARKM')
// c3 = input.symbol(title='3', defval='BIST:TNZTP')
// c4 = input.symbol(title='4', defval='BIST:ERBOS')
// c5 = input.symbol(title='5', defval='BIST:BFREN')
// c6 = input.symbol(title='6', defval='BIST:ALARK')
// c7 = input.symbol(title='7', defval='BIST:ISMEN')
// c8 = input.symbol(title='8', defval='BIST:CVKMD')
// c9 = input.symbol(title='9', defval='BIST:TTRAK')
// c10 = input.symbol(title='10', defval='BIST:ASELS')
// c11 = input.symbol(title='11', defval='BIST:ATAKP')
// c12 = input.symbol(title='12', defval='BIST:MGROS')
// c13 = input.symbol(title='13', defval='BIST:BRSAN')
// c14 = input.symbol(title='14', defval='BIST:ALFAS')
// c15 = input.symbol(title='15', defval='BIST:CWENE')
// c16 = input.symbol(title='16', defval='BIST:THYAO')
// c17 = input.symbol(title='17', defval='BIST:EREGL')
// c18 = input.symbol(title='18', defval='BIST:TUPRS')
// c19 = input.symbol(title='19', defval='BIST:YYLGD')
// c20 = input.symbol(title='20', defval='BIST:KLSER')
// c21 = input.symbol(title='21', defval='BIST:MIATK')
// c22 = input.symbol(title='22', defval='BIST:ASTOR')
// c23 = input.symbol(title='23', defval='BIST:DOAS')
// c24 = input.symbol(title='24', defval='BIST:ERCB')
// c25 = input.symbol(title='25', defval='BIST:REEDR')
// c26 = input.symbol(title='26', defval='BIST:DNISI')
// c27 = input.symbol(title='27', defval='BIST:ARZUM')
// c28 = input.symbol(title='28', defval='BIST:EBEBK')
// c29 = input.symbol(title='29', defval='BIST:KLKIM')
// c30 = input.symbol(title='30', defval='BIST:ONCSM')
// c31 = input.symbol(title='31', defval='BIST:SOKE')
// c32 = input.symbol(title='32', defval='BIST:GUBRF')
// c33 = input.symbol(title='33', defval='BIST:KONTR')
// c34 = input.symbol(title='34', defval='BIST:DAPGM')
// c35 = input.symbol(title='35', defval='BIST:BVSAN')
// c36 = input.symbol(title='36', defval='BIST:ODAS')
// c37 = input.symbol(title='37', defval='BIST:OYAKC')
// c38 = input.symbol(title='38', defval='BIST:KRPLS')
// c39 = input.symbol(title='39', defval='BIST:BOBET')


// [v1,s1] = request.security(c1, per, func())
// [v2,s2] = request.security(c2, per, func())
// [v3,s3] = request.security(c3, per, func())
// [v4,s4] = request.security(c4, per, func())
// [v5,s5] = request.security(c5, per, func())
// [v6,s6] = request.security(c6, per, func())
// [v7,s7] = request.security(c7, per, func())
// [v8,s8] = request.security(c8, per, func())
// [v9,s9] = request.security(c9, per, func())
// [v10,s10] = request.security(c10, per, func())
// [v11,s11] = request.security(c11, per, func())
// [v12,s12] = request.security(c12, per, func())
// [v13,s13] = request.security(c13, per, func())
// [v14,s14] = request.security(c14, per, func())
// [v15,s15] = request.security(c15, per, func())
// [v16,s16] = request.security(c16, per, func())
// [v17,s17] = request.security(c17, per, func())
// [v18,s18] = request.security(c18, per, func())
// [v19,s19] = request.security(c19, per, func())
// [v20,s20] = request.security(c20, per, func())
// [v21,s21] = request.security(c21, per, func())
// [v22,s22] = request.security(c22, per, func())
// [v23,s23] = request.security(c23, per, func())
// [v24,s24] = request.security(c24, per, func())
// [v25,s25] = request.security(c25, per, func())
// [v26,s26] = request.security(c26, per, func())
// [v27,s27] = request.security(c27, per, func())
// [v28,s28] = request.security(c28, per, func())
// [v29,s29] = request.security(c29, per, func())
// [v30,s30] = request.security(c30, per, func())
// [v31,s31] = request.security(c31, per, func())
// [v32,s32] = request.security(c32, per, func())
// [v33,s33] = request.security(c33, per, func())
// [v34,s34] = request.security(c34, per, func())
// [v35,s35] = request.security(c35, per, func())
// [v36,s36] = request.security(c36, per, func())
// [v37,s37] = request.security(c37, per, func())
// [v38,s38] = request.security(c38, per, func())
// [v39,s39] = request.security(c39, per, func())


// roundn(x, n) =>
//     mult = 1
//     if n != 0
//         for i = 1 to math.abs(n) by 1
//             mult *= 10
//             mult

//     n >= 0 ? math.round(x * mult) / mult : math.round(x / mult) * mult


// scr_label = 'A/G İZSÜREN\n'
// scr_label := s1 ? scr_label + syminfo.ticker(c1) + ' ' + str.tostring(roundn(v1, 2)) + '\n' : scr_label
// scr_label := s2 ? scr_label + syminfo.ticker(c2) + ' ' + str.tostring(roundn(v2, 2)) + '\n' : scr_label
// scr_label := s3 ? scr_label + syminfo.ticker(c3) + ' ' + str.tostring(roundn(v3, 2)) + '\n' : scr_label
// scr_label := s4 ? scr_label + syminfo.ticker(c4) + ' ' + str.tostring(roundn(v4, 2)) + '\n' : scr_label
// scr_label := s5 ? scr_label + syminfo.ticker(c5) + ' ' + str.tostring(roundn(v5, 2)) + '\n' : scr_label
// scr_label := s6 ? scr_label + syminfo.ticker(c6) + ' ' + str.tostring(roundn(v6, 2)) + '\n' : scr_label
// scr_label := s7 ? scr_label + syminfo.ticker(c7) + ' ' + str.tostring(roundn(v7, 2)) + '\n' : scr_label
// scr_label := s8 ? scr_label + syminfo.ticker(c8) + ' ' + str.tostring(roundn(v8, 2)) + '\n' : scr_label
// scr_label := s9 ? scr_label + syminfo.ticker(c9) + ' ' + str.tostring(roundn(v9, 2)) + '\n' : scr_label
// scr_label := s10 ? scr_label + syminfo.ticker(c10) + ' ' + str.tostring(roundn(v10, 2)) + '\n' : scr_label
// scr_label := s11 ? scr_label + syminfo.ticker(c11) + ' ' + str.tostring(roundn(v11, 2)) + '\n' : scr_label
// scr_label := s12 ? scr_label + syminfo.ticker(c12) + ' ' + str.tostring(roundn(v12, 2)) + '\n' : scr_label
// scr_label := s13 ? scr_label + syminfo.ticker(c13) + ' ' + str.tostring(roundn(v13, 2)) + '\n' : scr_label
// scr_label := s14 ? scr_label + syminfo.ticker(c14) + ' ' + str.tostring(roundn(v14, 2)) + '\n' : scr_label
// scr_label := s15 ? scr_label + syminfo.ticker(c15) + ' ' + str.tostring(roundn(v15, 2)) + '\n' : scr_label
// scr_label := s16 ? scr_label + syminfo.ticker(c16) + ' ' + str.tostring(roundn(v16, 2)) + '\n' : scr_label
// scr_label := s17 ? scr_label + syminfo.ticker(c17) + ' ' + str.tostring(roundn(v17, 2)) + '\n' : scr_label
// scr_label := s18 ? scr_label + syminfo.ticker(c18) + ' ' + str.tostring(roundn(v18, 2)) + '\n' : scr_label
// scr_label := s19 ? scr_label + syminfo.ticker(c19) + ' ' + str.tostring(roundn(v19, 2)) + '\n' : scr_label
// scr_label := s20 ? scr_label + syminfo.ticker(c20) + ' ' + str.tostring(roundn(v20, 2)) + '\n' : scr_label
// scr_label := s21 ? scr_label + syminfo.ticker(c21) + ' ' + str.tostring(roundn(v21, 2)) + '\n' : scr_label
// scr_label := s22 ? scr_label + syminfo.ticker(c22) + ' ' + str.tostring(roundn(v22, 2)) + '\n' : scr_label
// scr_label := s23 ? scr_label + syminfo.ticker(c23) + ' ' + str.tostring(roundn(v23, 2)) + '\n' : scr_label
// scr_label := s24 ? scr_label + syminfo.ticker(c24) + ' ' + str.tostring(roundn(v24, 2)) + '\n' : scr_label
// scr_label := s25 ? scr_label + syminfo.ticker(c25) + ' ' + str.tostring(roundn(v25, 2)) + '\n' : scr_label
// scr_label := s26 ? scr_label + syminfo.ticker(c26) + ' ' + str.tostring(roundn(v26, 2)) + '\n' : scr_label
// scr_label := s27 ? scr_label + syminfo.ticker(c27) + ' ' + str.tostring(roundn(v27, 2)) + '\n' : scr_label
// scr_label := s28 ? scr_label + syminfo.ticker(c28) + ' ' + str.tostring(roundn(v28, 2)) + '\n' : scr_label
// scr_label := s29 ? scr_label + syminfo.ticker(c29) + ' ' + str.tostring(roundn(v29, 2)) + '\n' : scr_label
// scr_label := s30 ? scr_label + syminfo.ticker(c30) + ' ' + str.tostring(roundn(v30, 2)) + '\n' : scr_label
// scr_label := s31 ? scr_label + syminfo.ticker(c31) + ' ' + str.tostring(roundn(v31, 2)) + '\n' : scr_label
// scr_label := s32 ? scr_label + syminfo.ticker(c32) + ' ' + str.tostring(roundn(v32, 2)) + '\n' : scr_label
// scr_label := s33 ? scr_label + syminfo.ticker(c33) + ' ' + str.tostring(roundn(v33, 2)) + '\n' : scr_label
// scr_label := s34 ? scr_label + syminfo.ticker(c34) + ' ' + str.tostring(roundn(v34, 2)) + '\n' : scr_label
// scr_label := s35 ? scr_label + syminfo.ticker(c35) + ' ' + str.tostring(roundn(v35, 2)) + '\n' : scr_label
// scr_label := s36 ? scr_label + syminfo.ticker(c36) + ' ' + str.tostring(roundn(v36, 2)) + '\n' : scr_label
// scr_label := s37 ? scr_label + syminfo.ticker(c37) + ' ' + str.tostring(roundn(v37, 2)) + '\n' : scr_label
// scr_label := s38 ? scr_label + syminfo.ticker(c38) + ' ' + str.tostring(roundn(v38, 2)) + '\n' : scr_label
// scr_label := s39 ? scr_label + syminfo.ticker(c39) + ' ' + str.tostring(roundn(v39, 2)) + '\n' : scr_label


// var panel = table.new(position = position.top_right,columns = 10,rows = 10,bgcolor = color.green,frame_color = color.white,border_color = color.red)


// if barstate.islast
//     table.cell(panel,0,0,text = str.tostring(scr_label))
// //------------------------------------------------------
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Trend-Following-ATR-Multi-Period-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- SuperTrend Trailing Stop Strategy Based on Heikin AshiPine Script · Trend following · 4h
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Incremental Order Size Fibonacci Retracement Trend Following StrategyPine Script · Trend following · 1d
- Supertrend Advance StrategyPine Script · Trend following · 5m
- Trend Tracking Strategy Based on Multi factor Model with Adaptive Trailing StoplossPine Script · Trend following · 1d
- Trend Tracking and Short term Trading Strategy Based on ADX IndicatorPine Script · Trend following · 1d