Dynamic Trend Momentum Breakout Strategy
The Dynamic Trend Momentum Breakout Strategy is a professional quantitative trading method specifically designed for high-momentum stocks. By combining Exponential Moving Averages (EMA), Relative Strength Index (RSI)…
Overview
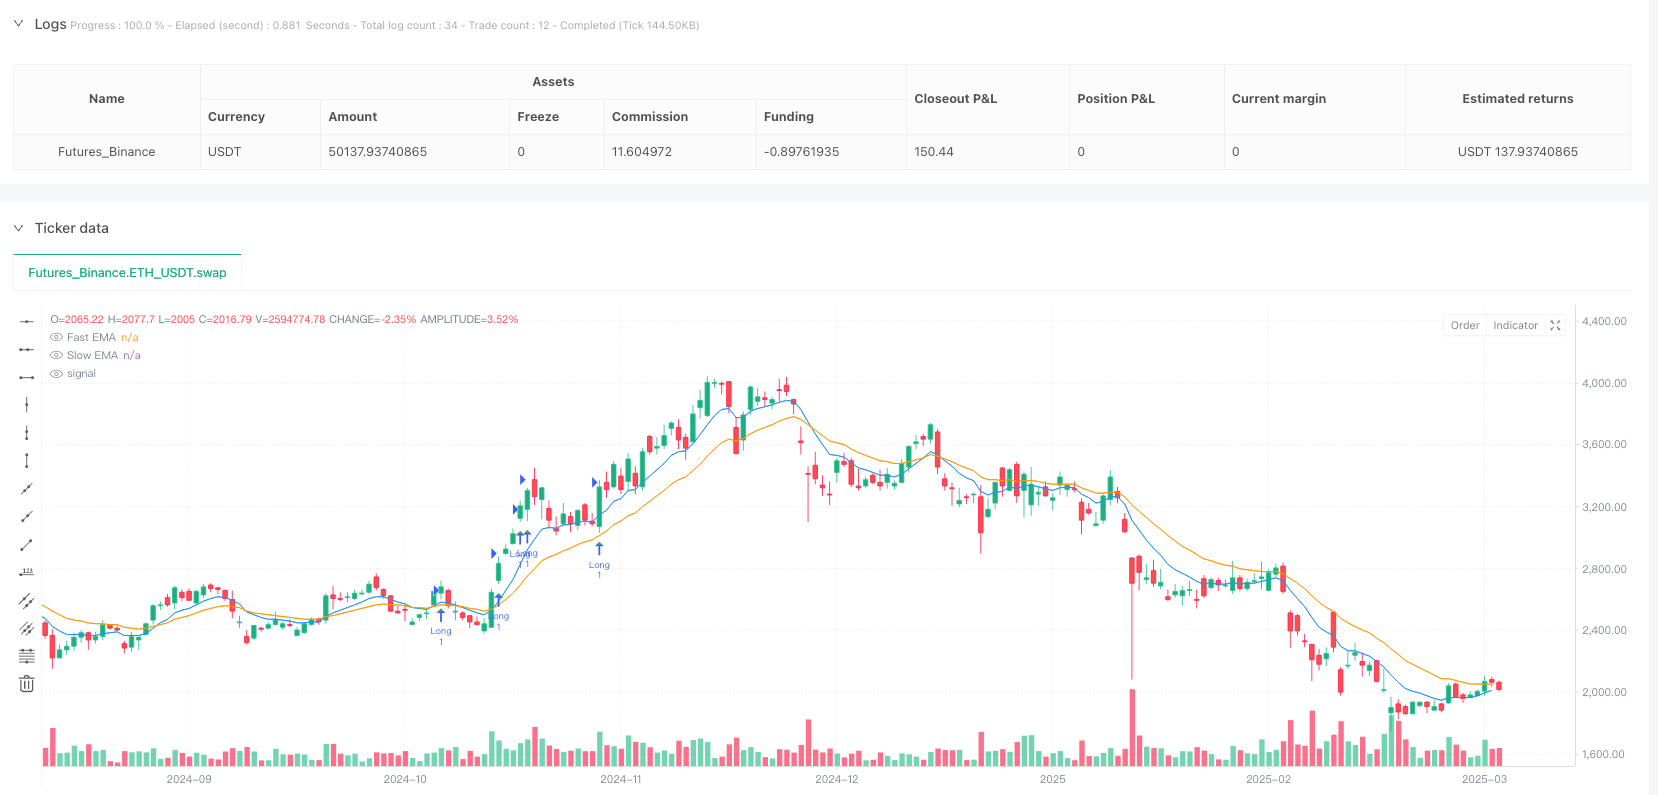
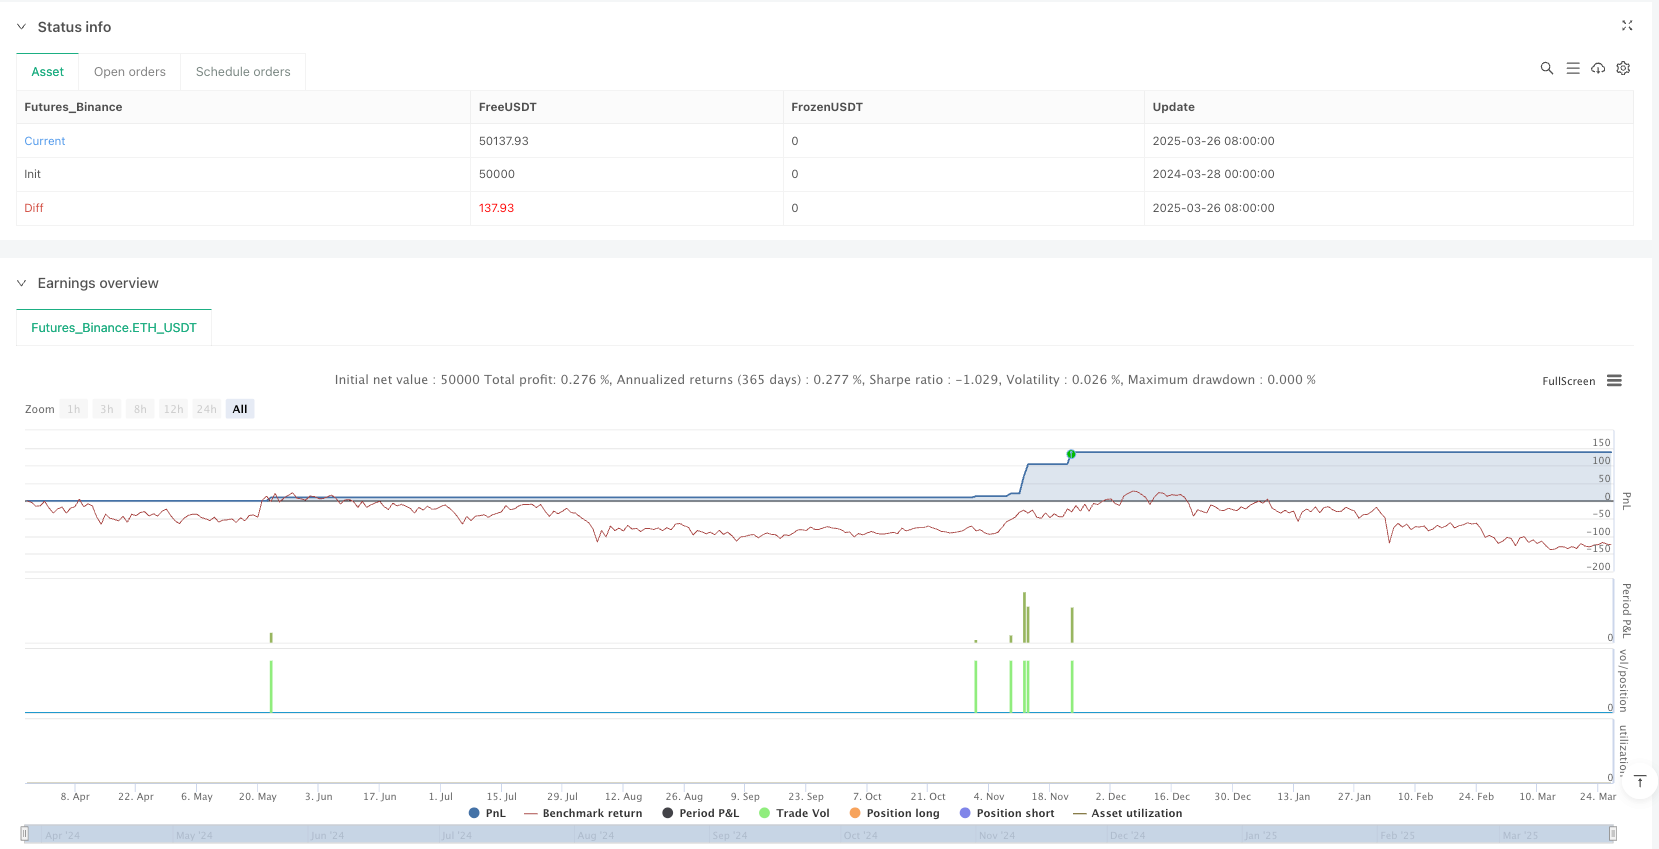
The Dynamic Trend Momentum Breakout Strategy is a professional quantitative trading method specifically designed for high-momentum stocks. By combining Exponential Moving Averages (EMA), Relative Strength Index (RSI) filtering, volume confirmation, and Average True Range (ATR)-based trailing stop-loss, the strategy aims to capture strong market breakouts while avoiding false signals.
Strategy Principles
The core principle of the strategy is based on multi-dimensional market signal verification:
- Use fast and slow EMAs to determine overall trend direction
- Utilize RSI to assess momentum and avoid negative divergences
- Confirm trading signals through volume breakouts
- Apply ATR for dynamic stop-loss and trailing profit management
Strategy Advantages
- High-precision signal filtering: Multiple condition verifications reduce error signal probability
- Dynamic risk management: ATR-based stop-loss mechanism protects capital
- Trend following: EMA combination ensures entry only in strong trends
- Momentum capture: Volume and RSI filtering ensure trade quality
Strategy Risks
- Severe market volatility may trigger stop-losses
- More invalid signals may occur in ranging markets
- Over-reliance on technical indicators might miss important fundamental information
Strategy Optimization Directions
- Introduce machine learning algorithms to optimize parameter selection
- Add cross-timeframe verification mechanisms
- Develop more complex multi-factor filtering algorithms
- Incorporate sentiment indicators and fundamental data
Summary
The Dynamic Trend Momentum Breakout Strategy builds a relatively robust quantitative trading method by integrating multiple technical analysis tools. Its core lies in balancing signal capture capability and risk control, providing traders with a systematic trading decision framework.
Source Pine Script
/*backtest
start: 2024-03-28 00:00:00
end: 2025-03-27 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"ETH_USDT"}]
*/

//@version=6
strategy("Enhanced First High Break Strategy v3", overlay=true, margin_long=100, margin_short=100)

// Input Parameters
emaFastLength = input.int(9, "Fast EMA Length")
emaSlowLength = input.int(20, "Slow EMA Length")
rsiLength = input.int(14, "RSI Length")
volumeAvgLength = input.int(20, "Volume Average Length")
atrLength = input.int(14, "ATR Length")

// Calculate Indicators
emaFast = ta.ema(close, emaFastLength)
emaSlow = ta.ema(close, emaSlowLength)
rsi = ta.rsi(close, rsiLength)
volAvg = ta.sma(volume, volumeAvgLength)
atr = ta.atr(atrLength)

// Pre-calculate lowest values (FIXED)
rsiLowCurrent = ta.lowest(rsi, 5)
rsiLowPrevious = ta.lowest(rsi[5], 5)
lowLowPrevious = ta.lowest(low[5], 5)

// Trend Conditions
bullishTrend = emaFast > emaSlow and emaFast > emaFast[1]
bearishDivergence = rsiLowCurrent > rsiLowPrevious and low < lowLowPrevious

// Entry Conditions
validBreakout = close > high[1] and close > emaFast
volumeConfirmation = volume > volAvg * 1.5
trendConfirmed = close > emaSlow and close[1] > emaSlow
rsiConfirmation = rsi > 50 and not bearishDivergence

// Final Entry Signal
entryCondition = validBreakout and volumeConfirmation and trendConfirmed

// Exit Conditions
stopLossPrice = low[1] - (atr * 0.50)
trailOffset = atr * 2

// Strategy Execution
if (entryCondition)
    strategy.entry("Long", strategy.long)
    strategy.exit("Exit", "Long", stop=stopLossPrice,trail_points=close > emaFast ? trailOffset : na,trail_offset=trailOffset)

// Plotting
plot(emaFast, "Fast EMA", color.new(color.blue, 0))
plot(emaSlow, "Slow EMA", color.new(color.orange, 0))
plotshape(entryCondition, style=shape.triangleup, color=color.green, location=location.belowbar)
Published by ianzeng123 on the FMZ strategy square · last modified 2025-03-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Trend-Momentum-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Filter Trend Breakthrough Smart Moving Average Trading StrategyPine Script · Breakout · 1h
- Multi Indicator Trend Breakout Strategy with Dynamic Stop LossPine Script · Breakout · 1d
- Enhanced Bollinger Breakout Quantitative Strategy with Momentum Filter Integration SystemPine Script · Breakout · 2d
- Multi Strategy Adaptive Trend Following and Breakout Trading SystemPine Script · Breakout · 1d
- Multi Dimensional Technical Indicator Fusion Trend Breakthrough StrategyPine Script · Breakout · 1h
- Multi Indicator Trend Following and Volatility Breakout StrategyPine Script · Breakout · 2h