Strategy vault / Trend following
Dynamic Wave Trend Tracking Strategy
This strategy is a quantitative trading system based on the WaveTrend indicator and trend following. It combines the WaveTrend indicator with moving averages to form a complete trading decision framework. The…
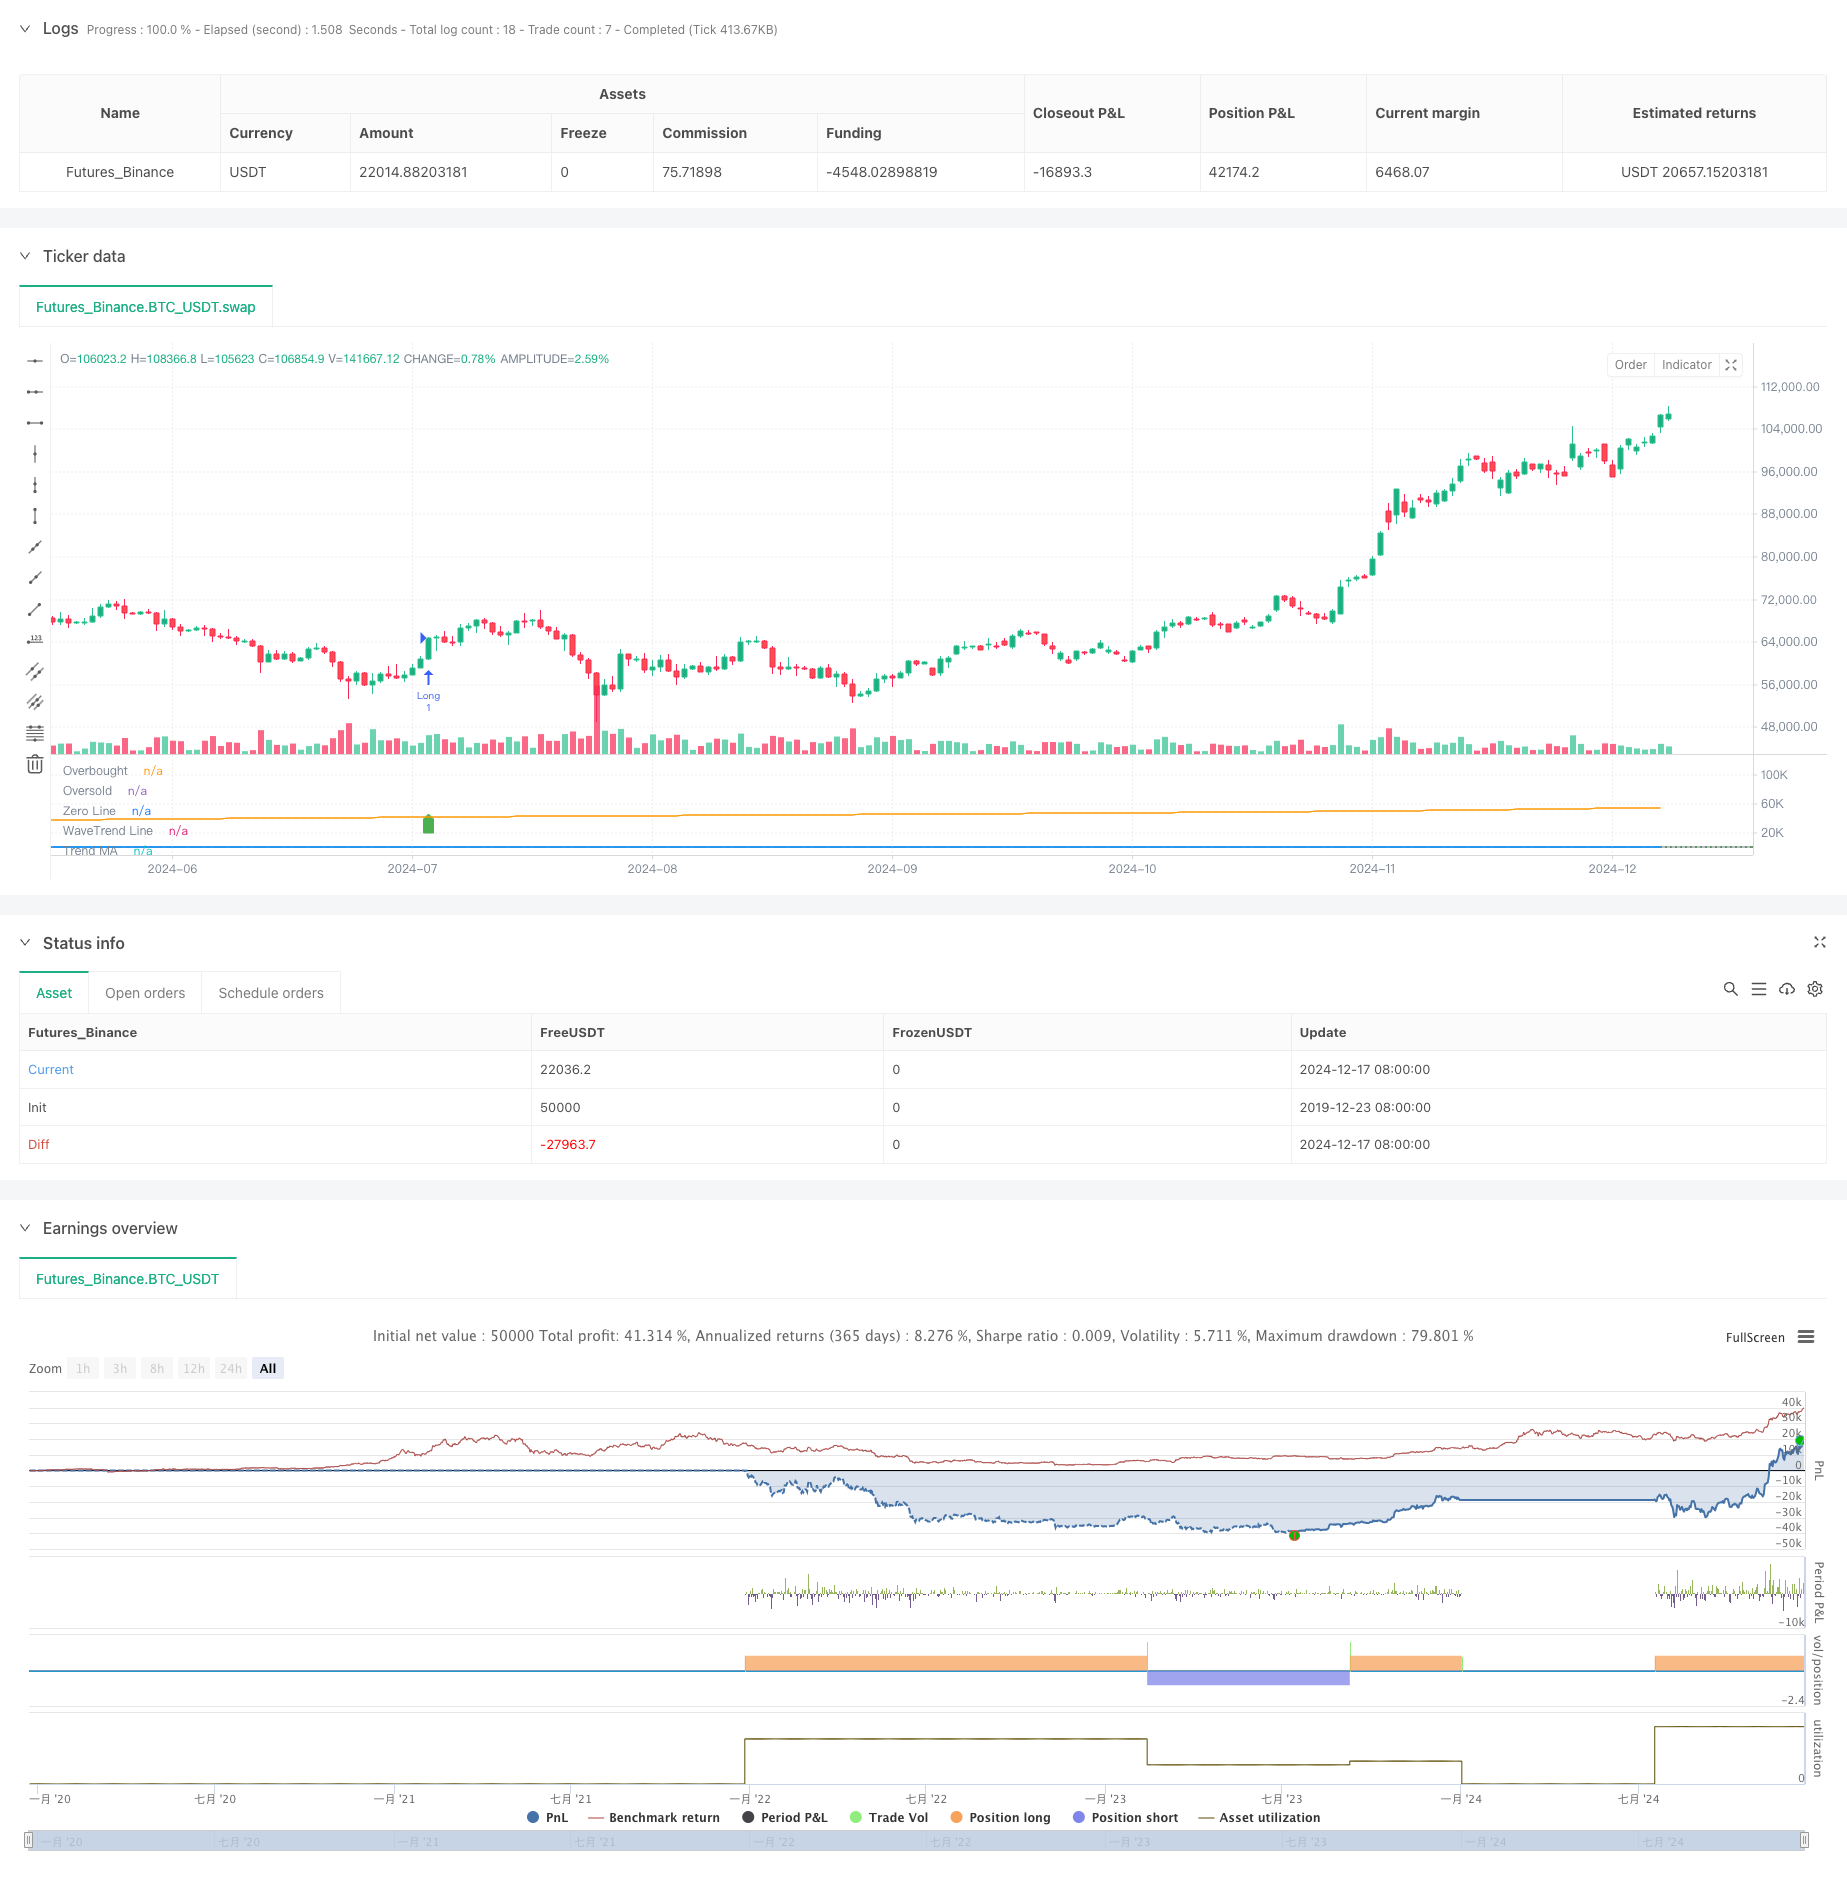
Overview
This strategy is a quantitative trading system based on the WaveTrend indicator and trend following. It combines the WaveTrend indicator with moving averages to form a complete trading decision framework. The strategy utilizes EMA and SMA to calculate wave trend values and overall market trends, identifies market turning points through overbought and oversold thresholds, and incorporates trend filters to improve trading accuracy.
Strategy Principle
The strategy's core is implemented through the following steps:
- Calculate HLC average price (average of high, low, and closing prices)
- Smooth the HLC average using EMA to obtain the ESA line
- Calculate and smooth the deviation between HLC average and ESA line using EMA
- Calculate K value based on deviation and smooth twice with EMA to get the final TCI line
- Use SMA to calculate long-term trend line as trend filter
- Generate trading signals when TCI line breaks through overbought/oversold levels and aligns with trend direction
Strategy Advantages
- High signal reliability: Effectively reduces false signals by combining WaveTrend indicator and trend filter
- Comprehensive risk control: Clear overbought/oversold thresholds for timely stop-loss
- Strong adaptability: Strategy parameters can be flexibly adjusted for different market conditions
- Clear operational logic: Explicit entry and exit conditions, easy to execute
- Comprehensive analysis: Considers both short-term fluctuations and long-term trends, improving trading stability
Strategy Risks
- Trend reversal risk: May lag in volatile markets
- Parameter sensitivity: Different parameter combinations may lead to drastically different results
- Market adaptability: May generate frequent trades in ranging markets
- Capital management: Requires reasonable position control to handle market volatility
- Technical dependence: Reliance on technical indicators may overlook fundamental factors
Strategy Optimization Directions
- Add volatility filter: Adjust trading thresholds during high volatility periods
- Incorporate multi-timeframe analysis: Combine signals from different timeframes to improve accuracy
- Optimize parameter adaptation: Dynamically adjust indicator parameters based on market conditions
- Improve profit/loss management: Add dynamic take-profit and stop-loss mechanisms
- Add volume confirmation: Incorporate volume analysis to enhance signal reliability
Summary
The strategy constructs a robust trading system by cleverly combining the WaveTrend indicator with trend filters. While maintaining operational simplicity, it achieves comprehensive market analysis. Although certain risks exist, the strategy has good practical value and development potential through proper risk management and continuous optimization.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-12-18 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © mojomarv

//@version=6
strategy("WaveTrend with Trend Filter", shorttitle="WaveTrend Trend", overlay=false, initial_capital = 100000)

// Inputs for the WaveTrend indicator
inputLength = input.int(10, title="Channel Length", minval=1)
avgLength = input.int(21, title="Average Length", minval=1)
obLevel = input.float(45, title="Overbought Level")
osLevel = input.float(-45, title="Oversold Level")
showSignals = input.bool(true, title="Show Buy/Sell Signals")

// Trend filter input
maLength = input.int(500, title="Trend MA Length", minval=1)

// Calculate WaveTrend values
hlc_avg = (high + low + close) / 3  // Renamed from hlc3 to hlc_avg
esa = ta.ema(hlc_avg, inputLength)
d = ta.ema(math.abs(hlc_avg - esa), inputLength)
k = (hlc_avg - esa) / (0.015 * d)
ci = ta.ema(k, avgLength)
tci = ta.ema(ci, avgLength)

// Moving average for trend detection
trendMA = ta.sma(close, maLength)

// Determine trend
bullishTrend = close > trendMA
bearishTrend = close < trendMA

// Generate signals with trend filter
crossUp = ta.crossover(tci, osLevel)
crossDown = ta.crossunder(tci, obLevel)

// Plot WaveTrend
plot(tci, title="WaveTrend Line", color=color.new(color.blue, 0), linewidth=2)
hline(obLevel, "Overbought", color=color.red, linestyle=hline.style_dotted)
hline(osLevel, "Oversold", color=color.green, linestyle=hline.style_dotted)
hline(0, "Zero Line", color=color.gray, linestyle=hline.style_solid)

// Plot moving average for trend visualization
plot(trendMA, title="Trend MA", color=color.orange, linewidth=1)

// Plot buy and sell signals
plotshape(showSignals and crossUp, title="Buy Signal", location=location.belowbar, style=shape.labelup, color=color.new(color.green, 0), size=size.small)
plotshape(showSignals and crossDown, title="Sell Signal", location=location.abovebar, style=shape.labeldown, color=color.new(color.red, 0), size=size.small)

// Alerts
alertcondition(crossUp, title="Buy Alert", message="WaveTrend Buy Signal (Trend Confirmed)")
alertcondition(crossDown, title="Sell Alert", message="WaveTrend Sell Signal (Trend Confirmed)")
alertcondition(bullishTrend, title="bull", message="WaveTrend Sell Signal (Trend Confirmed)")
alertcondition(bearishTrend, title="bear", message="WaveTrend Sell Signal (Trend Confirmed)")

// Strategy logic
if crossUp and bullishTrend
    strategy.entry("Long", strategy.long)

if crossDown
    strategy.close("Long")

if crossDown and bearishTrend
    strategy.entry("Short", strategy.short)

if crossUp
strategy.close("Short")Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Wave-Trend-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA SMA Trend Following with Swing Trading Strategy Combined Volume Filter and Percentage Take Profit Stop Loss SystemPine Script · Trend following · 1d
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Factor Trend Price Action Strategy with Dynamic Risk Management SystemPine Script · Trend following · 2h
- Multi Period Moving Average Ribbon and MACD Crossover Strategy SystemPine Script · Trend following · 1h
- Multi Period Phase Crossover with EMA Trend Following StrategyPine Script · Trend following · 1d
- Trend Following Strategy Based on Moving Average 439858Pine Script · Trend following · 1d