Dynmaic Risk Adjusted Momentum Trading Strategy
This unique systematic rulebased trading strategy is in the trend following category. It uses normalised prices series transformed from raw ticker price to gernerate trading signals. Advanced position sizing and risk…
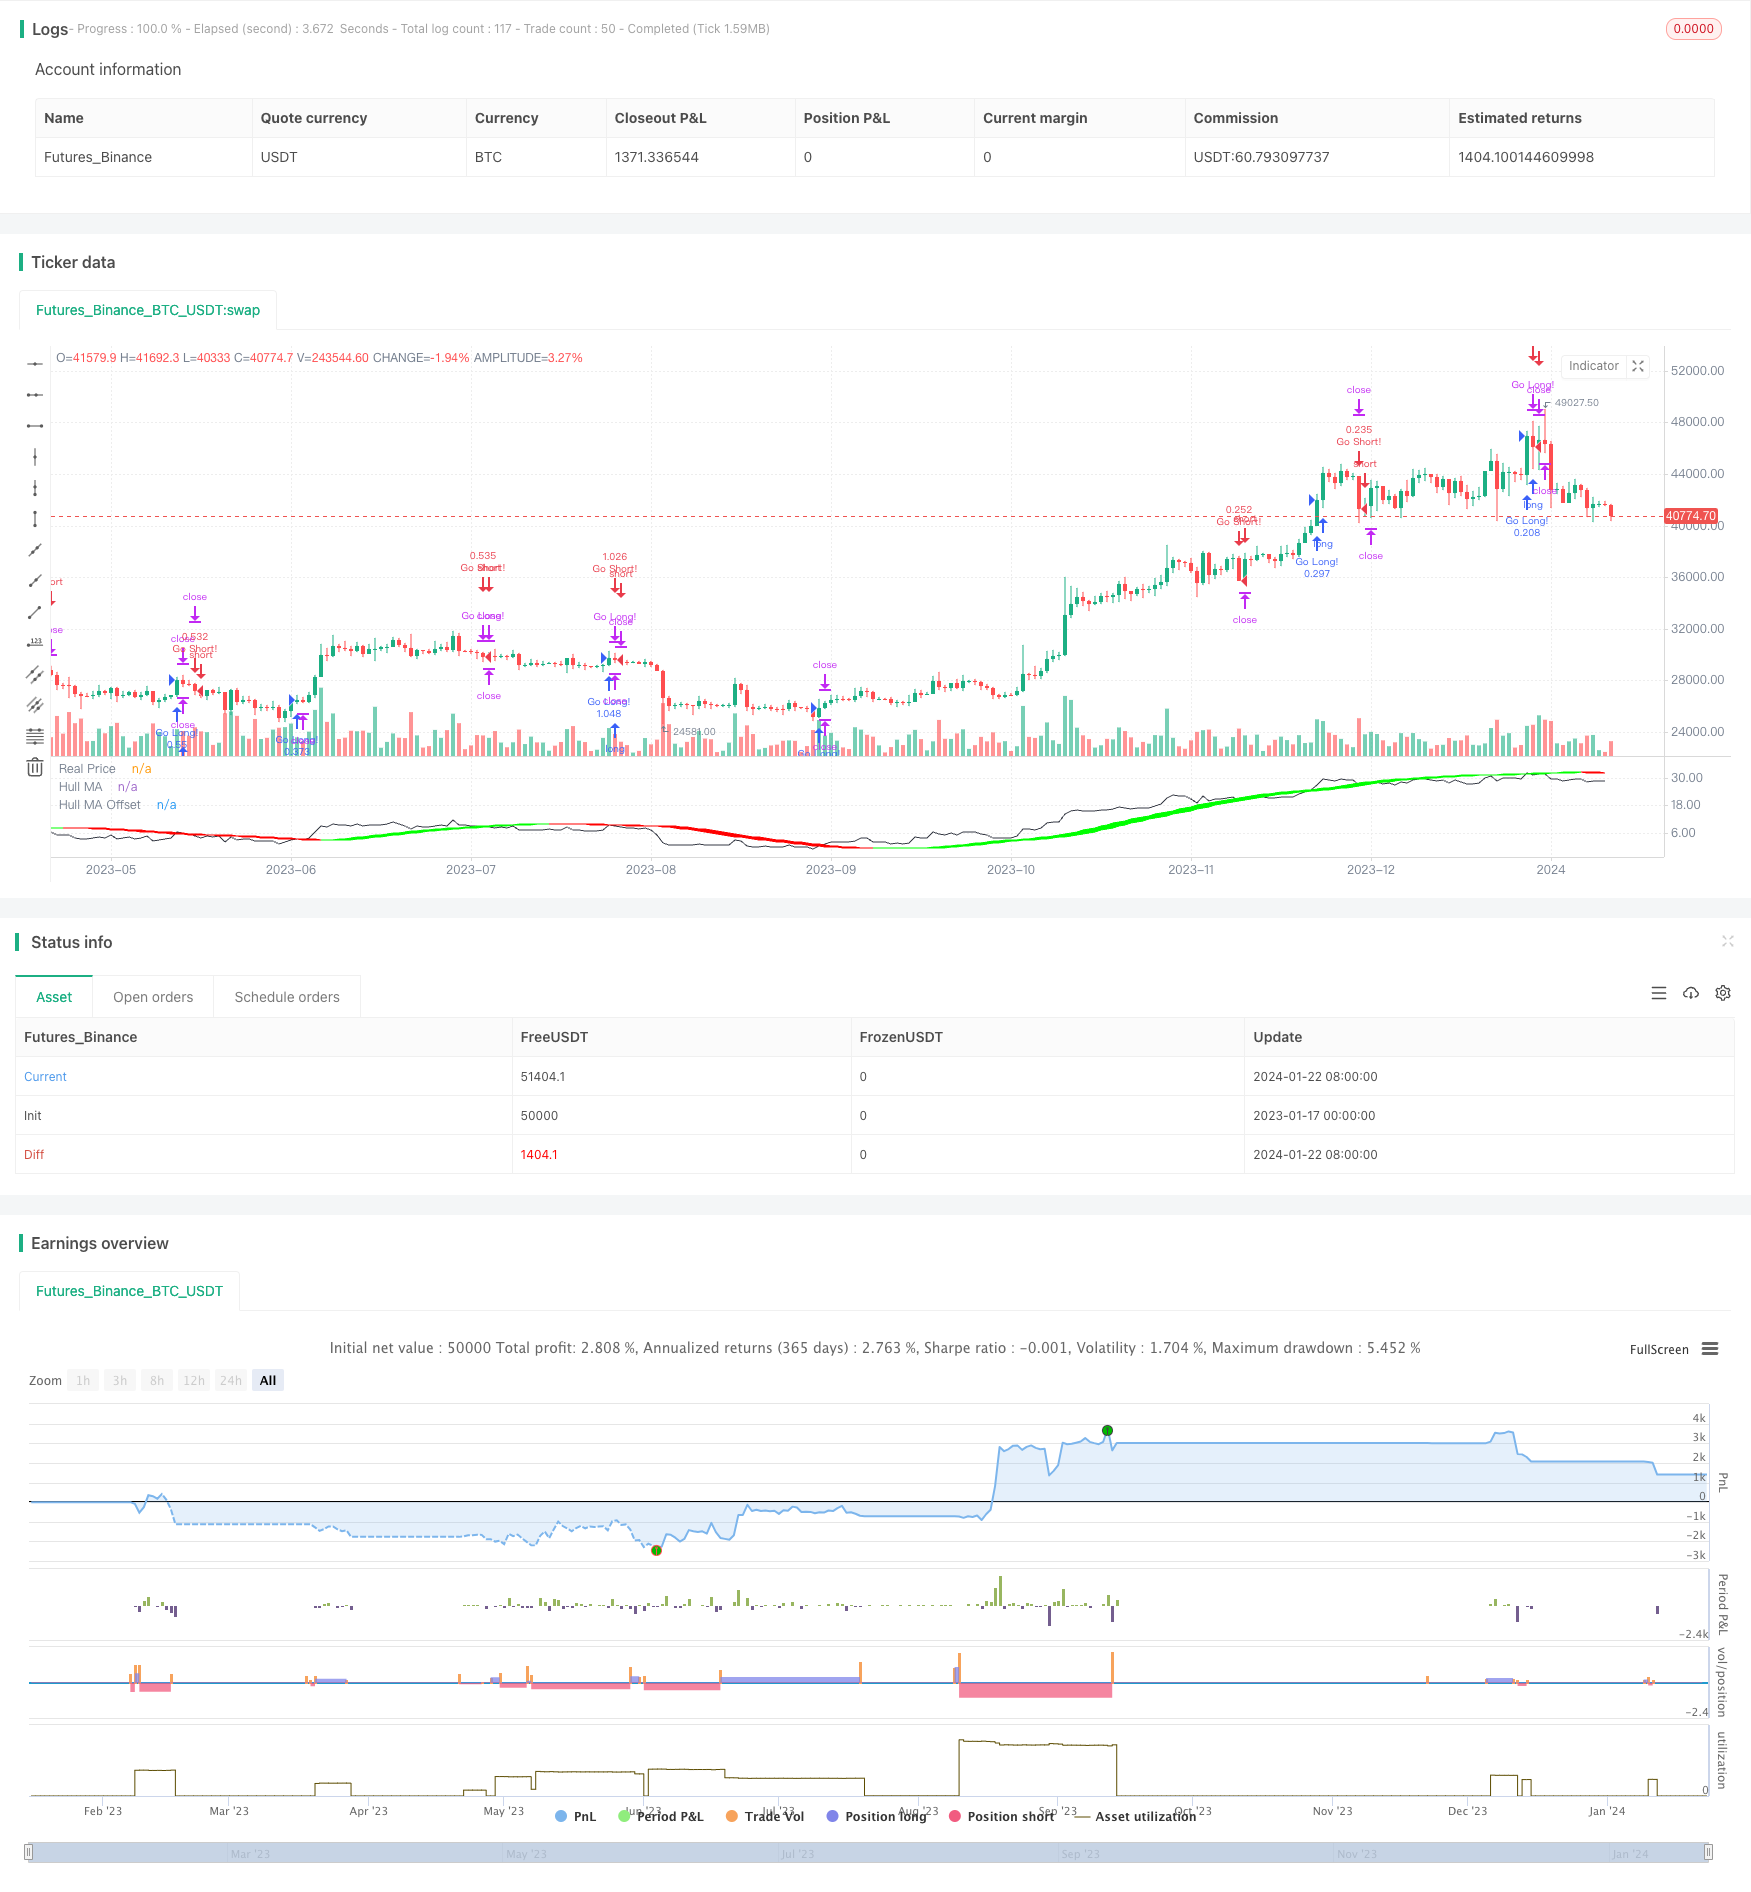
Overview
This unique systematic rulebased trading strategy is in the trend following category. It uses normalised prices series transformed from raw ticker price to gernerate trading signals. Advanced position sizing and risk management techniques, commonly reserved for institutional portfolio management, are utilised in this strategy - proven positioning and risk control technologies used by financial advisers like Commodity Trading Advisors and Managed Futures funds.
Strategy mechanics
The "normalised price" is a volatility-adjusted accumulated daily returns series. Daily volatility adjustment lookback is user defined. Hull moving average of the normalised price is used as the main trend indicator. Lookback period of the HMA is user defined too, with default period of 100 days for a responsive signal without inducing over-trading.
The core trades are simple, long when normalised price crossover HMA, short when crossunder HMA. New signals close any existing opposing position.
Position size is dynamically adjusted based on recent price volatility and the user defined annual risk target. Positions are risk-weighted, larger size with lower volatility and smaller with higher volatility. Recent volatility is the standard deviation of returns over the last 14 periods, then extrapolated into annual volatility as expeted returns. Annual risk target is used as reference for volatility adjusted position sizing. Default target is 10% of total capital. Initial capital should be set as maximum loss per trade. Max leverage allows achieving risk target if underlying natural volatility is insuffient, and alleviates excessively low volatility.
Hard stops are based on recent price average true range multiplier, user configurable.
Advantages
- Normalised prices reduces false signals
- Dynamic position sizing controls risk effectively
- Hard stops prevent runaway losses
- Simple trend following logic for transparency
Risks
- Lagging issues with Hull moving average
- Capping profits while lowering risk through volatility adjusted position sizing
- Stops too tight vulnerable to spikes
Risk controls measures include alternate moving average selections, adjusting risk targets.
Enhancements
- Test effectiveness of other moving average types
- Optimize parameters of moving averages
- Try long-only or short-only variants
- Fine tune stop loss ranges
- Experiment with other stop loss mechanisms
Conclusion
The strategy integrates various techniques like normalisation, dynamic position adjustment, hard stops to control risks. Trading is based on simple trend following rules. Parameters can be adjusted for personal preferences and market regimes. Worth further testing and verification for viable real world application.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | (?Strategy Settings)Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_int_1 | 14 | Lookback period for price normalisation filter |
| v_input_int_2 | 100 | Lookback period for Hull Moving Average |
| v_input_int_3 | false | HMA Offset |
| v_input_2 | true | Long |
| v_input_3 | true | Short |
| v_input_float_1 | true | (?Risk Management Settings)Stop multiple |
| v_input_float_2 | true | Max Leverage |
| v_input_float_3 | 10 | Annualised Volatility Target % |
| v_input_4 | false | Compounding |
| v_input_float_4 | 50 | % |
| v_input_int_4 | true | (?Backtest range)From Day |
| v_input_int_5 | true | From Mon |
| v_input_int_6 | 2018 | From Yr |
| v_input_int_7 | true | To Day |
| v_input_int_8 | true | To Mon |
| v_input_int_9 | 9999 | To Yr |
Source Pine Script
/*backtest
start: 2023-01-17 00:00:00
end: 2024-01-23 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Crunchster1

//@version=5
strategy(title="Crunchster's Normalised Trend Strategy", shorttitle="Normalised Trend Strategy", overlay=false )

// Inputs and Parameters
src = input(close, 'Source', group='Strategy Settings')
length = input.int(title="Lookback period for price normalisation filter", defval=14, minval=2, group='Strategy Settings', tooltip='This sets the lookback period for the volatility adjustment of returns, which is used to transform the price series into the "real price"')
hlength = input.int(title="Lookback period for Hull Moving Average", defval=100, minval=2, group='Strategy Settings')
offset = input.int(title="HMA Offset", defval=0, minval=0, group='Strategy Settings')
long = input(true, 'Long', inline='08', group='Strategy Settings')
short = input(true, 'Short', inline='08', group='Strategy Settings', tooltip='Toggle long/short strategy on/off')

stopMultiple = input.float(1, 'Stop multiple', step=0.25, group='Risk Management Settings', tooltip='Multiple for ATR, setting hard stop loss from entry price')
lev = input.float(1, 'Max Leverage', step=0.5, group='Risk Management Settings', tooltip='Max leverage sets maximum allowable leverage of total capital (initial capital + any net profit), capping maximum volatility adjusted position size')
riskT = input.float(10, maxval=75, title='Annualised Volatility Target %', group='Risk Management Settings', tooltip='Specify annual risk target, used to determine volatility adjusted position size. Annualised daily volatility is referenced to this value and position size adjusted accordingly')
comp = input(false, 'Compounding', inline='09', group='Risk Management Settings')
Comppct = input.float(50, '%', step=5, inline='09', group='Risk Management Settings', tooltip='Toggle compounding of profit, and set % of profit to compound')

// Backtesting period
FromDay = input.int(defval=1, title='From Day', minval=1, maxval=31, inline='04', group='Backtest range')
FromMonth = input.int(defval=1, title='From Mon', minval=1, maxval=12, inline='04', group='Backtest range')
FromYear = input.int(defval=2018, title='From Yr', minval=1900, inline='04', group='Backtest range', tooltip='Set start of backtesting period')
ToDay = input.int(defval=1, title='To Day', minval=1, maxval=31, inline='05', group='Backtest range')
ToMonth = input.int(defval=1, title='To Mon', minval=1, maxval=12, inline='05', group='Backtest range')
ToYear = input.int(defval=9999, title='To Yr', minval=1900, inline='05', group='Backtest range', tooltip='Set end of backtesting period')

start = timestamp(FromYear, FromMonth, FromDay, 00, 00)
finish = timestamp(ToYear, ToMonth, ToDay, 23, 59)
window = true

// Normalised returns calculation
nRet = (src - src[1]) / ta.stdev((src - src[1]), length)

nPrice = ta.cum(nRet)

//Hull Moving Average - using normalised price series
fHMA = ta.wma(2 * ta.wma(nPrice[offset], hlength / 2) - ta.wma(nPrice[offset], hlength), math.round(math.sqrt(hlength)))

//Risk Management formulae
strategy.initial_capital = 50000
tr = math.max(high - low, math.abs(high - close), math.abs(low - close)) //True range
stopL = ta.sma(tr, 14) //Average true range
stdev = ta.stdev(close-close[1], 14) //volatility of recent returns
maxcapital = strategy.initial_capital+strategy.netprofit //Maximum capital available to invest - initial capital net of profit
annvol = 100*math.sqrt(365)*stdev/close //converts recent volatility of returns into annualised volatility of returns - assumes daily timeframe

risk = 1.1
if comp
    risk := (strategy.initial_capital+(Comppct*strategy.netprofit/100))//adjust investment capital to include compounding
else
    risk := strategy.initial_capital

shares = (risk * (riskT/annvol)) / close //calculates volatility adjusted position size, dependent on user specified annualised risk target
if ((shares*close) > lev*maxcapital) //ensures position size does not exceed available capital multiplied by user specified maximum leverage
    shares := lev*maxcapital/close

//To set the price at the entry point of trade
Posopen() =>
    math.abs(strategy.position_size[1]) <= 0 and math.abs(strategy.position_size) > 0

var float openN = na
if Posopen()
    openN := stopL

// Strategy Rules
if long
    longCondition = ta.crossover(nPrice, fHMA) and window
    exitlong = ta.crossunder(nPrice, fHMA)
    if (longCondition)
        strategy.entry('Go Long!', strategy.long, qty=shares)
    if strategy.position_size > 0
        strategy.exit('Stop Long', from_entry = 'Go Long!', stop=(strategy.opentrades.entry_price(0) - (openN * stopMultiple)))
    if (exitlong)
        strategy.close('Go Long!', immediately = true)

if short
    shortCondition = ta.crossunder(nPrice, fHMA) and window
    exitshort = ta.crossover(nPrice, fHMA)
    if (shortCondition)
        strategy.entry('Go Short!', strategy.short, qty=shares)
    if strategy.position_size < 0
        strategy.exit('Stop Short', from_entry = 'Go Short!', stop=(strategy.opentrades.entry_price(0) + (openN * stopMultiple)))
    if (exitshort)
        strategy.close('Go Short!', immediately = true)

// Visuals of trend and direction
plot(nPrice, title='Real Price', color=color.black)

MAColor = fHMA > fHMA[3] ? #00ff00 : #ff0000
MA1 = plot(fHMA, title='Hull MA', color=MAColor)
MA2 = plot(fHMA[3], title='Hull MA Offset', color=MAColor)
fill(MA1, MA2, title='Band Filler', color=MAColor)Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynmaic-Risk-Adjusted-Momentum-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- Momentum Strategy Based on DEMA and EMA Crossover with ATR Volatility FilterPine Script · Momentum · 1h
- Momentum Trend Following SuperTrend and Stochastic Crossover StrategyPine Script · Momentum · 2d
- Momentum Trend Optimization Combination StrategyPine Script · Momentum · 1h
- Moving Average Candle Regression StrategyPine Script · Momentum · 15m
- Multi EMA Trend Momentum Trading Strategy with Risk Management SystemPine Script · Momentum · 1h