EHMA Range Strategy
This script is a modified version of @borserman's script for the Exponential Hull Moving Average All credit for the EHMA goes to him :) In addition to the EHMA, this script works with a range around the EHMA (which…
This script is a modified version of @borserman's script for the Exponential Hull Moving Average All credit for the EHMA goes to him :)
In addition to the EHMA, this script works with a range around the EHMA (which can be modified), in an attempt to be robust against fake signals. Many times a bar will close below a moving average, only to reverse again the next bar, which eats away at your profits. Especially on shorter timeframes, but also on choppy longer timeframes this can make a strategy unattractive to use.
With the range around the EHMA, the strategy only enters a long/exit-short position if a bar crosses above the upper range. Vice versa, it only enters a short/exit-long position if a bar crosses below the lower range. This avoids positions if bars behave choppy within the EHMA range & only enters a position if the market is confident in it's direction. Having said that, fakeouts are still possible, but a lot less frequent. Having backtested this strategy vs the regular EHMA strategy (and having experimented with various settings), this version seems to be a lot more robust & profitable!
Disclaimer Please remember that past performance may not be indicative of future results. Due to various factors, including changing market conditions, the strategy may no longer perform as good as in historical backtesting. This post and the script don't provide any financial advice.
backtest
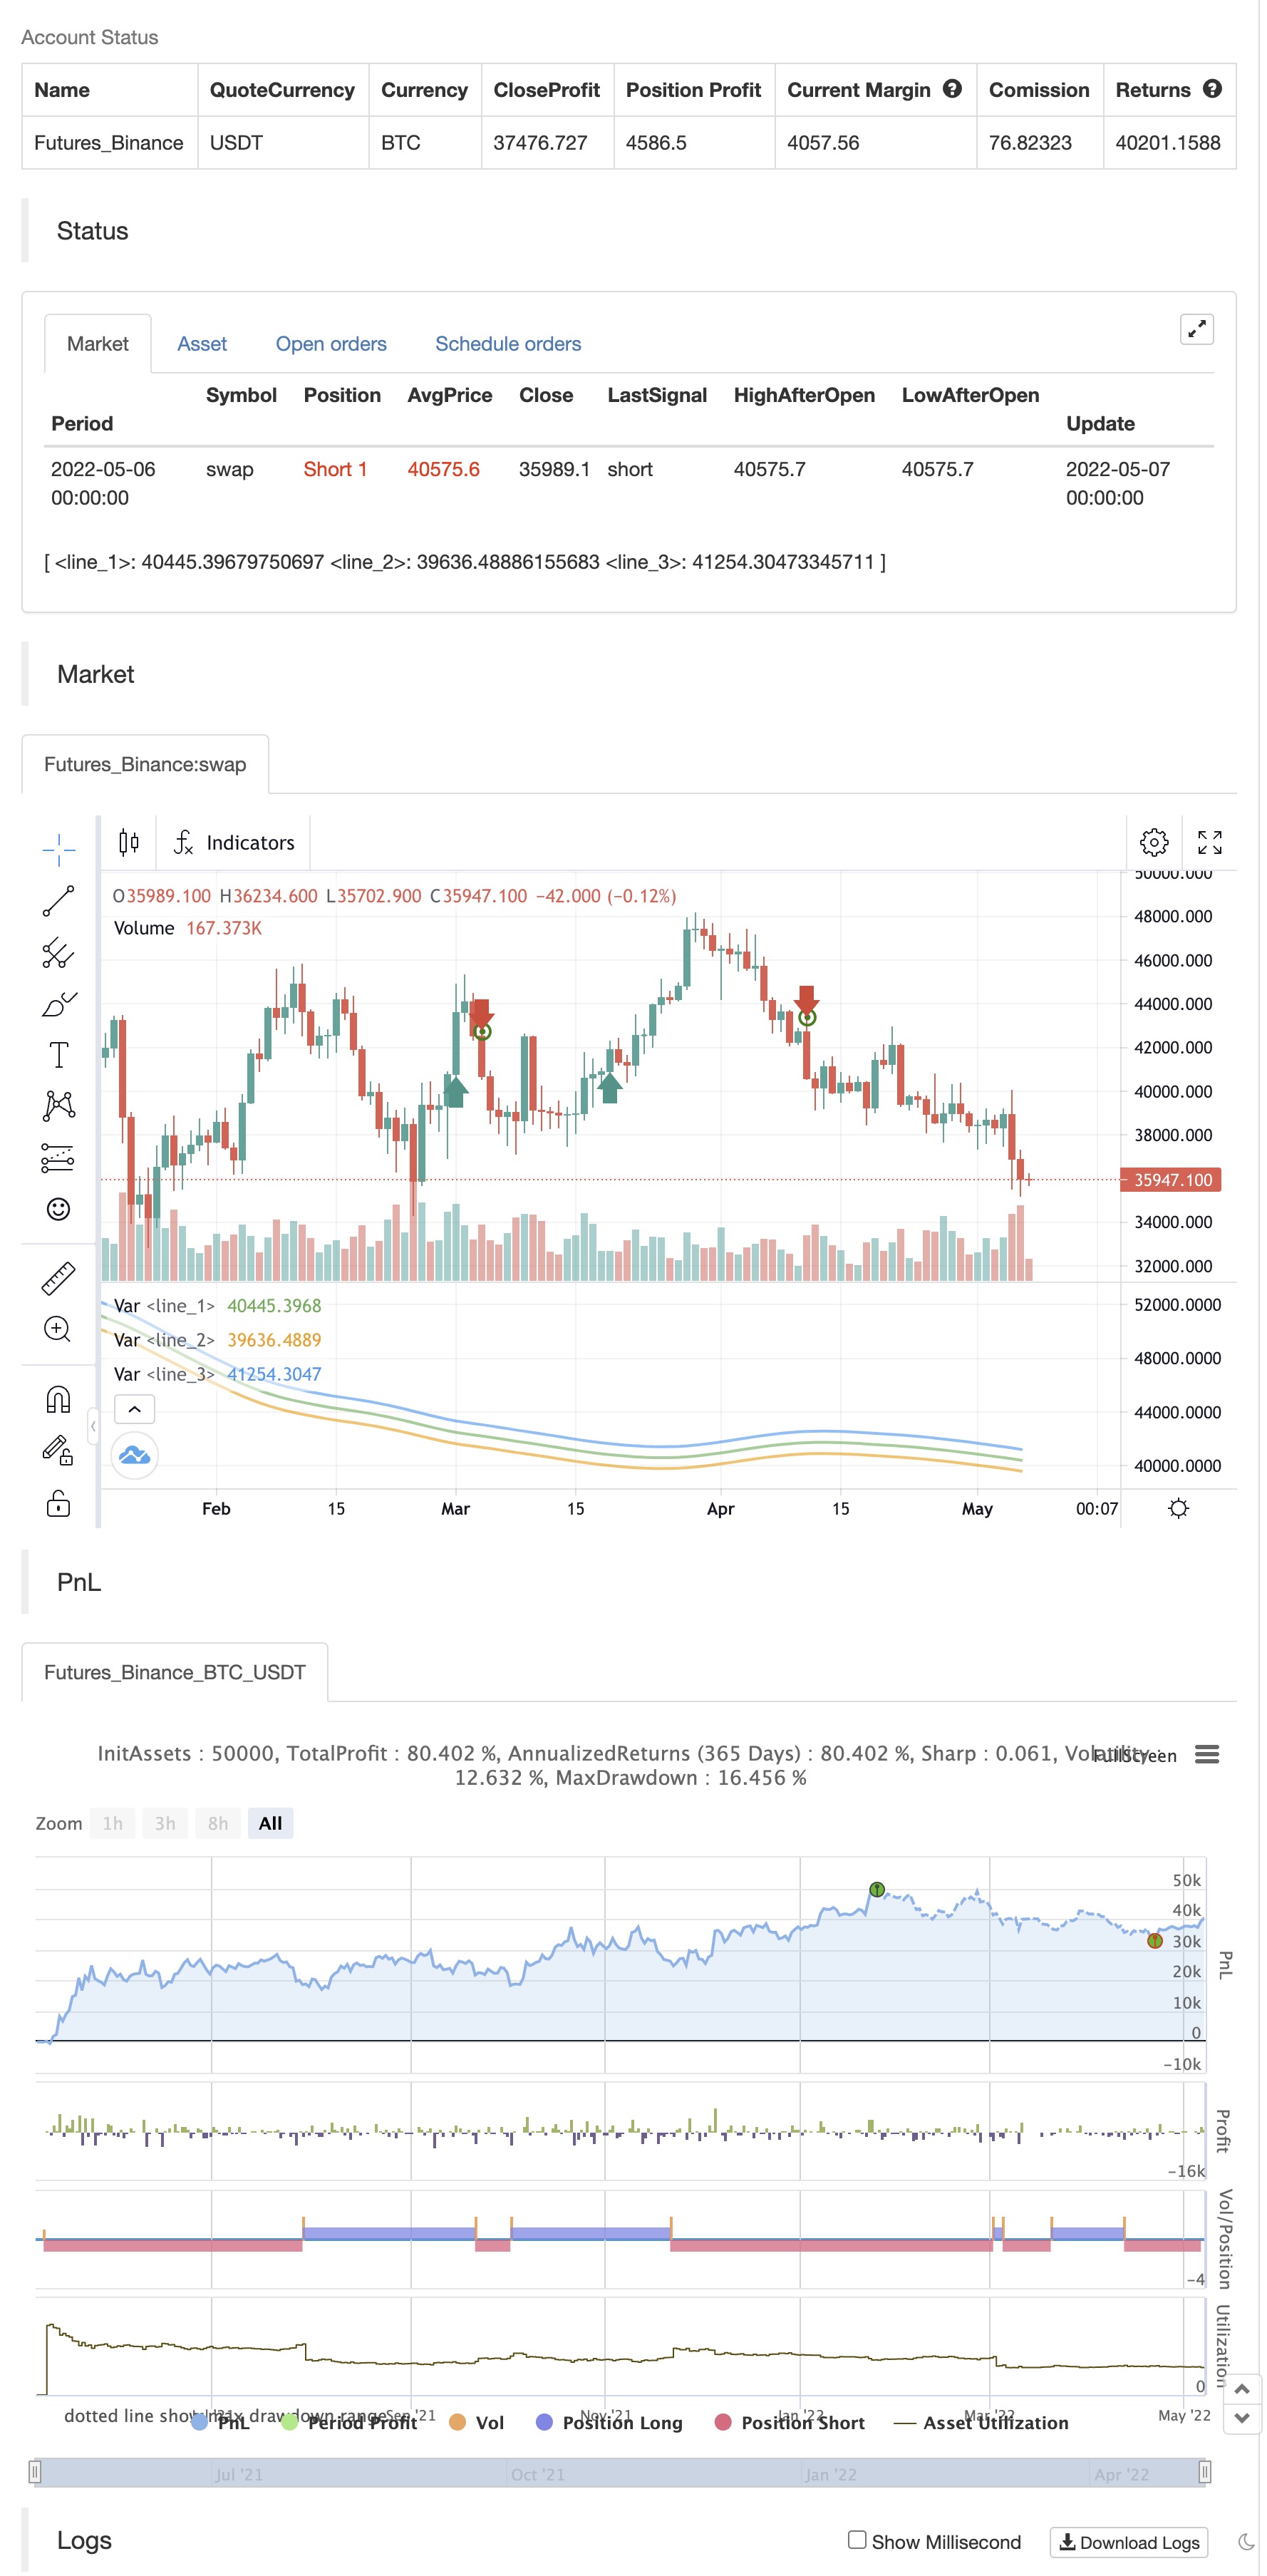
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0 | Position Type: Both | Long | Short |
| v_input_2 | 180 | Length |
| v_input_3 | 0.02 | Range Width |
Source Pine Script
/*backtest
start: 2021-05-08 00:00:00
end: 2022-05-07 23:59:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// Credit is due where credit is due:
// Hull Moving Average: developed by Alan Hull
// EHMA: coded by Twitter @borserman
// I've built on their work in an attempt to create a strategy more robust to fake moves
// @0xLetoII

//@version=4
//strategy(
//  title="EHMA Range Strategy",
//  process_orders_on_close=true,
//  explicit_plot_zorder=true,
//  overlay=true,
//  initial_capital=1500,
//  default_qty_type=strategy.percent_of_equity,
//  commission_type=strategy.commission.percent,
//  commission_value=0.085,
//  default_qty_value=100
//  )


// Position Type
pos_type = input(defval = "Both", title="Position Type", options=["Both", "Long", "Short"])

// Inputs
Period = input(defval=180, title="Length")
RangeWidth = input(defval=0.02, step=0.01, title="Range Width")
sqrtPeriod = sqrt(Period)

// Function for the Borserman EMA
borserman_ema(x, y) =>
    alpha = 2 / (y + 1)
    sum = 0.0
    sum := alpha * x + (1 - alpha) * nz(sum[1])

// Calculate the Exponential Hull Moving Average
EHMA = borserman_ema(2 * borserman_ema(close, Period / 2) - borserman_ema(close, Period), sqrtPeriod)

// Create upper & lower bounds around the EHMA for broader entries & exits
upper = EHMA + (EHMA * RangeWidth)
lower = EHMA - (EHMA * RangeWidth)

// Plots
EHMAcolor = (close > EHMA ? color.green : color.red)
plot(EHMA, color=EHMAcolor, linewidth=2)
plot(lower, color=color.orange, linewidth=2)
plot(upper, color=color.blue, linewidth=2)


// Strategy
long = close > upper
exit_long = close < lower
short = close < lower
exit_short = close > upper


// Calculate start/end date and time condition
//startDate  = input(timestamp("2017-01-01T00:00:00"))
//finishDate = input(timestamp("2029-01-01T00:00:00"))

time_cond  = true


// Entries & Exits
if pos_type == "Both"
    strategy.entry("Long", strategy.long, comment="Long", when=long and time_cond)
    strategy.close("Long", comment="Exit Long", when=exit_long and time_cond)
    strategy.entry("Short", strategy.short, comment="Short", when=short and time_cond)
    strategy.close("Short", comment="Exit Short", when=exit_short and time_cond)
if pos_type == "Long"
    strategy.entry("Long", strategy.long, comment="Long", when=long and time_cond)
    strategy.close("Long", comment="Exit Long", when=exit_long and time_cond)
if pos_type == "Short"
    strategy.entry("Short", strategy.short, comment="Short", when=short and time_cond)
    strategy.close("Short", comment="Exit Short", when=exit_short and time_cond)
Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-10. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/EHMA-Range-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.