Strategy vault / Trend following
EMA AROON ASH
=== IMPORTANT === My intention is to find the best strategies and dump the bad ones, as you can check by yourself using this automated strategy, the result is... BAD STRATEGY, AVOID === INTRO and CREDITS === This…
=== IMPORTANT === My intention is to find the best strategies and dump the bad ones, as you can check by yourself using this automated strategy, the result is... *** BAD STRATEGY, AVOID ***
=== INTRO and CREDITS === This script is a mix of 3 indicators in order to recreate TRADE KING's strategy from YouTube. First indicator is an EMA ( Exponential Moving Average ) (200 periods). Second is the classic Aroon indicator. And third is the Absolute Strength Histogram, the one by "jiehonglim", name is A"bsolute Strength Histogram v2 | jh". Credit for each indicator belongs to them, i just modified those to add some extra options, settings, etc, also updated all the code to PineScript 5.
=== THE STRATEGY === Default settings are already as TRADE KING requires, so you don't have to change anything. FOR LONGS (green background shows LONG entries).
- Price must be ABOVE the EMA .
- Bullish Aroon crossover.
- Bullish absolute strength histogram line must be ABOVE the bearish one.
FOR SHORTS (red background shows SHORT entries).
- Price must be BELOW the EMA .
- Bearish Aroon crossover.
- Bearish absolute strength histogram line must be ABOVE the bullish one.
Please check TRADE KING's YouTube channel for more info.
=== GENERAL IMPROVEMENTS === Upgrade to PineScript 5. Some performance improvements.
=== PERSONAL NOTES === The author of this strategy recommends 5M charts, however, 4H shows to be the best.
Thanks again to the authors of the indicators that compose this script and to TRADE KING to create this strategy.
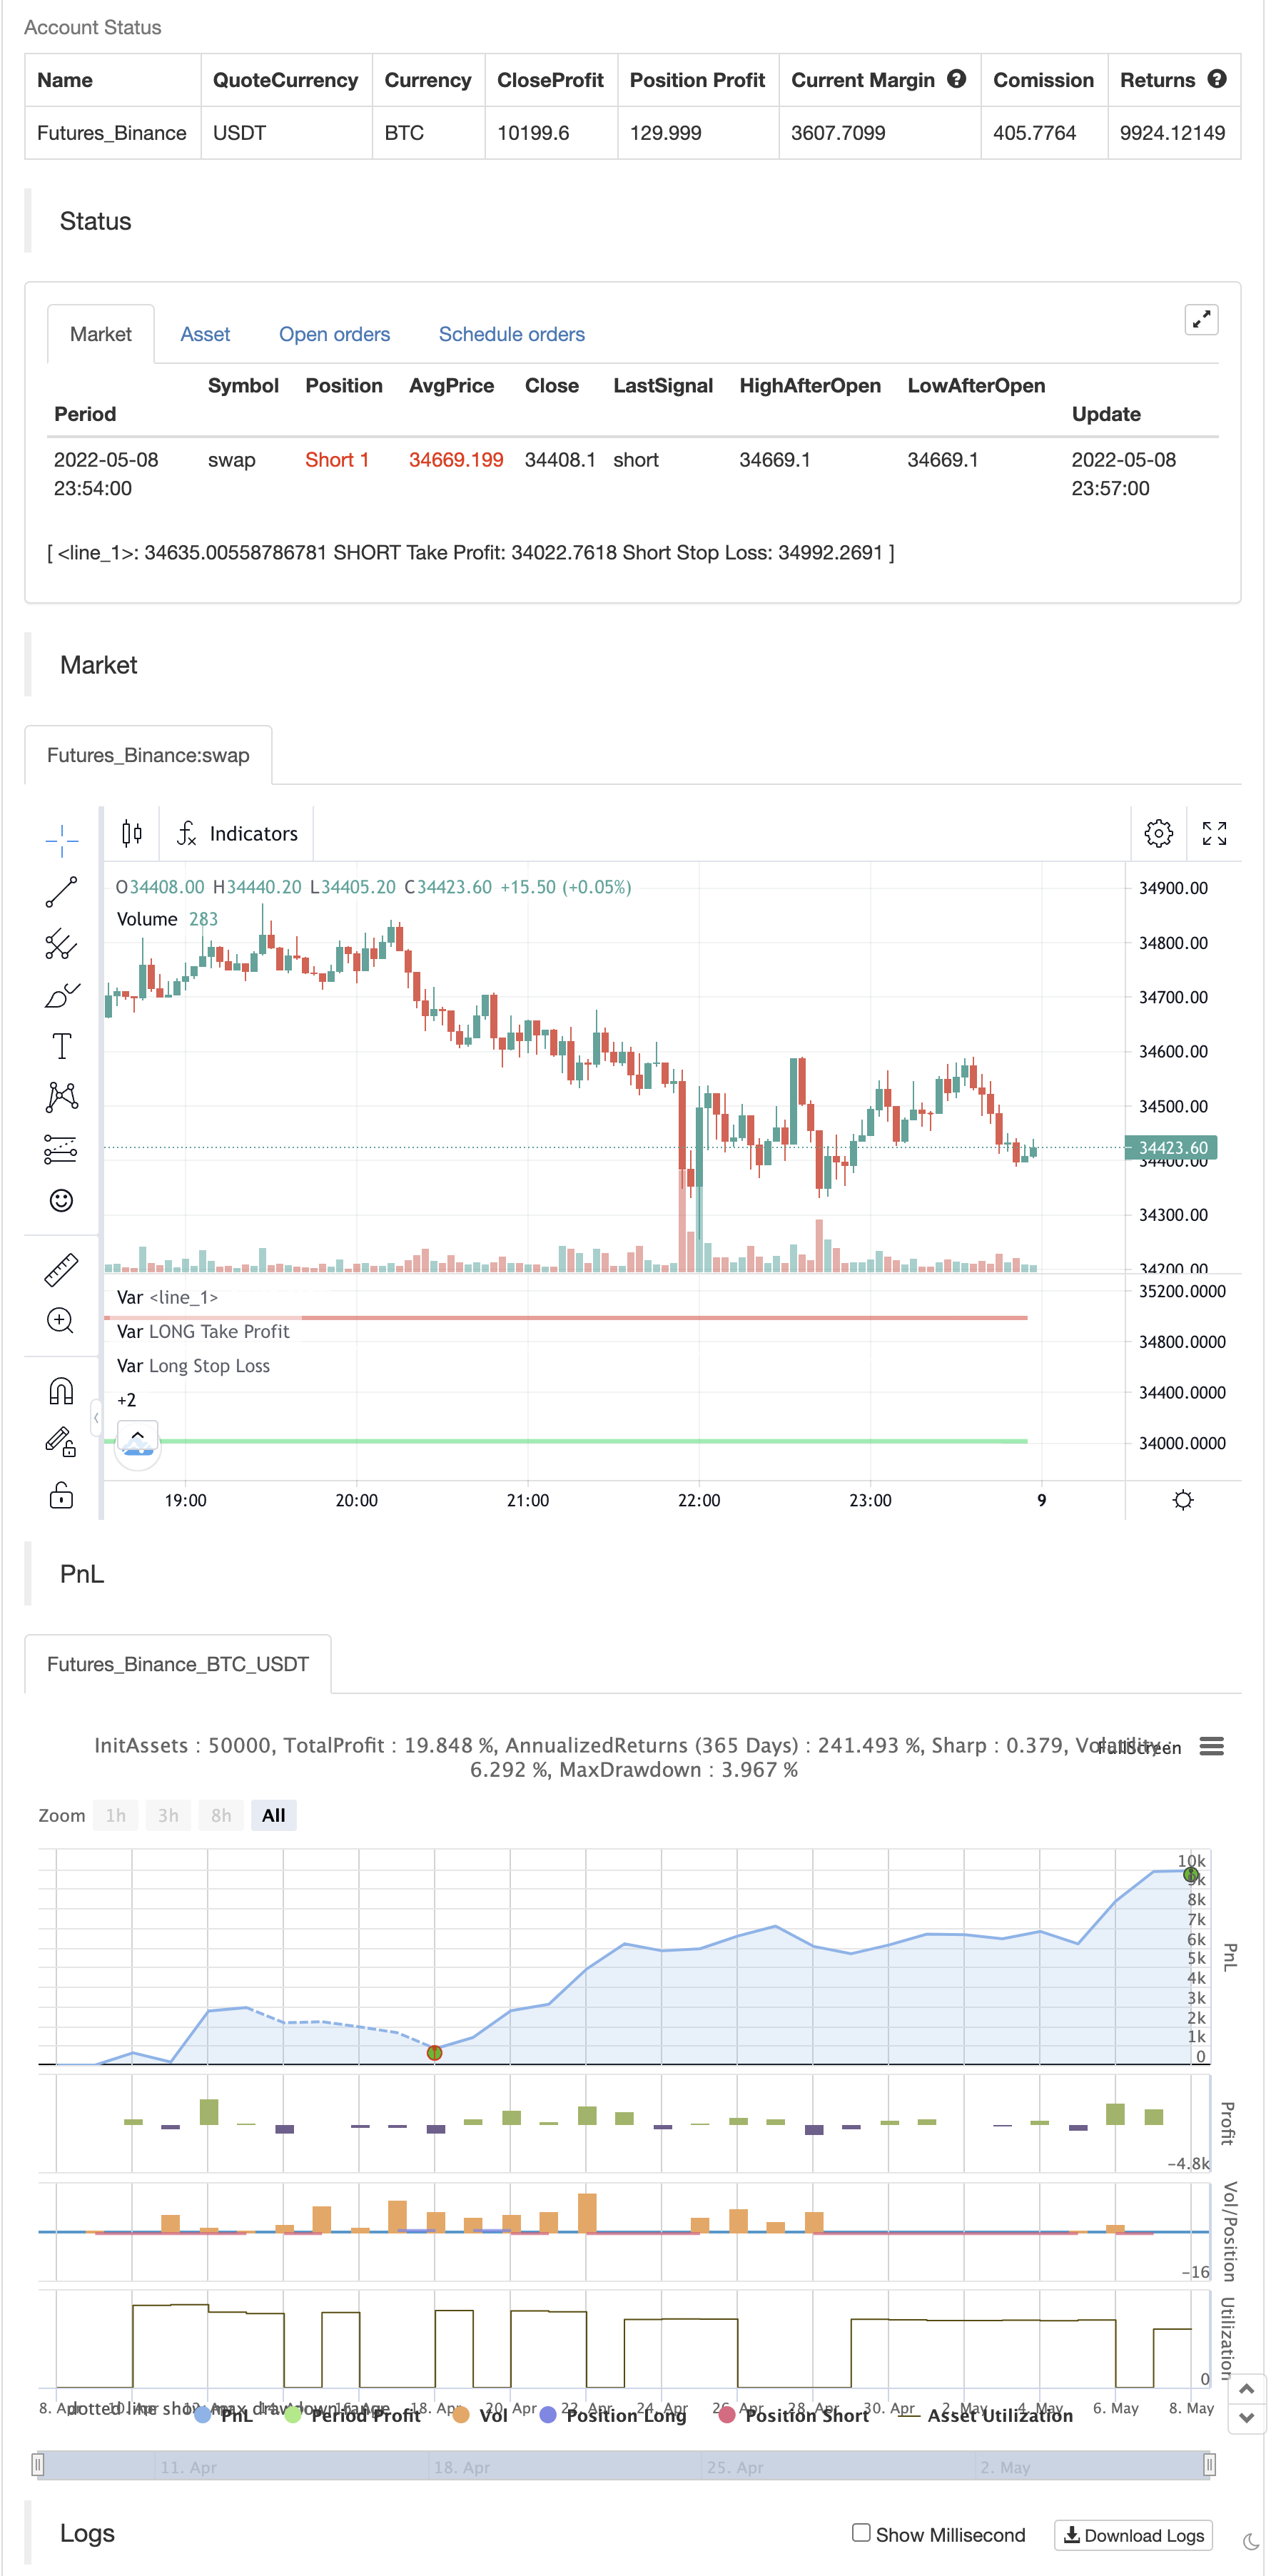
backtest
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_4_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_string_1 | 0 | Indicator Method: RSI | STOCHASTIC | ADX |
| v_input_string_2 | 0 | MA: WMA | EMA | ALMA | SMA | SMMA | HMA |
| v_input_float_2 | 0.85 | * Arnaud Legoux (ALMA) Only - Offset Value |
| v_input_int_4 | 6 | * Arnaud Legoux (ALMA) Only - Sigma Value |
| v_input_bool_1 | true | (?Positions)¿LONGS? |
| v_input_bool_2 | true | ¿SHORTS? |
| v_input_int_1 | 20 | (?TP y SL)• SL lookback for pivot / Mult. TP |
| v_input_float_1 | 2 | TPSL_SL_mult |
| v_input_int_2 | 200 | (?Exponential Moving Average (EMA))Length |
| v_input_1_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_int_3 | 20 | (?Aroon)• Length |
| v_input_2 | 9 | (?Absolute Strength Histogram v2 | jh)Period of Evaluation |
| v_input_3 | 3 | Period of Smoothing |
Source Pine Script
/*backtest
start: 2022-04-09 00:00:00
end: 2022-05-08 23:59:00
period: 3m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/


// © JoseMetal
//@version=5

//

//== Constantes
c_verde_radiactivo = color.rgb(0, 255, 0, 0)
c_verde            = color.rgb(0, 128, 0, 0)
c_verde_oscuro     = color.rgb(0, 80, 0, 0)
c_rojo_radiactivo  = color.rgb(255, 0, 0, 0)
c_rojo             = color.rgb(128, 0, 0, 0)
c_rojo_oscuro      = color.rgb(80, 0, 0, 0)


//== Funciones


//== Declarar estrategia y período de testeo
//strategy("EMA + AROON + ASH (TRADE KING's STRATEGY)", shorttitle="EMA + AROON + ASH (TRADE KING's STRATEGY)", overlay=true, initial_capital=10000, pyramiding=0, default_qty_value=10, default_qty_type=strategy.percent_of_equity, commission_type=strategy.commission.percent, commission_value=0.00075, max_labels_count=500, max_bars_back=1000)
//fecha_inicio     = input.time(timestamp("1 Jan 2000"), title="• Start date", group="Test period", inline="periodo_de_pruebas")
vela_en_fecha    = true
posicion_abierta = strategy.position_size != 0
LONG_abierto     = strategy.position_size > 0
SHORT_abierto    = strategy.position_size < 0

//== Condiciones de entrada y salida de estrategia
GRUPO_P           = "Positions"
P_permitir_LONGS  = input.bool(title="¿LONGS?", group=GRUPO_P, defval=true)
P_permitir_SHORTS = input.bool(title="¿SHORTS?", group=GRUPO_P, defval=true)

GRUPO_TPSL   = "TP y SL"
TPSL_TP_pivot_lookback = input.int(title="• SL lookback for pivot / Mult. TP", group=GRUPO_TPSL, defval=20, minval=1, step=1, inline="tp_sl")
TPSL_SL_mult = input.float(title="", group=GRUPO_TPSL, defval=2.0, minval=0.1, step=0.2, inline="tp_sl")


//== Inputs de indicadores
// EMA
GRUPO_EMA  = "Exponential Moving Average (EMA)"
EMA_length = input.int(200, minval=1, title="Length", group=GRUPO_EMA)
EMA_src    = input(close, title="Source", group=GRUPO_EMA)
EMA = ta.ema(EMA_src, EMA_length)

// Aroon
GRUPO_Aroon = "Aroon"
Aroon_length = input.int(title="• Length", group=GRUPO_Aroon, defval=20, minval=1)
Aroon_upper = 100 * (ta.highestbars(high, Aroon_length+1) + Aroon_length) / Aroon_length
Aroon_lower = 100 * (ta.lowestbars(low, Aroon_length+1) + Aroon_length) / Aroon_length

// ASH
GRUPO_ASH = "Absolute Strength Histogram v2 | jh"
ASH_Length = input(9, title='Period of Evaluation', group=GRUPO_ASH)
ASH_Smooth = input(3, title='Period of Smoothing', group=GRUPO_ASH)
ASH_src = input(close, title='Source')
ASH_Mode = input.string(title='Indicator Method', defval='RSI', options=['RSI', 'STOCHASTIC', 'ADX'])
ASH_ma_type = input.string(title='MA', defval='WMA', options=['ALMA', 'EMA', 'WMA', 'SMA', 'SMMA', 'HMA'])
ASH_alma_offset = input.float(defval=0.85, title='* Arnaud Legoux (ALMA) Only - Offset Value', minval=0, step=0.01)
ASH_alma_sigma = input.int(defval=6, title='* Arnaud Legoux (ALMA) Only - Sigma Value', minval=0)

_MA(type, src, len) =>
    float result = 0
    if type == 'SMA'  // Simple
        result := ta.sma(src, len)
        result
    if type == 'EMA'  // Exponential
        result := ta.ema(src, len)
        result
    if type == 'WMA'  // Weighted
        result := ta.wma(src, len)
        result
    if type == 'SMMA'  // Smoothed
        w = ta.wma(src, len)
        result := na(w[1]) ? ta.sma(src, len) : (w[1] * (len - 1) + src) / len
        result
    if type == 'HMA'  // Hull
        result := ta.wma(2 * ta.wma(src, len / 2) - ta.wma(src, len), math.round(math.sqrt(len)))
        result
    if type == 'ALMA'  // Arnaud Legoux
        result := ta.alma(src, len, ASH_alma_offset, ASH_alma_sigma)
        result
    result

Price1 = _MA('SMA', ASH_src, 1)
Price2 = _MA('SMA', ASH_src[1], 1)

// RSI
Bulls0 = 0.5 * (math.abs(Price1 - Price2) + Price1 - Price2)
Bears0 = 0.5 * (math.abs(Price1 - Price2) - (Price1 - Price2))

// STOCHASTIC
Bulls1 = Price1 - ta.lowest(Price1, ASH_Length)
Bears1 = ta.highest(Price1, ASH_Length) - Price1

// ADX
Bulls2 = 0.5 * (math.abs(high - high[1]) + high - high[1])
Bears2 = 0.5 * (math.abs(low[1] - low) + low[1] - low)

Bulls = ASH_Mode == 'RSI' ? Bulls0 : ASH_Mode == 'STOCHASTIC' ? Bulls1 : Bulls2
Bears = ASH_Mode == 'RSI' ? Bears0 : ASH_Mode == 'STOCHASTIC' ? Bears1 : Bears2
AvgBulls = _MA(ASH_ma_type, Bulls, ASH_Length)
AvgBears = _MA(ASH_ma_type, Bears, ASH_Length)

SmthBulls = _MA(ASH_ma_type, AvgBulls, ASH_Smooth)
SmthBears = _MA(ASH_ma_type, AvgBears, ASH_Smooth)

difference = math.abs(SmthBulls - SmthBears)


//== Cálculo de condiciones
EMA_alcista = close > EMA
EMA_bajista = close < EMA
Aroon_cruce_alcista = ta.crossover(Aroon_upper, Aroon_lower)
Aroon_cruce_bajista = ta.crossunder(Aroon_upper, Aroon_lower)
ASH_alcista = SmthBulls > SmthBears
ASH_bajista = SmthBulls < SmthBears

//== Entrada (deben cumplirse todas para entrar)
longCondition1  = EMA_alcista
longCondition2  = Aroon_cruce_alcista
longCondition3  = ASH_alcista
long_conditions = longCondition1 and longCondition2 and longCondition3
entrar_en_LONG  = P_permitir_LONGS and long_conditions and vela_en_fecha and not posicion_abierta

shortCondition1  = EMA_bajista
shortCondition2  = Aroon_cruce_bajista
shortCondition3  = ASH_bajista
short_conditions = shortCondition1 and shortCondition2 and shortCondition3
entrar_en_SHORT  = P_permitir_SHORTS and short_conditions and vela_en_fecha and not posicion_abierta

var LONG_stop_loss    = 0.0
var LONG_take_profit  = 0.0
var SHORT_stop_loss   = 0.0
var SHORT_take_profit = 0.0

//psl = ta.pivotlow(TPSL_TP_pivot_lookback, TPSL_TP_pivot_lookback)
//psh = ta.pivothigh(TPSL_TP_pivot_lookback, TPSL_TP_pivot_lookback)
psl = ta.lowest(TPSL_TP_pivot_lookback)
psh = ta.highest(TPSL_TP_pivot_lookback)

if (entrar_en_LONG)
    LONG_stop_loss   := psl - close*0.001
    LONG_take_profit := close + ((close - LONG_stop_loss) * TPSL_SL_mult)
    strategy.entry("+ Long", strategy.long)
    strategy.exit("- Long", "+ Long", limit=LONG_take_profit, stop=LONG_stop_loss)

if (entrar_en_SHORT)
    SHORT_stop_loss   := psh + close*0.001
    SHORT_take_profit := close - ((SHORT_stop_loss - close) * TPSL_SL_mult)
    strategy.entry("+ Short", strategy.short)
    strategy.exit("- Short", "+ Short", limit=SHORT_take_profit, stop=SHORT_stop_loss)


//== Ploteo en pantalla
// EMA
plot(EMA, color=color.white, linewidth=2)

// Símbolo de entrada (entre o no en compra)
bgcolor = color.new(color.black, 100)

if (entrar_en_LONG or entrar_en_SHORT)
    bgcolor := color.new(color.green, 90)

bgcolor(bgcolor)

// Precio de compra, Take Profit, Stop Loss y relleno
avg_position_price_plot = plot(series=posicion_abierta ? strategy.position_avg_price : na, color=color.new(color.white, 25), style=plot.style_linebr, linewidth=2, title="Precio Entrada")

LONG_tp_plot            = plot(LONG_abierto and LONG_take_profit > 0.0 ? LONG_take_profit : na, color=color.new(color.lime, 25), style=plot.style_linebr, linewidth=3, title="LONG Take Profit")
LONG_sl_plot            = plot(LONG_abierto and LONG_stop_loss > 0.0 ? LONG_stop_loss : na, color=color.new(color.red, 25), style=plot.style_linebr, linewidth=3, title="Long Stop Loss")
fill(avg_position_price_plot, LONG_tp_plot, color=color.new(color.olive, 85))
fill(avg_position_price_plot, LONG_sl_plot, color=color.new(color.maroon, 85))

SHORT_tp_plot            = plot(SHORT_abierto and SHORT_take_profit > 0.0 ? SHORT_take_profit : na, color=color.new(color.lime, 25), style=plot.style_linebr, linewidth=3, title="SHORT Take Profit")
SHORT_sl_plot            = plot(SHORT_abierto and SHORT_stop_loss > 0.0 ? SHORT_stop_loss : na, color=color.new(color.red, 25), style=plot.style_linebr, linewidth=3, title="Short Stop Loss")
fill(avg_position_price_plot, SHORT_tp_plot, color=color.new(color.olive, 85))
fill(avg_position_price_plot, SHORT_sl_plot, color=color.new(color.maroon, 85))
Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-10. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/EMA-AROON-ASH.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- Trend Tracking and Short term Trading Strategy Based on ADX IndicatorPine Script · Trend following · 1d
- Multi Period Trend Confirmation Dynamic Risk Control Quantitative Trading StrategyPine Script · Trend following · 1h
- Multi indicator Adaptive Trend Trading StrategyPine Script · Trend following · 1d
- Trend Following Strategy Based on Multiple IndicatorsPine Script · Trend following · 2h
- WaveTrend and DER Based Swing Trading StrategyPine Script · Trend following · 1d