Strategy vault / Machine learning
EMA Candle Close Strategy
This strategy generates trading signals based on the golden cross and dead cross of moving averages. It incorporates three moving averages with different parameter settings - short-term, medium-term and long-term…
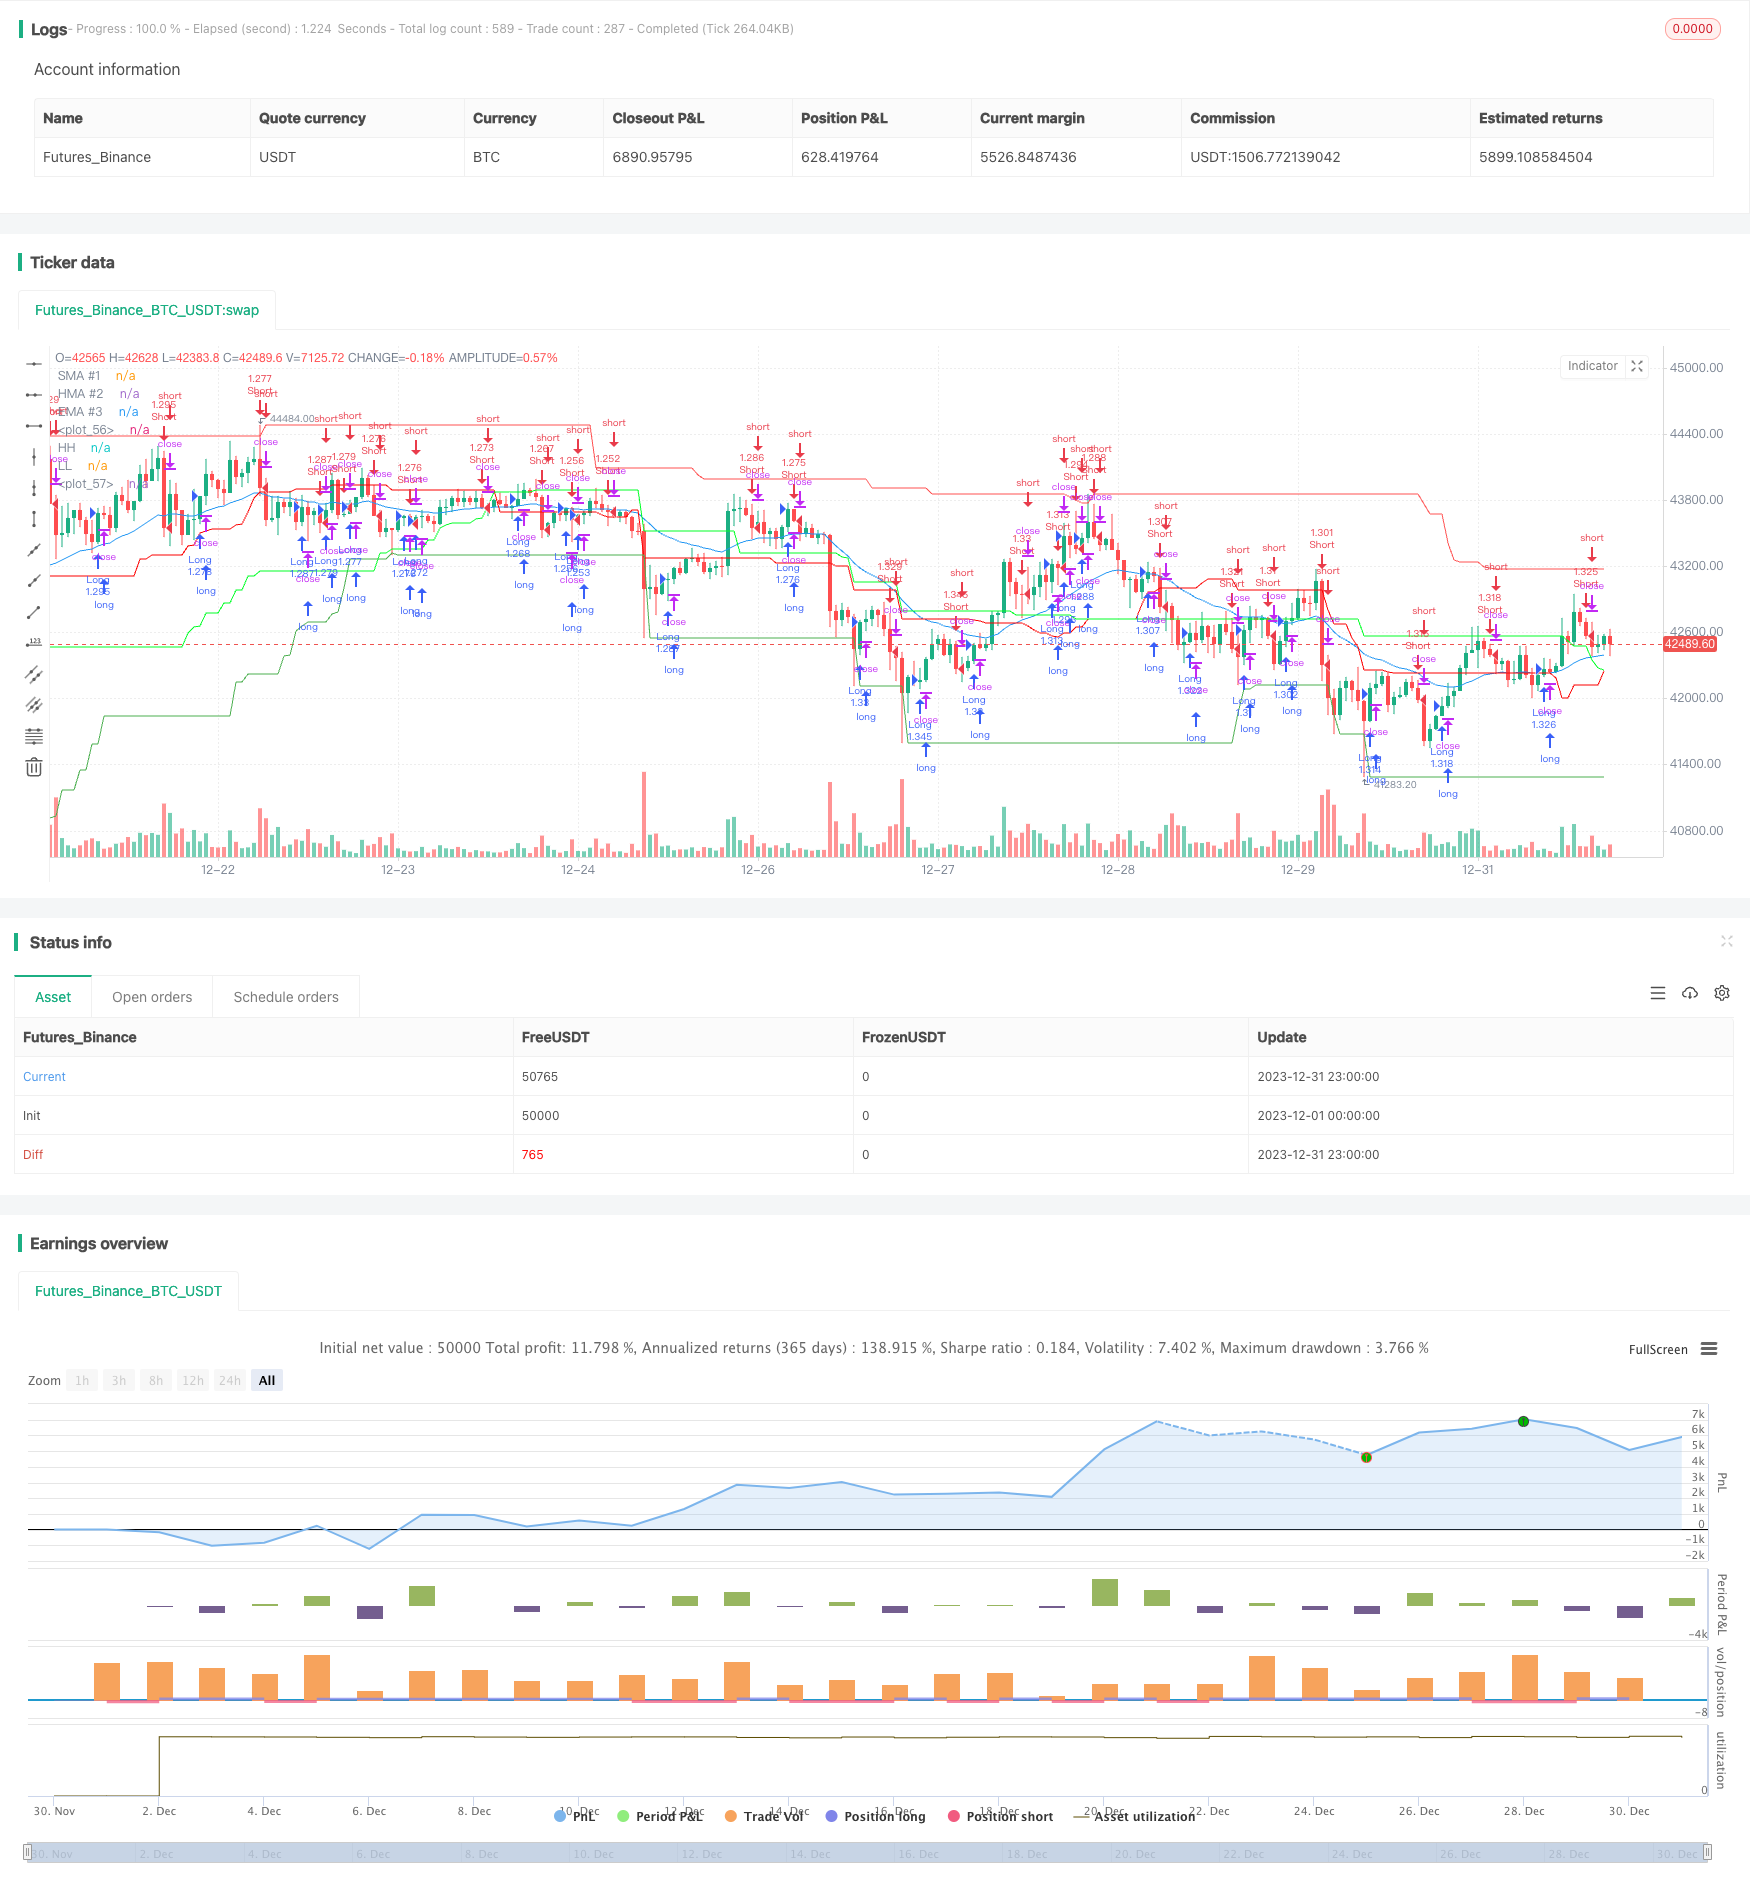
Overview
This strategy generates trading signals based on the golden cross and dead cross of moving averages. It incorporates three moving averages with different parameter settings - short-term, medium-term and long-term ones. By comparing the height relationship among these three MAs, it determines the bullish/bearish state of the market and produces trading signals.
Strategy Principle
The strategy sets three moving average lines, which are a short-term simple moving average, a medium-term weighted moving average and a long-term exponential moving average. Specifically, it sets a 1-period SMA, a 20-period WMA and a 25-period EMA.
When the short-term SMA line crosses over the medium-term WMA line upwardly and the closing price is also higher than the WMA line, it indicates the market is reversing upward and forms a bullish signal. When the short-term SMA crosses below the medium-term WMA or the closing price is lower than the WMA, it gives a bearish signal. Therefore, this strategy judges the bullish/bearish state of the market by comparing the height and crossover among the three MAs.
Advantage Analysis
The strategy incorporates three MAs of short, medium and long terms, which can react to market changes in different cycles and improve the accuracy of capturing trends. Especially, the medium-term WMA has a better effect of filtering out market noise and avoids wrong signals effectively. In addition, the strategy only sends long signals when the bullish signals of SMA and closing price reach high consistency, which prevents whipsaws and ensures every entry efficient.
Risk Analysis
The strategy has the risk of false signals. When the short-term SMA produces wrong signals, unnecessary losses may be caused due to the strategy's strict dependence on the SMA line. Also, the strategy is sensitive to parameters. When parameters are set improperly under range-bound markets, many wrong trades can be triggered.
To prevent such risks, it's suggested to adjust the MA lengths, properly loosen trading conditions and set stop loss to limit single loss. When the market trend is unclear, the strategy can be stopped temporarily.
Optimization Directions
The strategy can be optimized from the following aspects:
Incorporate more types of MAs like KC to form an indicator portfolio to improve accuracy
Add volume factors like breakout with high volume
Combine volatility indicators to avoid failure in choppy markets
Employ machine learning to train and optimize parameters
Conclusion
The strategy determines market bullish/bearish status based on the crossover and height relationship among three MAs and closing prices. By combining MAs of different terms, it can effectively discover trends and the signals are of high quality. With proper parameter tuning and introducing more auxiliary indicators, the strategy can be further enhanced in pertinence and stability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | true | SMA #1 Length |
| v_input_1_close | 0 | SMA Source #1: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_int_2 | 20 | HMA #2 Length |
| v_input_2_close | 0 | HMA Source #2: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_int_3 | 25 | EMA #3 Length |
| v_input_3_close | 0 | EMA Source #3: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_4 | 55 | Period Look Back |
| v_input_5 | 40 | Short Length |
| v_input_6 | 80 | Long Length |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("EMA Candle Close Strategy KHANH 11/11/2023", overlay=true, initial_capital=100, commission_type=strategy.commission.percent, commission_value=0.0000005, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

len1 = input.int(1, title="SMA #1 Length", minval=1)
src1 = input(close, title="SMA Source #1")
out1 = ta.sma(src1, len1)
plot(out1, title="SMA #1", color=close >= out1 ? color.rgb(120, 123, 134, 100) : color.rgb(120, 123, 134, 100), linewidth=1)

len2 = input.int(20, title="HMA #2 Length", minval=1)
src2 = input(close, title="HMA Source #2")
out2 = ta.hma(src2, len2)
plot(out2, title="HMA #2", color=close >= out2 ? color.rgb(253, 255, 254, 100) : color.rgb(255, 255, 255, 100), linewidth=1)

len3 = input.int(25, title="EMA #3 Length", minval=1)
src3 = input(close, title="EMA Source #3")
out3 = ta.ema(src3, len3)
plot(out3, title="EMA #3", color=close >= out3 ? color.blue : color.blue, linewidth=1)

// Define the long condition
longCondition = (out1 > out2 and close > out2)

// Define the short condition
shortCondition = (out1 < out2 or close < out2)

// Entry conditions
if (longCondition)
    strategy.entry("Long",strategy.long)
else if (shortCondition)
    strategy.entry("Short", strategy.short)

// Trade channel plot
PeriodLookBack = input(55, title="Period Look Back")
xHighest55 = request.security(syminfo.tickerid, timeframe.period, ta.highest(PeriodLookBack))
xLowest55 = request.security(syminfo.tickerid, timeframe.period, ta.lowest(PeriodLookBack))
plot(xHighest55[1], color=color.red, title="HH")
plot(xLowest55[1], color=color.green, title="LL")


//@version=5
//indicator("Custom Moving Averages", shorttitle="CMA", overlay=true)

shortLength = input(defval=40, title="Short Length")
longLength = input(defval=80, title="Long Length")

// Sử dụng khung thời gian của biểu đồ đang sử dụng thay vì cố định là "D"
shortTopBorder = request.security(syminfo.tickerid, timeframe.period, ta.highest(high, shortLength))
shortBottomBorder = request.security(syminfo.tickerid, timeframe.period, ta.lowest(low, shortLength))

longTopBorder = request.security(syminfo.tickerid, timeframe.period, ta.highest(high, longLength))
longBottomBorder = request.security(syminfo.tickerid, timeframe.period, ta.lowest(low, longLength))

shortAverageLine = (shortTopBorder + shortBottomBorder) / 2
longAverageLine = (longTopBorder + longBottomBorder) / 2

plot(shortAverageLine, color=color.new(#fc0000, 0))
plot(longAverageLine, color=color.new(#01ff27, 0))
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/EMA-Candle-Close-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- Dual Moving Average Matching Strategy Based on Bollinger BandsPine Script · Machine learning · 1h
- Dynamic Weighted Moving Average Trading StrategyPine Script · Machine learning · 1d
- EMA and RSI Quantitative Trading StrategyPine Script · Machine learning · 1h
- MACD Robot Trading StrategyPine Script · Machine learning · 1d
- Multi Indicator Dynamic Adaptive Quantitative Trading StrategyPine Script · Machine learning · 1h