EMA Cloud Intraday Strategy
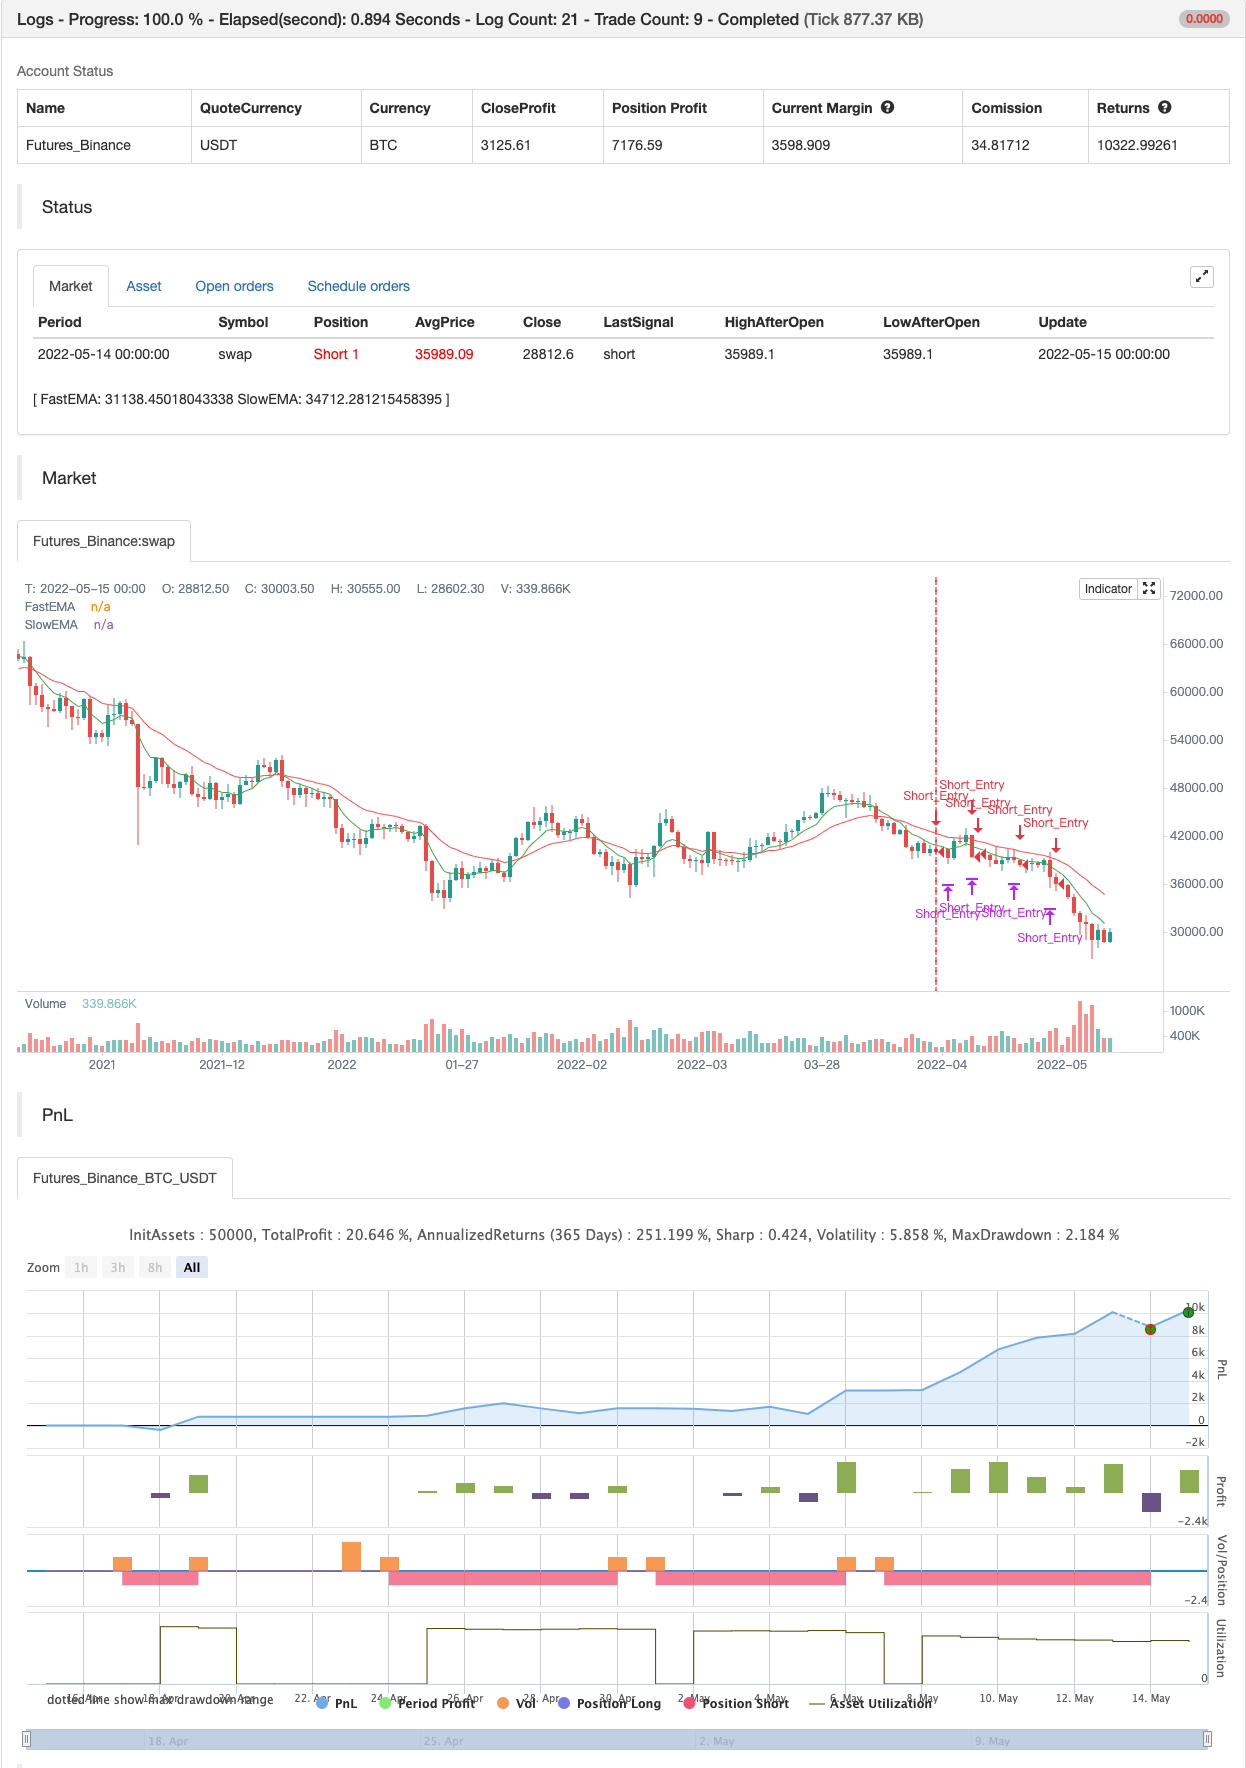
This strategy utilizes the 9 and 20 period exponential moving averages to create a colored cloud between similar to what is seen on the Ichimoku Cloud . The strategy closes all trades by the end of the trading day…
This strategy utilizes the 9 and 20 period exponential moving averages to create a colored cloud between similar to what is seen on the Ichimoku Cloud . The strategy closes all trades by the end of the trading day. Entry is when the price closes above a Green (9 EMA above 20 EMA ) cloud or below a Red (9 EMA below 20 EMA ) cloud. Exit is when price closes against the 9 EMA or at the end of the trading day. Running the strategy tester on different intraday time frames will show the best time frame for a given Symbol. For example, I have found that the best results are returned by this strategy for SPY on the 30 minute time frame.
backtest
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 10 | Trade Quantity |
| v_input_1 | 7 | Fast EMA Length |
| v_input_2 | 20 | Slow EMA Length |
Source Pine Script
/*backtest
start: 2022-04-16 00:00:00
end: 2022-05-15 23:59:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © rwestbrookjr

//@version=5
strategy("EMA Cloud Intraday Strategy", overlay=true, margin_long=100, margin_short=100, process_orders_on_close=true)

i_trdQty = input.int(10, "Trade Quantity", minval = 1)


fastLen = input(title = "Fast EMA Length", defval = 7)
slowLen = input(title = "Slow EMA Length", defval = 20)

fastEMA = ta.ema(close, fastLen)
slowEMA = ta.ema(close, slowLen)

fema = plot(fastEMA, title = "FastEMA", color = color.green, linewidth = 1, style = plot.style_line)
sema = plot(slowEMA, title = "SlowEMA", color = color.red, linewidth = 1, style = plot.style_line)

fill(fema, sema, color = fastEMA > slowEMA ? color.new(#417505, 50) : color.new(#890101, 50), title = "Cloud")

longCondition = (close > fastEMA and fastEMA > slowEMA)

if (longCondition)
    strategy.entry("Long_Entry", strategy.long)
longExit = close[1] < fastEMA
if (longExit)
    strategy.close("Long_Entry",when=longExit)
    //strategy.exit("exit", "My Long Entry Id", trail_points=1.5, trail_offset=0)

shortCondition = (close < fastEMA and fastEMA < slowEMA)
if (shortCondition)
    strategy.entry("Short_Entry", strategy.short)
shortExit = close[1] > fastEMA
if (shortExit)
    strategy.close("Short_Entry",when=shortExit)
    //strategy.exit("exit", "My Short Entry Id", trail_points=1.5, trail_offset=0)
Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/EMA-Cloud-Intraday-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.