Strategy vault / Mean reversion
EMA Mean Reversion Trading Strategy
The EMA mean reversion trading strategy opens and closes positions based on the degree to which price diverges from the EMA. It uses the percentage difference between price and EMA as the entry signal and trailing…
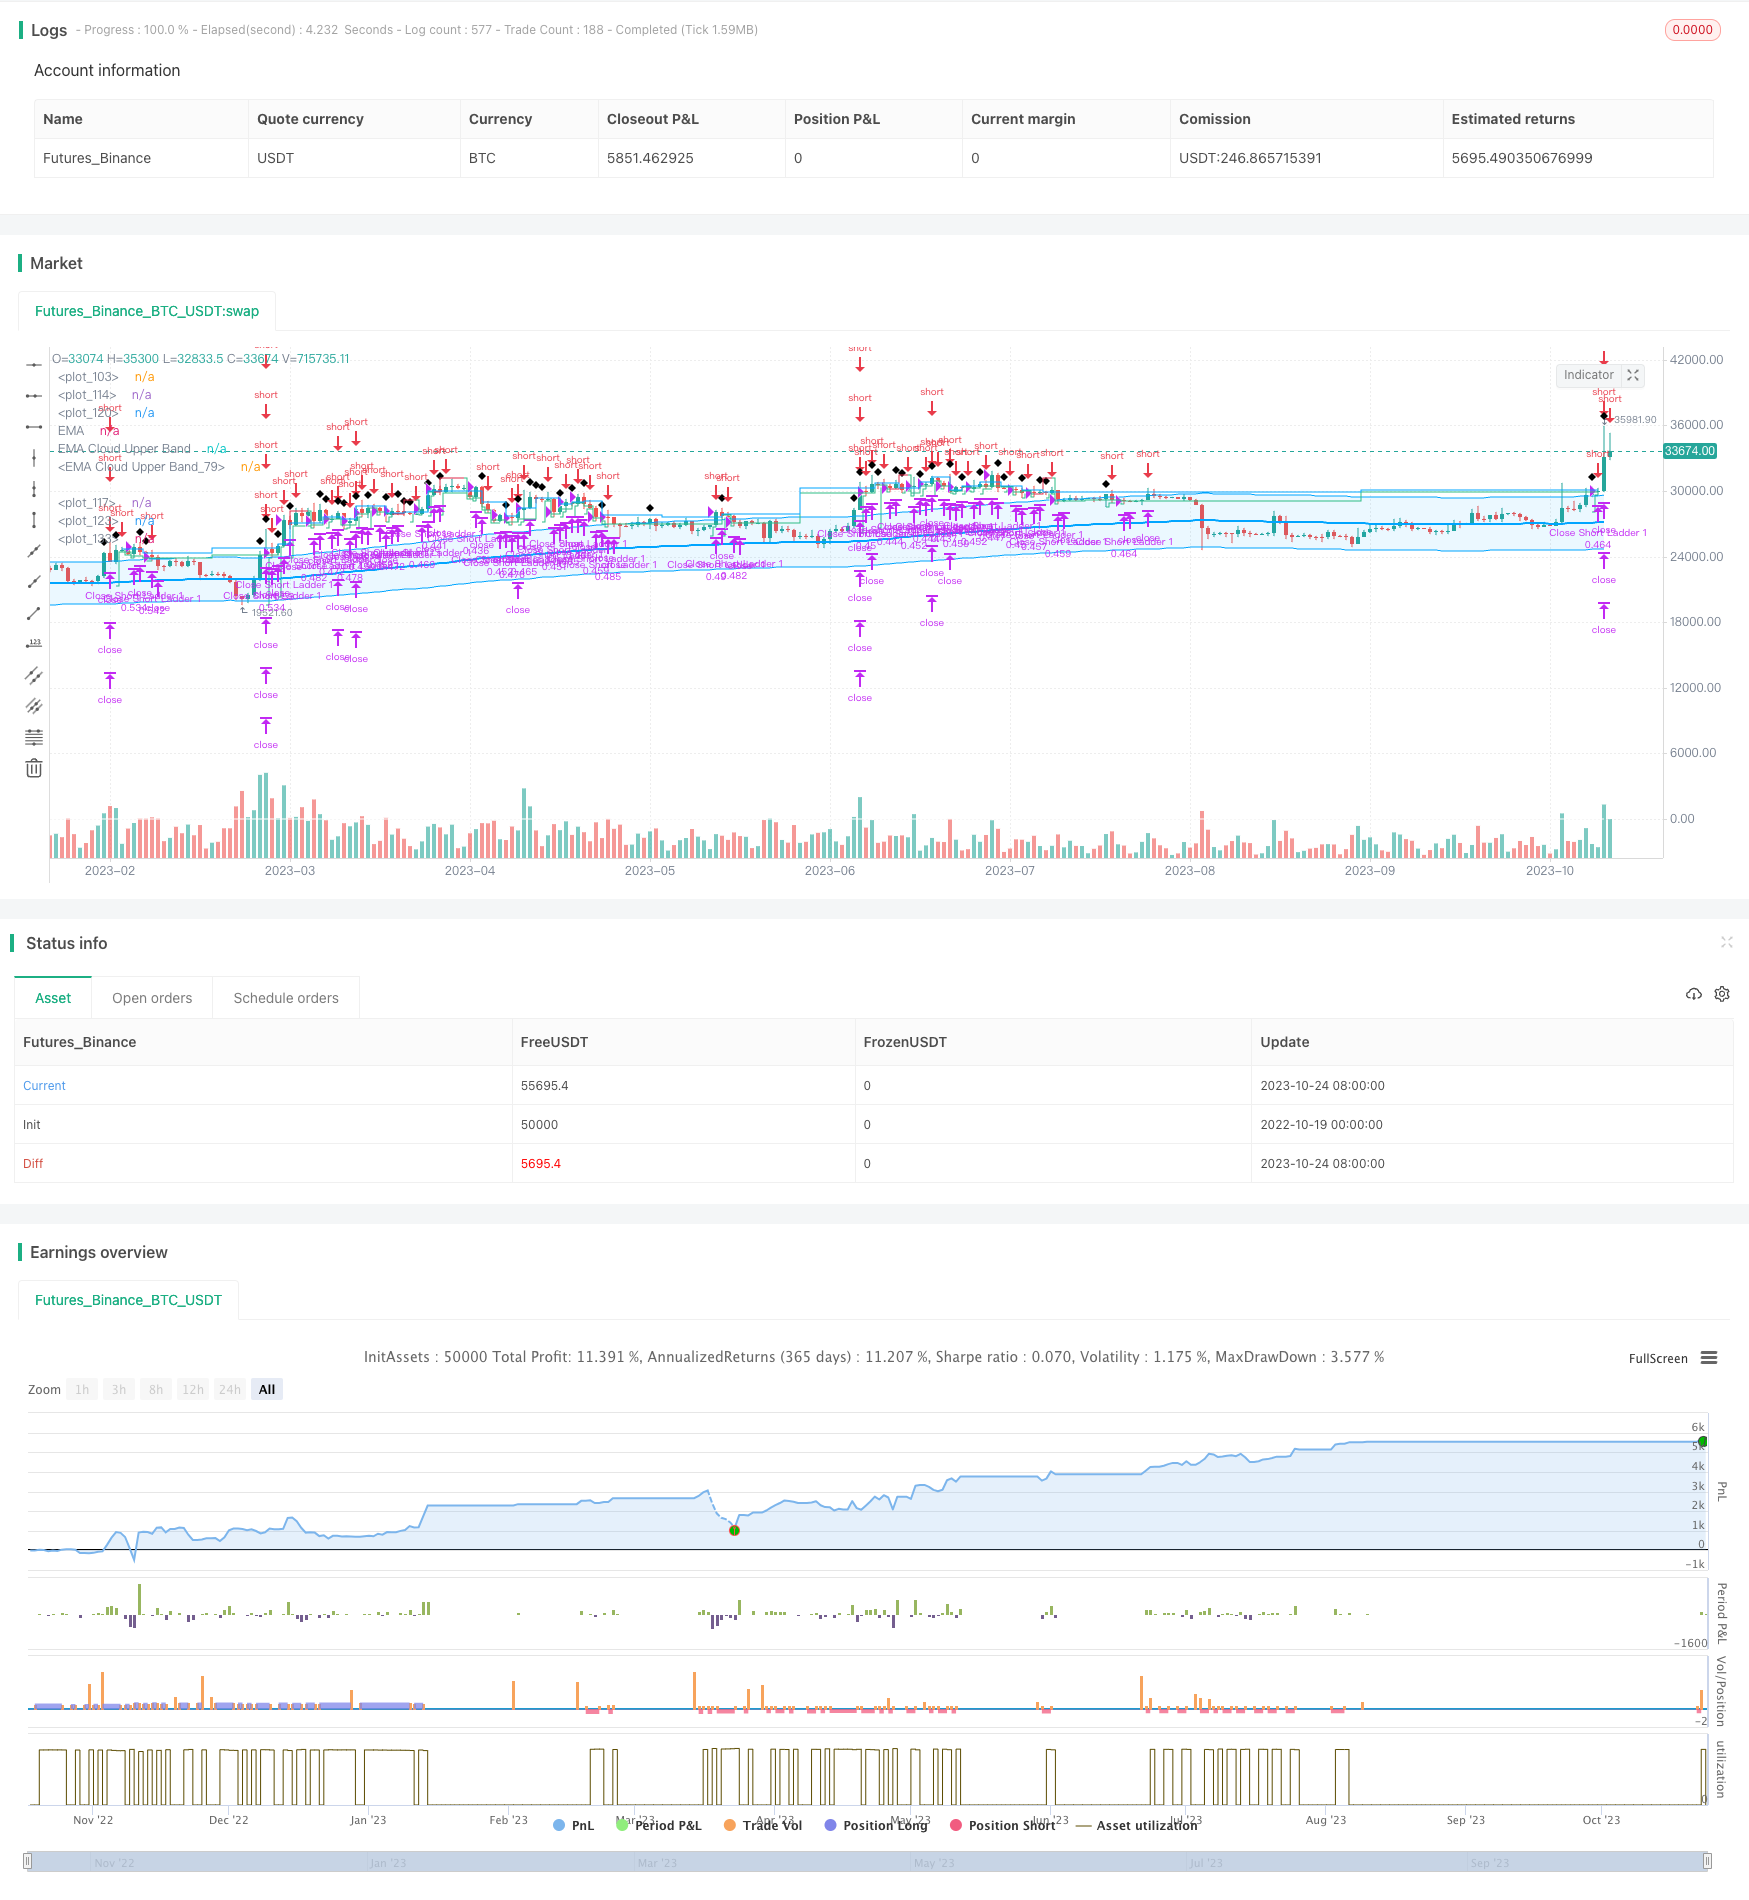
Overview
The EMA mean reversion trading strategy opens and closes positions based on the degree to which price diverges from the EMA. It uses the percentage difference between price and EMA as the entry signal and trailing stop loss to manage positions.
Strategy Logic
The strategy uses EMA as the benchmark and calculates the percentage difference between current price and EMA. It goes long when the price is far enough from the EMA (default 9%), and closes position when price gets close enough to the EMA (default 1%). After opening positions, it uses trailing stop loss to lock in profit as it increases.
Specifically, the strategy includes the following components:
Calculate EMA. The period (default 200), source (close price) and method (EMA, SMA, RMA, WMA) are configurable.
Calculate the percentage difference between current price and EMA. Pay attention to the positive/negative sign.
Open positions based on difference threshold. Default long entry is 9% and short entry is 9%.
Support ladder entry. The number of rungs and percentage step per rung can be configured.
Use trailing stop loss after entry. The threshold to start trailing (default 1% profit) and trailing percentage (default 1%) are configurable.
Close positions based on difference threshold. Default exit is 1% for both long and short.
Cancel unfilled orders when price reverts to EMA.
Configurable stop loss percentage.
Support backtesting and live trading.
Advantage Analysis
The advantages of this strategy:
Utilize mean reversion concept to trade trend based on EMA deviation. Aligns with trend trading theory.
Entry, stop loss, exit parameters are configurable to adapt to different market conditions.
Ladder entry allows gradual position build up and reduces cost.
Trailing stop locks in profit and manages risk.
Highly optimizable by adjusting EMA parameters or entry/exit thresholds.
Pine Script allows straightforward use in TradingView.
Intuitive charting for observation and analysis.
Risk Analysis
The risks of this strategy:
Backtest overfitting risk. Parameter optimization may overfit backtest data and underperform in live trading.
EMA failure risk. Price may deviate from EMA for extended periods.
Stop loss getting run over risk. Stop loss may get penetrated by volatile moves.
High trading frequency leads to higher commission costs.
Require longer lookback period. More susceptible to sudden events.
Risk management:
Robust parameter selection through optimization and multi-market verification.
Reasonable EMA period, not too short or too long.
Wider stop loss buffer to prevent getting stopped out prematurely.
Less aggressive entry rules to reduce trade frequency.
Incorporate additional indicators like volume, Bollinger Bands, RSI to adapt to events.
Optimization Directions
The strategy can be improved in the following aspects:
Add filters like volume, Bollinger Bands, RSI to reduce false signals.
Add dual EMA for higher probability trend trading.
Enhance stop loss with adaptive stops, Chandelier Exits to further limit risk.
Add auto parameter optimization to find better parameter sets.
Incorporate machine learning for chance of EMA deviation.
Consider intraday or overnight position to take advantage of gaps.
Integrate stock universe selection for larger capacity.
Conclusion
The EMA mean reversion strategy trades based on the mean reverting behavior of prices around a moving average. It utilizes the statistical properties of EMA rationally to identify trend changes and uses stop loss to control risk. Compared to traditional moving average strategies, it focuses more on dynamic trailing stops than rigid entry and exit rules. The strategy can complement trend following strategies, but requires caution on curve fitting and controlling trade frequency. Further improvements on stop loss and entry quality may lead to better live performance.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_timeframe_1 | (?EMA Settings)Timeframe | |
| v_input_int_1 | 200 | Length |
| v_input_string_1 | 0 | Type: EMA | SMA | RMA | WMA |
| v_input_source_1_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_float_1 | 9 | (?Entry Settings)Long Position Entry Trigger |
| v_input_float_2 | 9 | Short Position Entry Trigger |
| v_input_float_3 | true | Close Position Trigger |
| v_input_float_4 | 4 | Cancel Unfilled Entries Trigger |
| v_input_bool_1 | true | Ladder Into Positions |
| v_input_int_2 | 4 | Ladder Rungs |
| v_input_float_5 | 0.5 | Ladder Step (%) |
| v_input_float_6 | 4 | Stop Loss (%) |
| v_input_float_7 | true | Start Trailing After (%) |
| v_input_float_8 | true | Trail Behind (%) |
Source Pine Script
/*backtest
start: 2022-10-19 00:00:00
end: 2023-10-25 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © jordanfray

//@version=5
strategy(title="EMA Mean Reversion Strategy", overlay=true, max_bars_back=5000, default_qty_type=strategy.percent_of_equity, default_qty_value=100,initial_capital=100000, commission_type=strategy.commission.percent, commission_value=0.05, backtest_fill_limits_assumption=2)


// Indenting Classs
indent_1 = " "
indent_2 = "  "
indent_3 = "   "
indent_4 = "    "


// Tooltips
longEntryToolTip = "When the percentage that the price is away from the selected EMA reaches this point, a long postion will open."
shortEntryToolTip = "When the percentage that the price is away from the selected EMA reaches this point, a short postion will open."
closeEntryToolTip = "When the percentage that the price is away from the selected EMA reaches this point, open postion will close."
ladderInToolTip = "Enable this to use the laddering settings below."
cancelEntryToolTip = "When the percentage that the price is away from the selected EMA reaches this point, any unfilled entries will be canceled."

// Group Titles
group_one_title = "EMA Settings"
group_two_title = "Entry Settings"


// Colors
blue = color.new(#00A5FF,0)
lightBlue = color.new(#00A5FF,90)
green = color.new(#2DBD85,0)
gray_80 =  color.new(#7F7F7F,80)
gray_60 =  color.new(#7F7F7F,60)
gray_40 =  color.new(#7F7F7F,40)
white = color.new(#ffffff,0)
red = color.new(#E02A4A,0)
transparent = color.new(#000000,100)


// Strategy Settings
EMAtimeframe = input.timeframe(defval="", title="Timeframe", group=group_one_title)
EMAlength = input.int(defval=200, minval=1, title="Length", group=group_one_title)
EMAtype = input.string(defval="EMA", options = ["EMA", "SMA", "RMA", "WMA"], title="Type", group=group_one_title)
EMAsource = input.source(defval=close, title="Source", group=group_one_title)

openLongEntryAbove = input.float(defval=9, title="Long Position Entry Trigger", tooltip=longEntryToolTip, group=group_two_title)
openEntryEntryAbove = input.float(defval=9, title="Short Position Entry Trigger", tooltip=shortEntryToolTip, group=group_two_title)
closeEntryBelow = input.float(defval=1.0, title="Close Position Trigger", tooltip=closeEntryToolTip, group=group_two_title)
cancelEntryBelow = input.float(defval=4, title="Cancel Unfilled Entries Trigger", tooltip=cancelEntryToolTip, group=group_two_title)

enableLaddering = input.bool(defval=true, title="Ladder Into Positions", tooltip=ladderInToolTip, group=group_two_title)
ladderRungs = input.int(defval=4, minval=2, maxval=4, step=1, title=indent_4+"Ladder Rungs", group=group_two_title)
ladderStep = input.float(defval=.5, title=indent_4+"Ladder Step (%)", step=.1, group=group_two_title)/100
stop_loss_val = input.float(defval=4.0, title="Stop Loss (%)", step=0.1, group=group_two_title)/100
start_trailing_after = input.float(defval=1, title="Start Trailing After (%)", step=0.1, group=group_two_title)/100
trail_behind = input.float(defval=1, title="Trail Behind (%)", step=0.1, group=group_two_title)/100

// Calculate trailing stop values
long_start_trailing_val = strategy.position_avg_price + (strategy.position_avg_price * start_trailing_after)
long_trail_behind_val = close - (strategy.position_avg_price * trail_behind)
long_stop_loss = strategy.position_avg_price * (1.0 - stop_loss_val)
short_start_trailing_val = strategy.position_avg_price - (strategy.position_avg_price * start_trailing_after)
short_trail_behind_val = close + (strategy.position_avg_price * trail_behind)
short_stop_loss = strategy.position_avg_price * (1 + stop_loss_val)


// Calulate EMA
EMA = switch EMAtype
    "EMA" => ta.ema(EMAsource, EMAlength)
    "SMA" => ta.sma(EMAsource, EMAlength)
    "RMA" => ta.rma(EMAsource, EMAlength)
    "WMA" => ta.wma(EMAsource, EMAlength)
    => na
EMA_ = EMAtimeframe == timeframe.period ? EMA : request.security(syminfo.ticker, EMAtimeframe, EMA[1], lookahead = barmerge.lookahead_on)
plot(EMA_, title="EMA", linewidth=2, color=blue, editable=true)

EMA_cloud_upper_band_val = EMA_ + (EMA_ * openLongEntryAbove/100)
EMA_cloud_lower_band_val = EMA_ - (EMA_ * openLongEntryAbove/100)
EMA_cloud_upper_band = plot(EMA_cloud_upper_band_val, title="EMA Cloud Upper Band", color=blue)
EMA_cloud_lower_band = plot(EMA_cloud_lower_band_val, title="EMA Cloud Upper Band", color=blue)
fill(EMA_cloud_upper_band, EMA_cloud_lower_band, editable=false, color=lightBlue)

distance_from_EMA = ((close - EMA_)/close)*100
if distance_from_EMA < 0
    distance_from_EMA := distance_from_EMA * -1

// Calulate Ladder Entries
long_ladder_1_limit_price = close - (close * 1 * ladderStep)
long_ladder_2_limit_price = close - (close * 2 * ladderStep)
long_ladder_3_limit_price = close - (close * 3 * ladderStep)
long_ladder_4_limit_price = close - (close * 4 * ladderStep)

short_ladder_1_limit_price = close + (close * 1 * ladderStep)
short_ladder_2_limit_price = close + (close * 2 * ladderStep)
short_ladder_3_limit_price = close + (close * 3 * ladderStep)
short_ladder_4_limit_price = close + (close * 4 * ladderStep)

var position_qty = strategy.equity/close
if enableLaddering
    position_qty := (strategy.equity/close) / ladderRungs
else
    position_qty := strategy.equity/close

plot(position_qty, color=white)
//plot(strategy.equity, color=green)

// Entry Conditions
currently_in_a_postion = strategy.position_size != 0
currently_in_a_long_postion = strategy.position_size > 0
currently_in_a_short_postion = strategy.position_size < 0
average_price = strategy.position_avg_price

bars_since_entry = currently_in_a_postion ? bar_index - strategy.opentrades.entry_bar_index(strategy.opentrades - 1) + 1 : 5
long_run_up = ta.highest(high, bar_index == 0 ? 5000: bars_since_entry)
long_run_up_line = plot(long_run_up, style=plot.style_stepline, editable=false, color=currently_in_a_long_postion ? green : transparent)
start_trailing_long_entry = currently_in_a_long_postion and long_run_up > long_start_trailing_val
long_trailing_stop = start_trailing_long_entry ? long_run_up - (long_run_up * trail_behind) : long_stop_loss
long_trailing_stop_line = plot(long_trailing_stop, style=plot.style_stepline, editable=false, color=currently_in_a_long_postion ? long_trailing_stop > strategy.position_avg_price ? green : red : transparent)

short_run_up = ta.lowest(low, bar_index == 0 ? 5000: bars_since_entry)
short_run_up_line = plot(short_run_up, style=plot.style_stepline, editable=false, color=currently_in_a_short_postion ? green : transparent)
start_trailing_short_entry = currently_in_a_short_postion and short_run_up < short_start_trailing_val
short_trailing_stop = start_trailing_short_entry ? short_run_up + (short_run_up * trail_behind) : short_stop_loss
short_trailing_stop_line = plot(short_trailing_stop, style=plot.style_stepline, editable=false, color=currently_in_a_short_postion ? short_trailing_stop < strategy.position_avg_price ? green : red : transparent)

long_conditions_met = distance_from_EMA > openLongEntryAbove and close < EMA_ and not currently_in_a_postion
short_conditions_met = distance_from_EMA > openEntryEntryAbove and close > EMA_ and not currently_in_a_postion
close_long_entries = distance_from_EMA <= closeEntryBelow or close <= long_trailing_stop
close_short_entries = distance_from_EMA <= closeEntryBelow or close >= short_trailing_stop
cancel_entries = distance_from_EMA <= cancelEntryBelow

plotshape(long_conditions_met ? close : na, style=shape.diamond, title="Long Conditions Met" )
plotshape(short_conditions_met ? close : na, style=shape.diamond, title="Short Conditions Met" )
plot(average_price,style=plot.style_stepline, editable=false, color=currently_in_a_postion ? blue : transparent)

// Long Entry
if enableLaddering
    if ladderRungs == 2
        strategy.entry(id="Long Ladder 1", direction=strategy.long, qty=position_qty, limit=long_ladder_1_limit_price, when=long_conditions_met)
        strategy.entry(id="Long Ladder 2", direction=strategy.long, qty=position_qty, limit=long_ladder_2_limit_price, when=long_conditions_met)
    else if ladderRungs == 3
        strategy.entry(id="Long Ladder 1", direction=strategy.long, qty=position_qty, limit=long_ladder_1_limit_price, when=long_conditions_met)
        strategy.entry(id="Long Ladder 2", direction=strategy.long, qty=position_qty, limit=long_ladder_2_limit_price, when=long_conditions_met)
        strategy.entry(id="Long Ladder 3", direction=strategy.long, qty=position_qty, limit=long_ladder_3_limit_price, when=long_conditions_met)
    else if ladderRungs == 4
        strategy.entry(id="Long Ladder 1", direction=strategy.long, qty=position_qty, limit=long_ladder_1_limit_price, when=long_conditions_met)
        strategy.entry(id="Long Ladder 2", direction=strategy.long, qty=position_qty, limit=long_ladder_2_limit_price, when=long_conditions_met)
        strategy.entry(id="Long Ladder 3", direction=strategy.long, qty=position_qty, limit=long_ladder_3_limit_price, when=long_conditions_met)
        strategy.entry(id="Long Ladder 4", direction=strategy.long, qty=position_qty, limit=long_ladder_4_limit_price, when=long_conditions_met)

    strategy.exit(id="Close Long Ladder 1", from_entry="Long Ladder 1", stop=long_trailing_stop, limit=long_trailing_stop, when=close_long_entries)
    strategy.exit(id="Close Long Ladder 2", from_entry="Long Ladder 2", stop=long_trailing_stop, limit=long_trailing_stop, when=close_long_entries)
    strategy.exit(id="Close Long Ladder 3", from_entry="Long Ladder 3", stop=long_trailing_stop, limit=long_trailing_stop, when=close_long_entries)
    strategy.exit(id="Close Long Ladder 4", from_entry="Long Ladder 4", stop=long_trailing_stop, limit=long_trailing_stop, when=close_long_entries)

    strategy.cancel(id="Long Ladder 1", when=cancel_entries)
    strategy.cancel(id="Long Ladder 2", when=cancel_entries)
    strategy.cancel(id="Long Ladder 3", when=cancel_entries)
    strategy.cancel(id="Long Ladder 4", when=cancel_entries)
else
    strategy.entry(id="Long", direction=strategy.long, qty=100, when=long_conditions_met)
    strategy.exit(id="Close Long", from_entry="Long", stop=long_stop_loss, limit=EMA_, when=close_long_entries)
    strategy.cancel(id="Long", when=cancel_entries)

// Short Entry
if enableLaddering
    if ladderRungs == 2
        strategy.entry(id="Short Ladder 1", direction=strategy.short, qty=position_qty, limit=short_ladder_1_limit_price, when=short_conditions_met)
        strategy.entry(id="Short Ladder 2", direction=strategy.short, qty=position_qty, limit=short_ladder_2_limit_price, when=short_conditions_met)
    else if ladderRungs == 3
        strategy.entry(id="Short Ladder 1", direction=strategy.short, qty=position_qty, limit=short_ladder_1_limit_price, when=short_conditions_met)
        strategy.entry(id="Short Ladder 2", direction=strategy.short, qty=position_qty, limit=short_ladder_2_limit_price, when=short_conditions_met)
        strategy.entry(id="Short Ladder 3", direction=strategy.short, qty=position_qty, limit=short_ladder_3_limit_price, when=short_conditions_met)
    else if ladderRungs == 4
        strategy.entry(id="Short Ladder 1", direction=strategy.short, qty=position_qty, limit=short_ladder_1_limit_price, when=short_conditions_met)
        strategy.entry(id="Short Ladder 2", direction=strategy.short, qty=position_qty, limit=short_ladder_2_limit_price, when=short_conditions_met)
        strategy.entry(id="Short Ladder 3", direction=strategy.short, qty=position_qty, limit=short_ladder_3_limit_price, when=short_conditions_met)
        strategy.entry(id="Short Ladder 4", direction=strategy.short, qty=position_qty, limit=short_ladder_4_limit_price, when=short_conditions_met)

    strategy.exit(id="Close Short Ladder 1", from_entry="Short Ladder 1", stop=short_trailing_stop, limit=EMA_, when=close_short_entries)
    strategy.exit(id="Close Short Ladder 2", from_entry="Short Ladder 2", stop=short_trailing_stop, limit=EMA_, when=close_short_entries)
    strategy.exit(id="Close Short Ladder 3", from_entry="Short Ladder 3", stop=short_trailing_stop, limit=EMA_, when=close_short_entries)
    strategy.exit(id="Close Short Ladder 4", from_entry="Short Ladder 4", stop=short_trailing_stop, limit=EMA_, when=close_short_entries)

    strategy.cancel(id="Short Ladder 1", when=cancel_entries)
    strategy.cancel(id="Short Ladder 2", when=cancel_entries)
    strategy.cancel(id="Short Ladder 3", when=cancel_entries)
    strategy.cancel(id="Short Ladder 4", when=cancel_entries)
else
    strategy.entry(id="Short", direction=strategy.short, when=short_conditions_met)
    strategy.exit(id="Close Short", from_entry="Short", limit=EMA_, when=close_short_entries)
    strategy.cancel(id="Short", when=cancel_entries)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/EMA-Mean-Reversion-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trading Strategy Combining RSI Divergence and Moving AveragesPine Script · Mean reversion · 1h
- Advanced Quantitative Trend Following and Cloud Reversal Composite Trading StrategyPine Script · Mean reversion · 1d
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d
- Bidirectional Moving Average Reversion Trading StrategyPine Script · Mean reversion · 1h