Strategy vault / DCA & fixed investment
EMA Multi DCA Strategy with Trailing Stop Loss and Profit Target
This strategy utilizes dynamic multiple EMAs as entry signals combined with trailing stop loss and profit target mechanisms for risk management. It takes advantage of the smoothing nature of EMAs to identify trends…
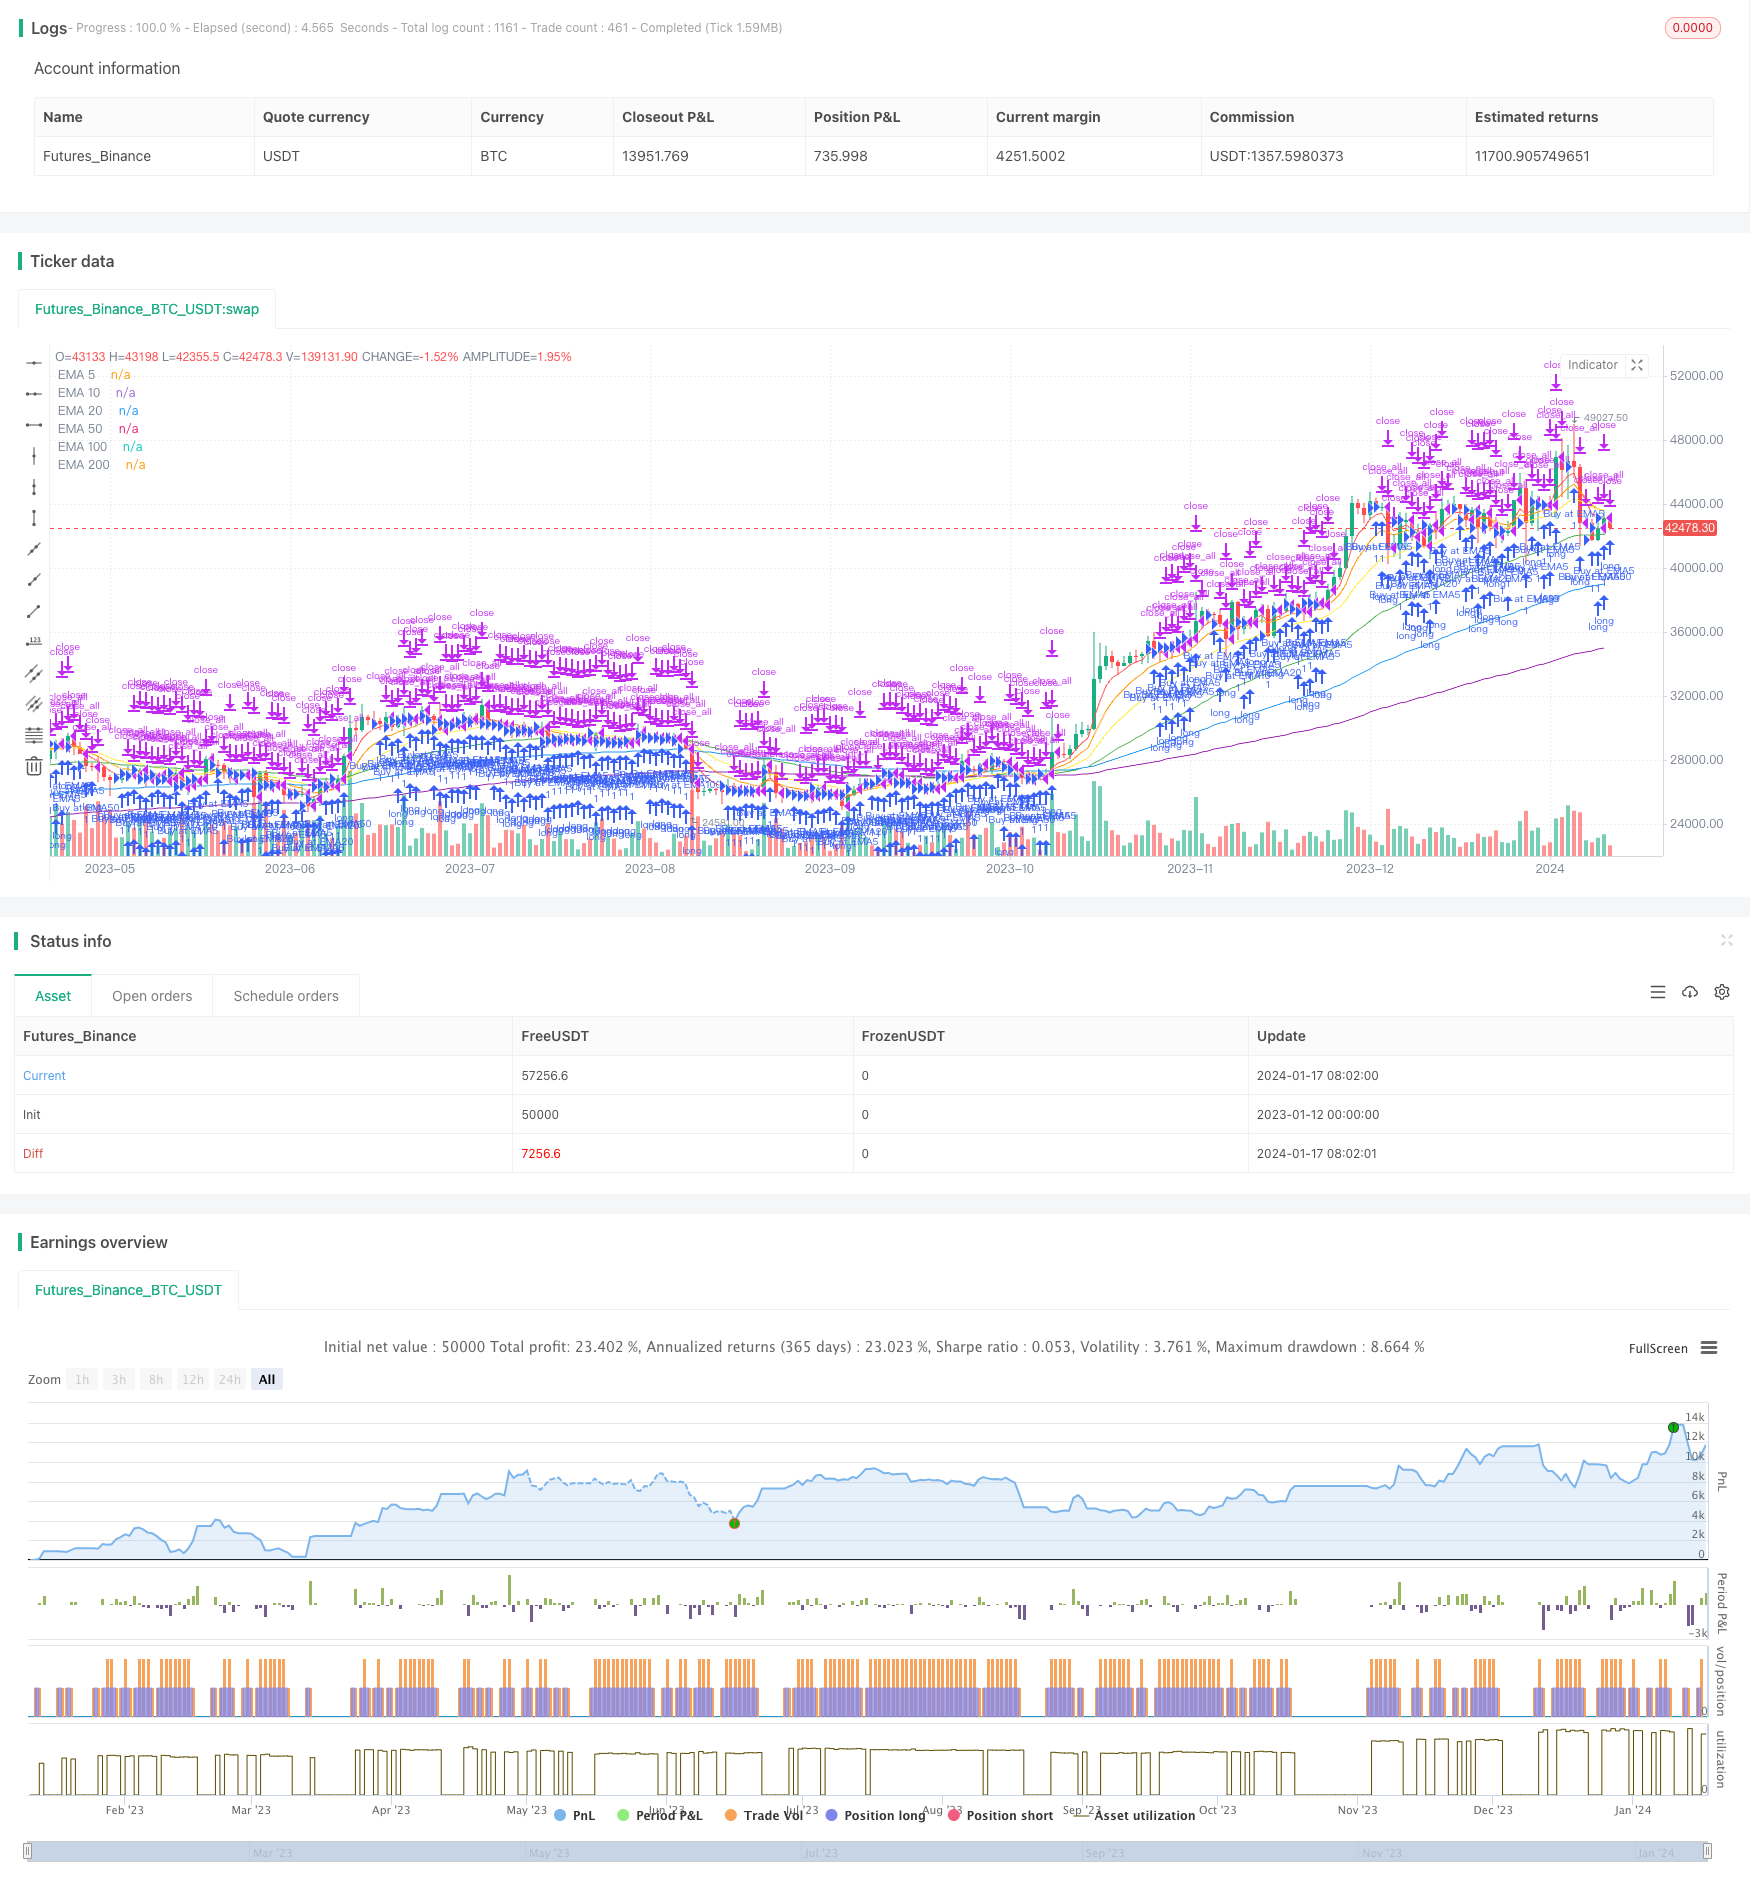
Overview
This strategy utilizes dynamic multiple EMAs as entry signals combined with trailing stop loss and profit target mechanisms for risk management. It takes advantage of the smoothing nature of EMAs to identify trends and control cost via multi-DCA entries. In addition, the integration of adaptive stop loss and profit taking features enhances the automation process.
Strategy Logic
Indicators
- EMA5, EMA10, EMA20, EMA50, EMA100, EMA 200
- Average True Range (ATR)
Entry Signals
Triggers long entry when price crosses or moves inside a range of selected EMA periods. Typical EMAs include 5, 10, 20, 50, 100, 200 periods. This strategy uses 1% range of EMA as the entry criteria.
Risk Management
Incorporates multiple risk control mechanisms:
- ATR Stop Loss: Close all positions when ATR exceeds threshold
- Entry Frequency Limit: Control maximum number of entries
- Trailing Stop Loss: Dynamic stop loss based on price movement
Profit Taking
Set profit target price levels for exits
Advantages
- Identify trends using EMAs with noise filtering
- Cost averaging via multi-DCA entries
- Enhanced entry signals using EMA combos
- Adaptive stop loss mechanism
- Take profit control for profit protection
Risks & Improvements
- EMAs tuning needs optimization for different markets
- Excessive DCA entries may occupy too much capital
- Stop loss percentage needs backtesting
Enhancement Strategies
- Utilize advanced EMA systems for better trend identification
- Multi-variable optimization of DCA frequency and stop loss percentage
- Incorporate machine learning models for price change forecasts
- Integrate position sizing module to manage overall capital utilization
Conclusion
The strategy encompasses EMA trend detection, multi-DCA cost averaging, trailing stop loss, target profit taking and more. There remains ample potential in tuning parameters and enhancing risk controls. Overall, this highly adaptive and versatile strategy offers investors stable alpha generation capabilities.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | ATR Sell Threshold |
| v_input_2 | 3000 | Buy Limit |
| v_input_3 | true | Trailing Stop Percentage |
| v_input_4 | 3 | Profit Target Percentage |
Source Pine Script
/*backtest
start: 2023-01-12 00:00:00
end: 2024-01-18 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("EMA DCA Strategy with Trailing Stop and Profit Target", overlay=true )

// Define the investment amount for when the condition is met
investment_per_condition = 6

// Define the EMAs
ema5 = ema(close, 5)
ema10 = ema(close, 10)
ema20 = ema(close, 20)
ema50 = ema(close, 50)
ema100 = ema(close, 100)
ema200 = ema(close, 200)

// Define ATR sell threshold
atr_sell_threshold = input(title="ATR Sell Threshold", type=input.integer, defval=10, minval=1)

// Helper function to find if the price is within 1% of the EMA
isWithin1Percent(price, ema) =>
    ema_min = ema * 0.99
    ema_max = ema * 1.01
    price >= ema_min and price <= ema_max

// Control the number of buys
var int buy_count = 0
buy_limit = input(title="Buy Limit", type=input.integer, defval=3000)

// Calculate trailing stop and profit target levels
trail_percent = input(title="Trailing Stop Percentage", type=input.integer, defval=1, minval=0, maxval=10)
profit_target_percent = input(title="Profit Target Percentage", type=input.integer, defval=3, minval=1, maxval=10)

// Determine if the conditions are met and execute the strategy
checkConditionAndBuy(emaValue, emaName) =>
    var int local_buy_count = 0 // Create a local mutable variable
    if isWithin1Percent(close, emaValue) and local_buy_count < buy_limit
        strategy.entry("Buy at " + emaName, strategy.long, qty=investment_per_condition / close, alert_message ="Buy condition met for " + emaName)
        local_buy_count := local_buy_count + 1
        // alert("Buy Condition", "Buy condition met for ", freq_once_per_bar_close)

    local_buy_count // Return the updated local_buy_count

// Add ATR sell condition
atr_condition = atr(20) > atr_sell_threshold
if atr_condition
    strategy.close_all()
    buy_count := 0 // Reset the global buy_count when selling

// Strategy execution
buy_count := checkConditionAndBuy(ema5, "EMA5")
buy_count := checkConditionAndBuy(ema10, "EMA10")
buy_count := checkConditionAndBuy(ema20, "EMA20")
buy_count := checkConditionAndBuy(ema50, "EMA50")
buy_count := checkConditionAndBuy(ema100, "EMA100")
buy_count := checkConditionAndBuy(ema200, "EMA200")

// Calculate trailing stop level
trail_offset = close * trail_percent / 100
trail_level = close - trail_offset

// Set profit target level
profit_target_level = close * (1 + profit_target_percent / 100)

// Exit strategy: Trailing Stop and Profit Target
strategy.exit("TrailingStop", from_entry="Buy at EMA", trail_offset=trail_offset, trail_price=trail_level)
strategy.exit("ProfitTarget", from_entry="Buy at EMA",  when=close >= profit_target_level)

// Plot EMAs
plot(ema5, title="EMA 5", color=color.red)
plot(ema10, title="EMA 10", color=color.orange)
plot(ema20, title="EMA 20", color=color.yellow)
plot(ema50, title="EMA 50", color=color.green)
plot(ema100, title="EMA 100", color=color.blue)
plot(ema200, title="EMA 200", color=color.purple)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/EMA-Multi-DCA-Strategy-with-Trailing-Stop-Loss-and-Profit-Target.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA Crossover Smart DCA with Dual Trailing Stop SystemPine Script · DCA & fixed investment · 1d
- Intelligent Volatility Responsive DCA Strategy with Dual Trailing Stop SystemPine Script · DCA & fixed investment · 1h
- Multi Indicator Confirmation EMA Breakout with DCA and Dynamic Take Profit StrategyPine Script · DCA & fixed investment · 1d
- Quantized Gradual Weighted DCA Trading StrategyPine Script · DCA & fixed investment · 1d
- Dollar Cost Averaging After Downtrend StrategyPine Script · DCA & fixed investment · 1h
- 50 Period EMA Crossover with Monthly Dollar Cost Averaging Dual Optimization Trend Following StrategyPine Script · DCA & fixed investment · 1d