Fast Oscillating RSI Trading Strategy
This is a trading strategy that identifies oscillating markets using the RSI indicator and captures trend reversal opportunities during market oscillations. The strategy judges if prices have entered the oscillation…
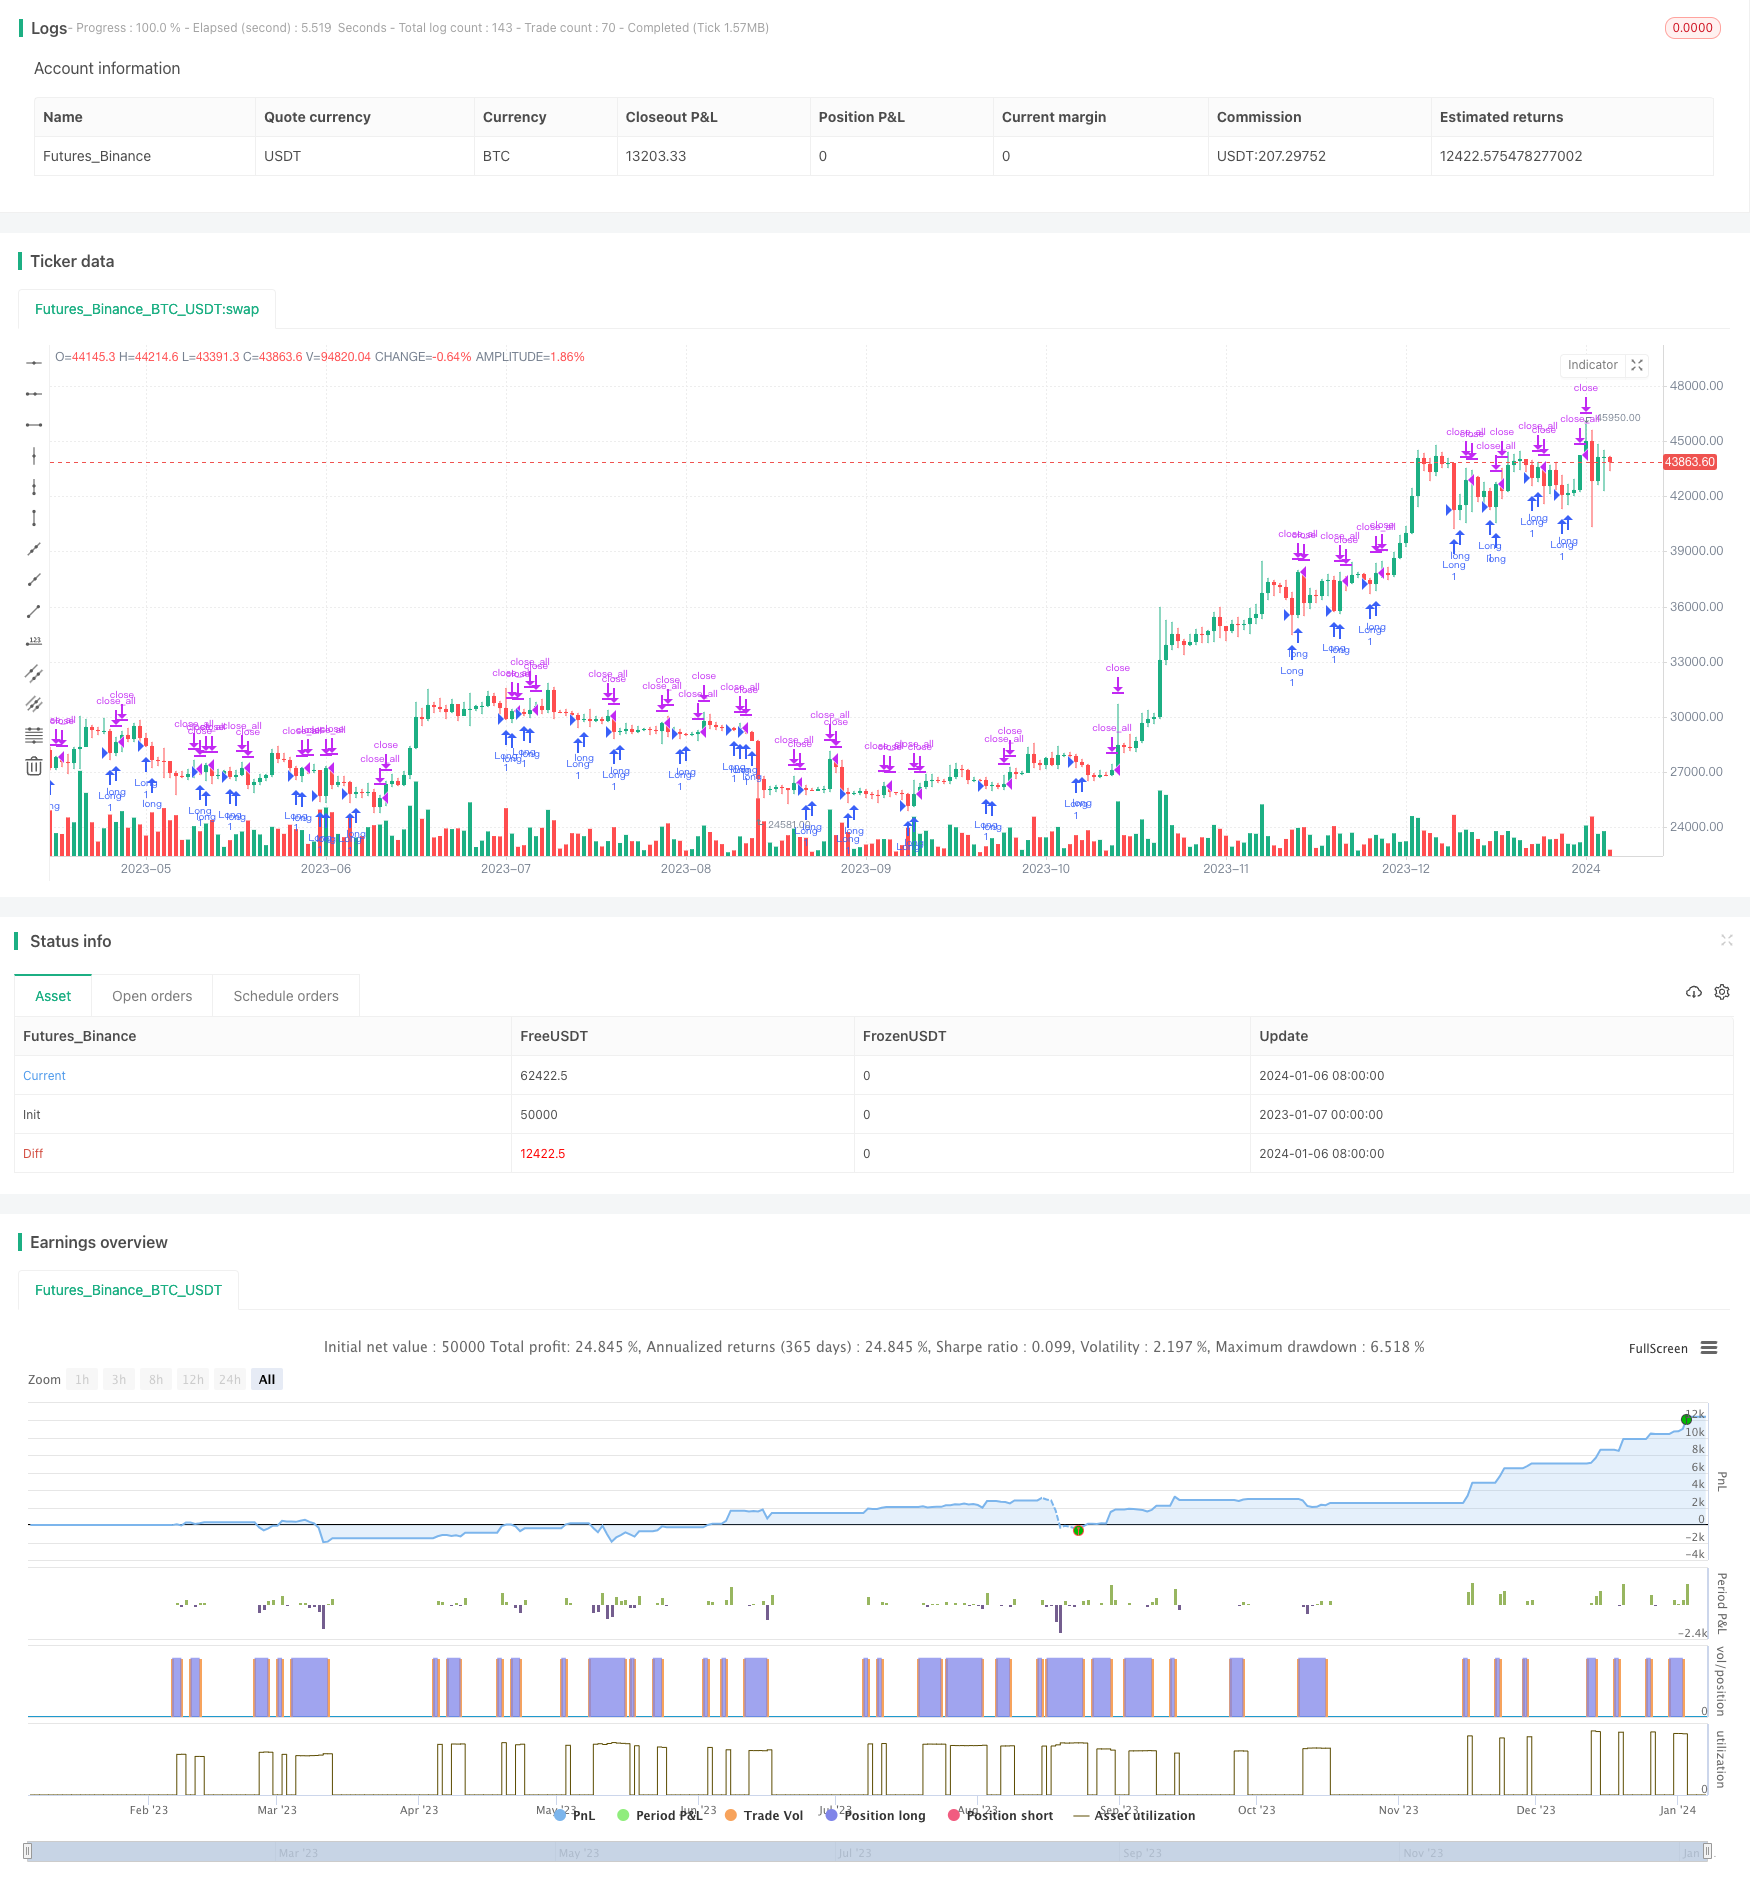
Overview
This is a trading strategy that identifies oscillating markets using the RSI indicator and captures trend reversal opportunities during market oscillations. The strategy judges if prices have entered the oscillation zone by the fast RSI indicator and determines entry timing in combination with candlestick bodies and fast RSI signals.
Strategy Logic
The strategy mainly operates on the following principles:
- Identify oscillating price action by fast RSI judging if prices have entered the overbought/oversold zone
- Determine specific entry timing with candlestick body breakout and fast RSI signals
- Avoid false signals in non-oscillating trends through dual filter mechanisms
Specifically, the strategy employs dual-period RSI to judge if prices have entered the 30-70 pre-set oscillation range. It also requires the candle body to break through 1/4 or 1/2 of the MA before generating trading signals. By such dual conditional checks, false signals can be effectively filtered out to ensure entering the market only when real oscillation happens.
Advantage Analysis
The strategy demonstrates significant advantages as follows:
- Fast RSI indicator is sensitive to swiftly identify prices entering/leaving the oscillation zone
- Dual timeframe analysis prevents interference from market noise
- Candle filter ensures entering on real trend reversals
- Medium trade frequency prevents over-trading
Risk Analysis
There are also some risks to be aware of:
- Possible missing trend reversal opportunities leading to insufficient profit
- Whipsw signals may cause losses
- Improper parameter settings impact strategy performance
To control risks, adjusting parameter combinations, live trading verification and stop loss mechanisms are recommended.
Optimization Directions
There is room for further optimization:
- Integrate other indicator signals to build Likelihood model
- Add adaptive parameter tuning module
- Increase algo trading module for faster trade execution
By techniques like multi-indicator integration, adaptive parameter tuning and algo trading, strategy stability and profitability can be lifted to the next level.
Conclusion
The fast oscillating RSI trading strategy identifies price oscillations and determines entry timing via fast RSI and dual filter mechanisms. It is an effective strategy worth in-depth research and application. In practice, risks should be monitored and multi-dimensional optimizations are needed to further lift the strategy efficacy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2 | RSI UP Period |
| v_input_2 | 9 | RSI DN Period |
| v_input_3 | 30 | RSI limit |
| v_input_4_close | 0 | RSI Price: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_5 | true | RSI Bars |
| v_input_6 | 2018 | From Year |
| v_input_7 | 2018 | To Year |
| v_input_8 | true | From Month |
| v_input_9 | 12 | To Month |
| v_input_10 | true | From day |
| v_input_11 | 31 | To day |
Source Pine Script
/*backtest
start: 2023-01-07 00:00:00
end: 2024-01-07 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy(title = "Noro's FRSI Strategy v1.22", shorttitle = "FRSI str 1.22", overlay = true )

//Settings
uprsiperiod = input(2, defval = 2, minval = 2, maxval = 50, title = "RSI UP Period")
dnrsiperiod = input(9, defval = 9, minval = 2, maxval = 50, title = "RSI DN Period")
limit = input(30, defval = 30, minval = 1, maxval = 100, title = "RSI limit")
rsisrc = input(close, defval = close, title = "RSI Price")
rb = input(1, defval = 1, minval = 1, maxval = 5, title = "RSI Bars")
sps = 0
fromyear = input(2018, defval = 2018, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2018, defval = 2018, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To day")

//Fast RSI
fastup = rma(max(change(rsisrc), 0), uprsiperiod)
fastdown = rma(-min(change(rsisrc), 0), dnrsiperiod)
fastrsi = fastdown == 0 ? 100 : fastup == 0 ? 0 : 100 - (100 / (1 + fastup / fastdown))

//Limits
bar = close > open ? 1 : close < open ? -1 : 0
uplimit = 100 - limit
dnlimit = limit

//RSI Bars
ur = fastrsi > uplimit
dr = fastrsi < dnlimit
uprsi = rb == 1 and ur ? 1 : rb == 2 and ur and ur[1] ? 1 : rb == 3 and ur and ur[1] and ur[2] ? 1 : rb == 4 and ur and ur[1] and ur[2] and ur[3] ? 1 : rb == 5 and ur and ur[1] and ur[2] and ur[3] and ur[4] ? 1 : 0
dnrsi = rb == 1 and dr ? 1 : rb == 2 and dr and dr[1] ? 1 : rb == 3 and dr and dr[1] and dr[2] ? 1 : rb == 4 and dr and dr[1] and dr[2] and dr[3] ? 1 : rb == 5 and dr and dr[1] and dr[2] and dr[3] and dr[4] ? 1 : 0

//Body
body = abs(close - open)
emabody = ema(body, 30)

//Signals
up = bar == -1 and sps == 0 and dnrsi and body > emabody / 4
dn = bar == 1 and sps == 0 and uprsi and body > emabody / 4
exit = bar == 1 and fastrsi > dnlimit and body > emabody / 2

//Trading
if up
    strategy.entry("Long", strategy.long)
    sps := 1

if exit
    strategy.close_all()
    sps := 0
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-08. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Fast-Oscillating-RSI-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bull Market Tracking SystemPine Script · Breakout · 1h
- Dual MA Momentum Breakout StrategyPine Script · Breakout · 1h
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h
- Exponential Moving Average Candle Stop Trading StrategyPine Script · Breakout · 1d
- Fast RSI Breakout Trading StrategyPine Script · Breakout · 2d
- Force Breakthrough StrategyPine Script · Breakout · 30m