Strategy vault / Machine learning
Fast RSI Strategy Analysis
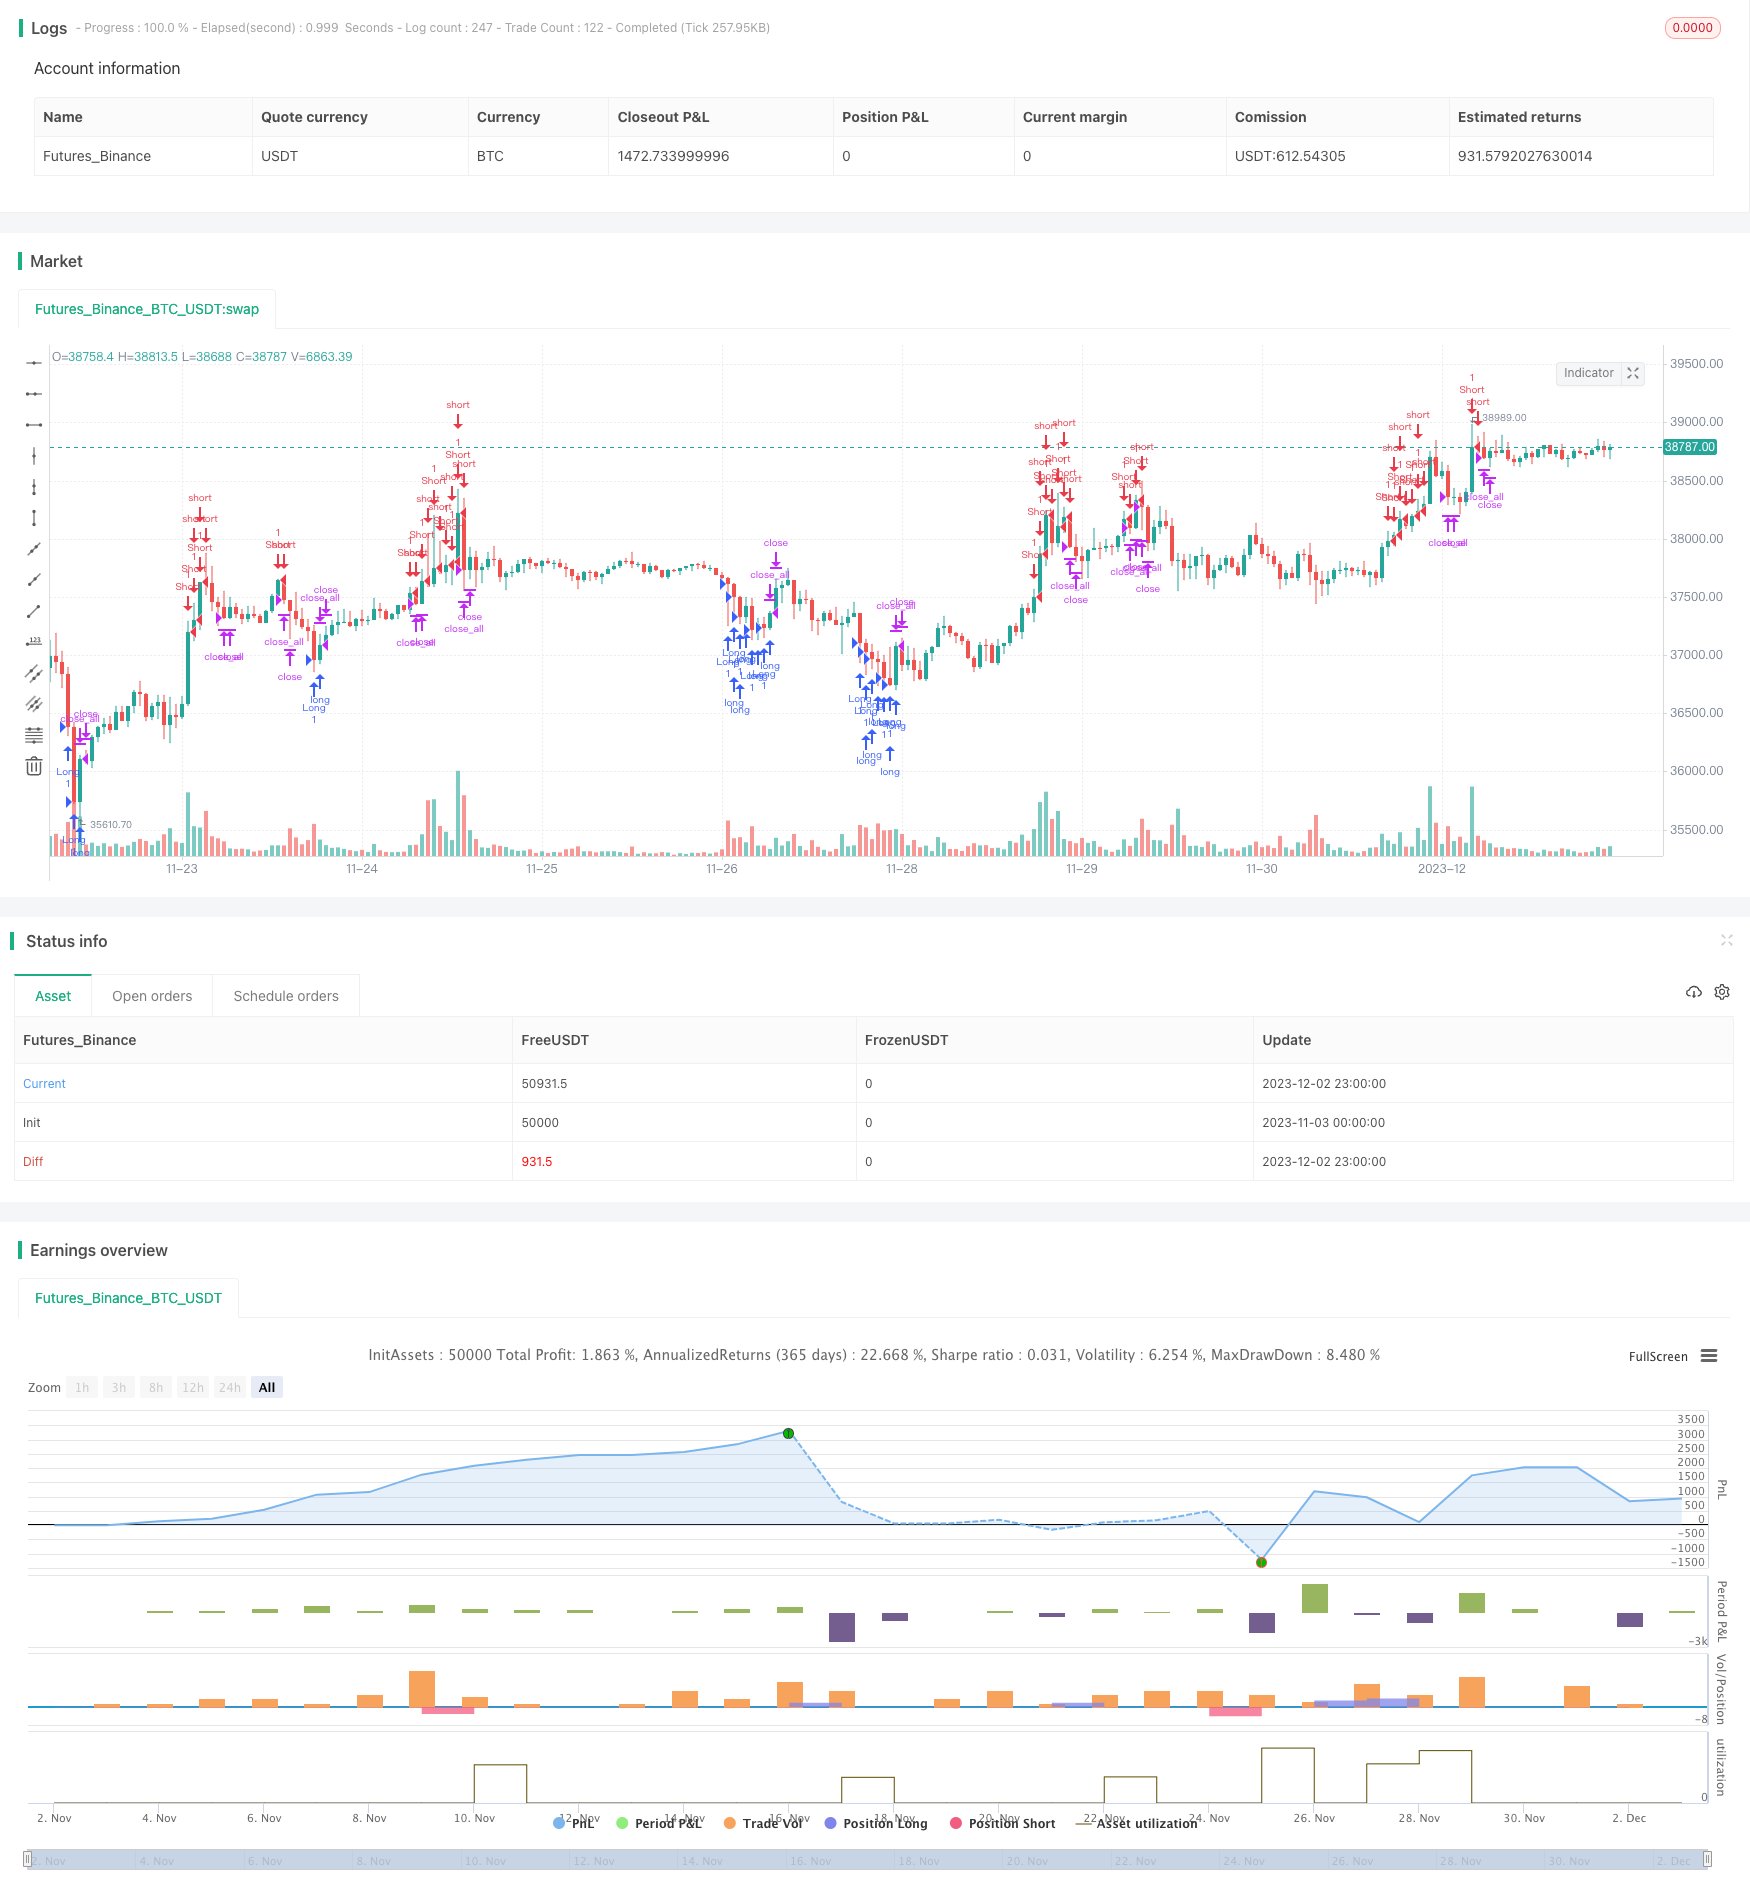
This strategy utilizes the RSI indicator to determine price trends quickly. It has both long and short capabilities to capture faster short-term price levels.
Strategy Name
Extreme Dual-Directional RSI Trend Strategy
Overview
This strategy utilizes the RSI indicator to determine price trends quickly. It has both long and short capabilities to capture faster short-term price levels.
Strategy Principle
The strategy uses an improved RSI indicator to judge the overbought and oversold status of prices, combined with candle body filtering to reduce noise. It goes long or short when the RSI is in the overbought or oversold zone and the candle body size is greater than 1/3 of the average body size. It closes positions when the candle reverses direction and the RSI pulls back to safer levels after the trading signals trigger.
Advantage Analysis
The strategy responds swiftly and can capture faster short-term trends. Meanwhile, the body filtering helps reduce noise and avoid being misled by false breakouts. It suits high volatility products well and can achieve higher returns.
Risk Analysis
The strategy is quite sensitive to price changes, easily misguided by false signals in the market. Also, stop losses may trigger frequently in the high volatility market. We can loosen the stop loss range and optimize RSI parameters to lower the false signal probability.
Optimization Directions
We can test different periodic parameters of the indicators to optimize the strategy and find the best parameter combination. Also, incorporating other indicators like the Turtle Trading rules may aid further in filtering signals. Training better RSI thresholds via machine learning methods could also be a worthwhile attempt.
Summary
Overall, this is an efficient and responsive short-term strategy. With some parameter and model optimization, it has the potential to further enhance stability and profitability. It merits continued research and tracking by quant traders.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Long |
| v_input_2 | true | Short |
| v_input_3 | 7 | RSI Period |
| v_input_4 | 30 | RSI limit |
| v_input_5_close | 0 | RSI Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_6 | 2018 | From Year |
| v_input_7 | 2100 | To Year |
| v_input_8 | true | From Month |
| v_input_9 | 12 | To Month |
| v_input_10 | true | From day |
| v_input_11 | 31 | To day |
Source Pine Script
/*backtest
start: 2023-11-03 00:00:00
end: 2023-12-03 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy(title = "Noro's Fast RSI Strategy v1.1", shorttitle = "Fast RSI str 1.1", overlay = true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, pyramiding = 5)

//Settings
needlong = input(true, defval = true, title = "Long")
needshort = input(true, defval = true, title = "Short")
rsiperiod = input(7, defval = 7, minval = 2, maxval = 50, title = "RSI Period")
limit = input(30, defval = 30, minval = 1, maxval = 100, title = "RSI limit")
rsisrc = input(close, defval = close, title = "RSI Source")
fromyear = input(2018, defval = 2018, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2100, defval = 2100, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To day")

//Fast RSI
fastup = rma(max(change(rsisrc), 0), rsiperiod)
fastdown = rma(-min(change(rsisrc), 0), rsiperiod)
fastrsi = fastdown == 0 ? 100 : fastup == 0 ? 0 : 100 - (100 / (1 + fastup / fastdown))
uplimit = 100 - limit
dnlimit = limit

//Body
body = abs(close - open)
emabody = ema(body, 30) / 3

//Signals
bar = close > open ? 1 : close < open ? -1 : 0
up = bar == -1 and fastrsi < dnlimit and body > emabody
dn = bar == 1 and fastrsi > uplimit and body > emabody
exit = ((strategy.position_size > 0 and fastrsi > dnlimit) or (strategy.position_size < 0 and fastrsi < uplimit)) and body > emabody

//Trading
if up
    strategy.entry("Long", strategy.long, needlong == false ? 0 : na, when=(time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 00, 00)))

if dn
    strategy.entry("Short", strategy.short, needshort == false ? 0 : na, when=(time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 00, 00)))

if time > timestamp(toyear, tomonth, today, 00, 00) or exit
    strategy.close_all()
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Fast-RSI-Strategy-Analysis.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- EMA and RSI Quantitative Trading StrategyPine Script · Machine learning · 1h
- MACD Robot Trading StrategyPine Script · Machine learning · 1d
- Multi Indicator Dynamic Adaptive Quantitative Trading StrategyPine Script · Machine learning · 1h
- Triple Moving Average Combined with MACD Quantitative StrategyPine Script · Machine learning · 1d
- kNN based Trend Following StrategyPine Script · Machine learning · 1h