Strategy vault / Machine learning
Fibonacci Retracement Dynamic Stop Loss Strategy
This strategy utilizes the Fibonacci retracement levels to automatically set stop loss and take profit prices for position management. It allows to ride trends for greater profits while mitigating losses during…
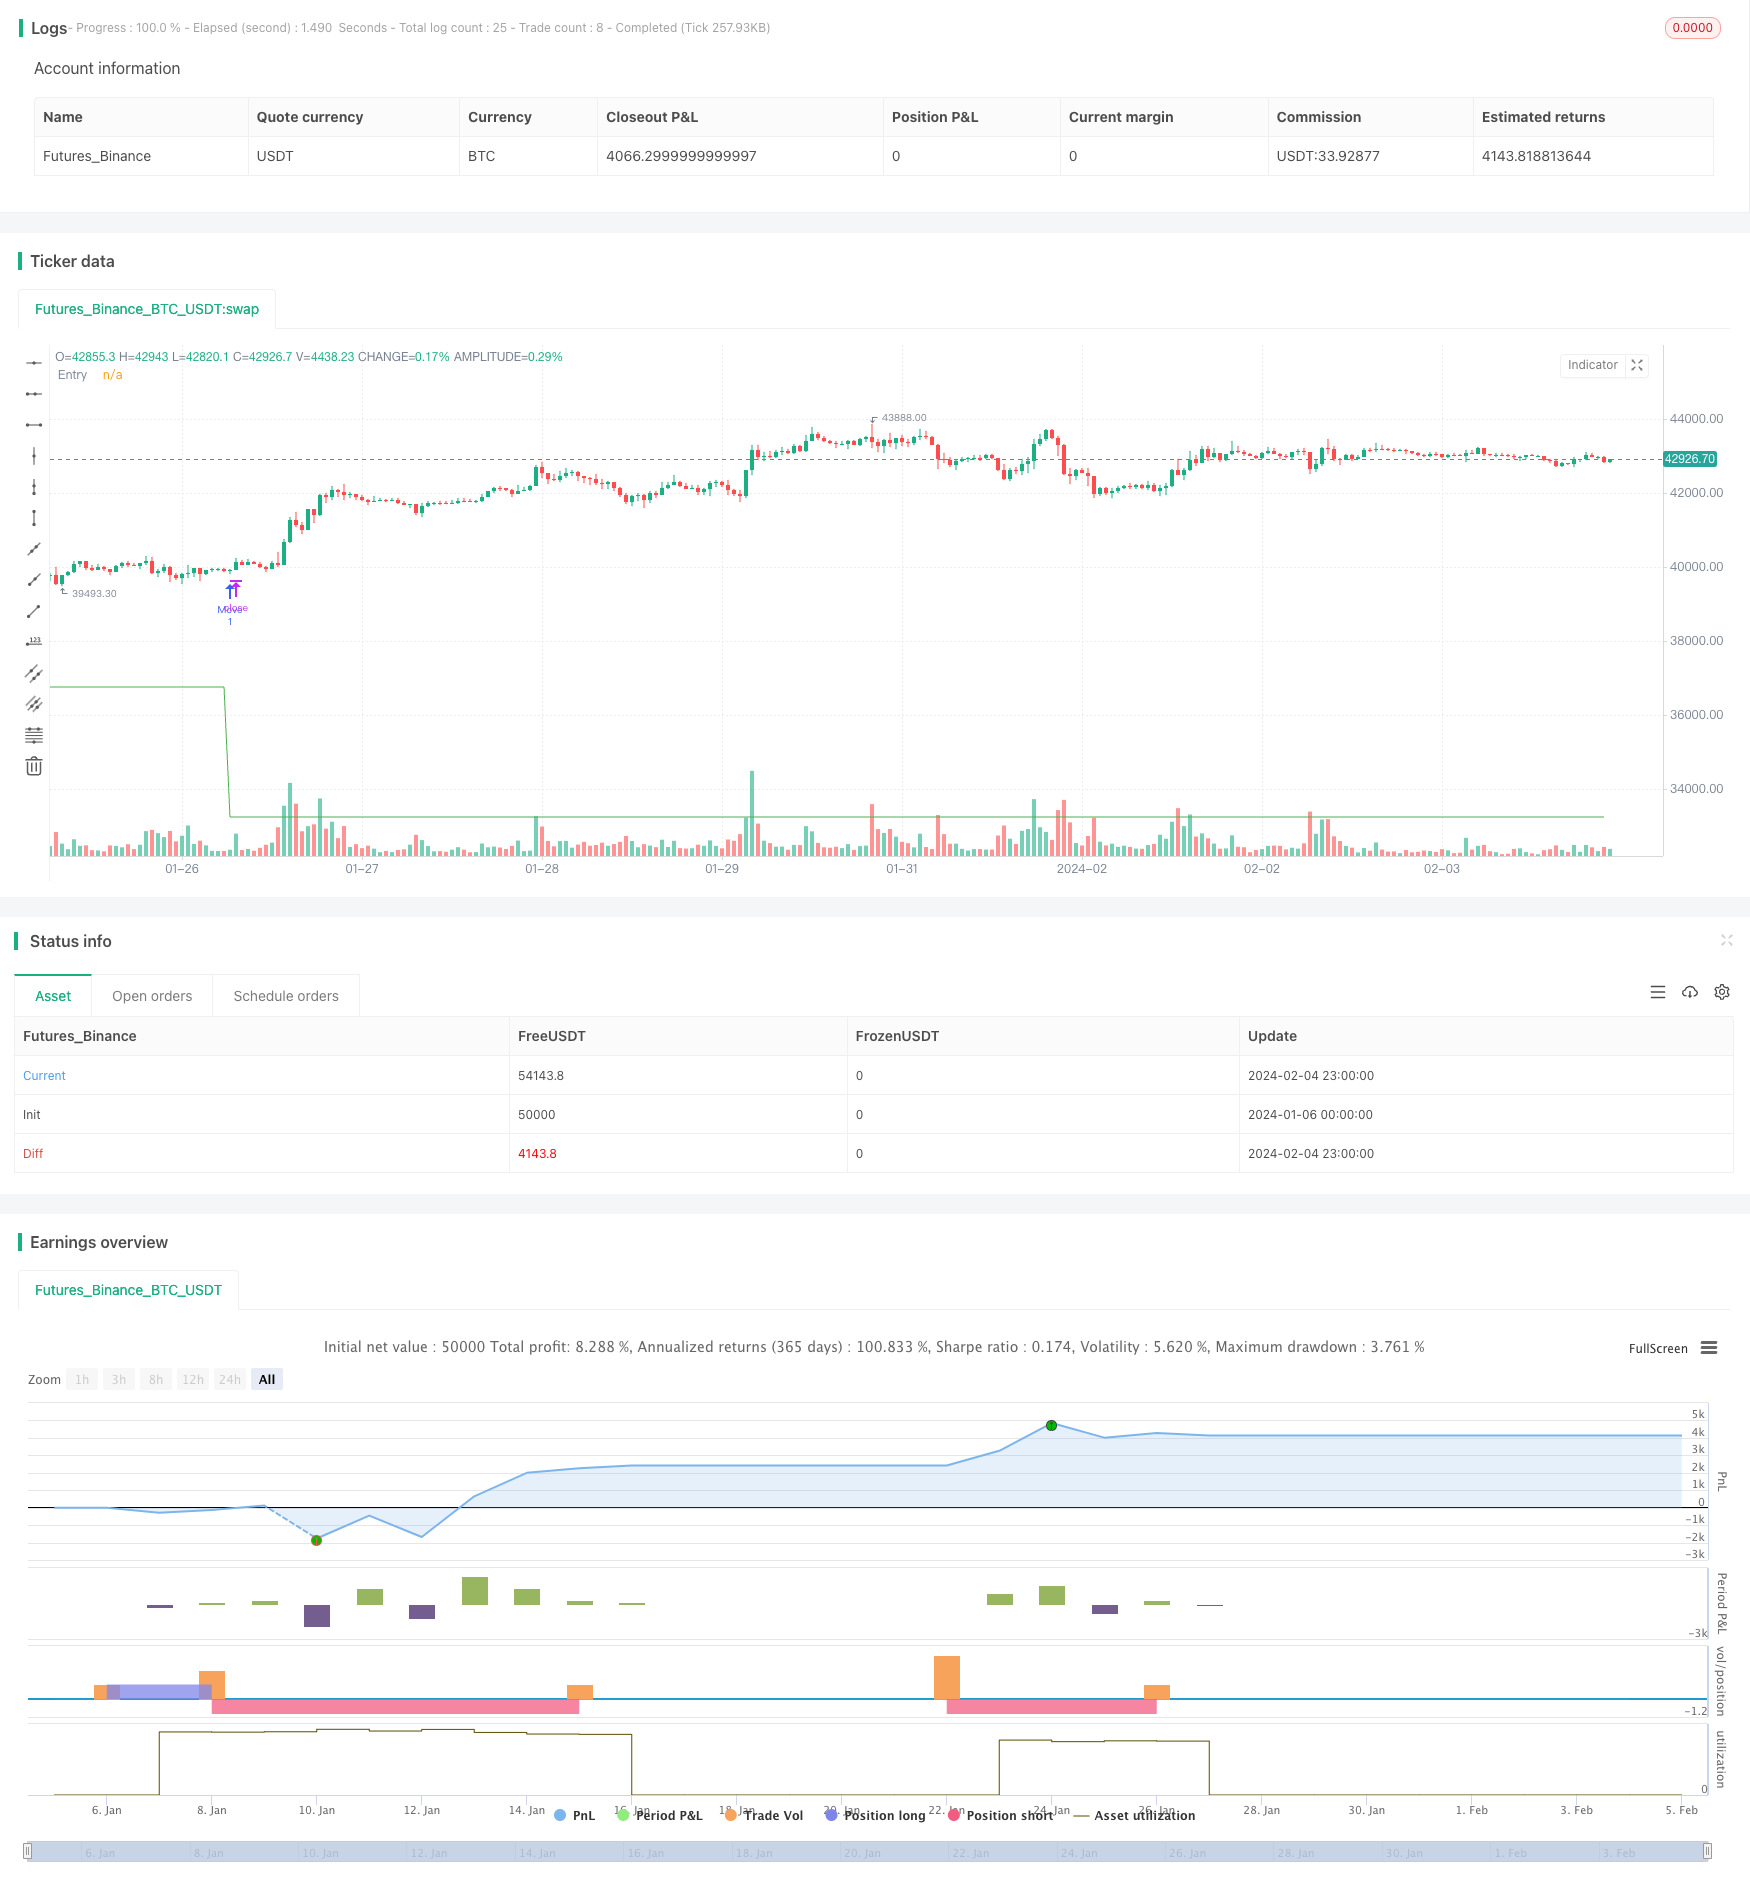
Overview
This strategy utilizes the Fibonacci retracement levels to automatically set stop loss and take profit prices for position management. It allows to ride trends for greater profits while mitigating losses during consolidation.
Strategy Logic
The core of this strategy relies on the Fibonacci retracement indicator to determine key support and resistance levels. It tracks the recent highs and lows to plot 10 Fibonacci price zones. Based on configuration, one of the Fibonacci levels is chosen as the entry trigger. When price breaks above that level, a long order will be placed based on the configured leverage. At the same time, a take profit price is set at certain percentage above the entry price.
After entry, the strategy keeps tracking the updated Fibonacci levels. If a lower Fib level emerges, indicating potential reversal, the strategy will cancel existing orders and re-place orders at the lower price as a stop loss mechanism. When the price eventually breaks above the take profit price, the position will be closed for profit.
Advantages
The biggest advantage of this strategy is the ability to dynamically adjust stop loss and take profit prices for trending markets. Key traits:
Capture greater profits in trending conditions by trailing stops based on entry price.
Mitigate losses in consolidation by stopping out at emerging lower Fib levels.
Allow pyramiding by adding to position when price drops certain percentage from last entry price.
Simple to operate with automatic order placement once configured correctly.
Risks
There are still some risks to be aware of:
Prone to repeated stops during sideways markets, increasing fees.
No fixed stop loss mechanism, risks large drawdowns.
Uncapped pyramiding might exacerbate losses.
Corresponding solutions:
Pause trading when price oscillating in range.
Manually overseer markets and close positions if necessary.
Set limits on pyramiding orders.
Enhancement Opportunities
There remains ample room for optimization:
Add additional indicators like EMA, MACD for extra entry confirmation to avoid false breakouts.
Incorporate fixed/trailing stop loss mechanisms to limit losses in extreme conditions.
Refine pyramiding logic based on market regimes to prevent over-leveraging.
Employ machine learning models like LSTM to forecast price and identify better entry/exits.
Conclusion
In summary, this strategy is suitable for trend-fading scenarios. By constantly adjusting stops it allows riding trends effectively. Proper optimizations and guard rails are needed handling more tricky market conditions.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | false | Live |
| v_input_2 | 1600976975 | Start Timestamp |
| v_input_3 | 60 | Start Delay |
| v_input_4 | true | Leverage |
| v_input_5 | true | Take Profit % |
| v_input_6 | -1 | DCA when < % |
| v_input_7 | 0 | Entry Level: 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| v_input_8 | 60 | Pivot Length |
Source Pine Script
/*backtest
start: 2024-01-06 00:00:00
end: 2024-02-05 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © CryptoRox

//@version=4
//Paste the line below in your alerts to run the built-in commands.
//{{strategy.order.alert_message}}
strategy(title="Fibs limit only", shorttitle="Strategy", overlay=true, precision=8, pyramiding=1000, commission_type=strategy.commission.percent, commission_value=0.04)

//Settings
testing = input(false, "Live")
//Use epochconverter or something similar to get the current timestamp.
starttime = input(1600976975, "Start Timestamp") * 1000
//Wait XX seconds from that timestamp before the strategy starts looking for an entry.
seconds = input(60, "Start Delay") * 1000
testPeriod = true


leverage = input(1, "Leverage")
tp = input(1.0, "Take Profit %") / leverage
dca = input(-1.0, "DCA when < %") / leverage *-1
fibEntry = input("1", "Entry Level", options=["1", "2", "3", "4", "5", "6", "7", "8", "9", "10"])

//Strategy Calls
equity = strategy.equity
avg = strategy.position_avg_price
symbol = syminfo.tickerid
openTrades = strategy.opentrades
closedTrades = strategy.closedtrades
size = strategy.position_size

//Fibs
lentt = input(60, "Pivot Length")
h = highest(lentt)
h1 = dev(h, lentt) ? na : h
hpivot = fixnan(h1)
l = lowest(lentt)
l1 = dev(l, lentt) ? na : l
lpivot = fixnan(l1)
z = 400
p_offset= 2
transp = 60
a=(lowest(z)+highest(z))/2
b=lowest(z)
c=highest(z)

fib0 = (((hpivot - lpivot)) + lpivot)
fib1 = (((hpivot - lpivot)*.21) + lpivot)
fib2 = (((hpivot - lpivot)*.3) + lpivot)
fib3 = (((hpivot - lpivot)*.5) + lpivot)
fib4 = (((hpivot - lpivot)*.62) + lpivot)
fib5 = (((hpivot - lpivot)*.7) + lpivot)
fib6 = (((hpivot - lpivot)* 1.00) + lpivot)
fib7 = (((hpivot - lpivot)* 1.27) + lpivot)
fib8 = (((hpivot - lpivot)* 2) + lpivot)
fib9 = (((hpivot - lpivot)* -.27) + lpivot)
fib10 = (((hpivot - lpivot)* -1) + lpivot)

notna = nz(fib10[60])
entry = 0.0
if fibEntry == "1"
    entry := fib10
if fibEntry == "2"
    entry := fib9
if fibEntry == "3"
    entry := fib0
if fibEntry == "4"
    entry := fib1
if fibEntry == "5"
    entry := fib2
if fibEntry == "6"
    entry := fib3
if fibEntry == "7"
    entry := fib4
if fibEntry == "8"
    entry := fib5
if fibEntry == "9"
    entry := fib6
if fibEntry == "10"
    entry := fib7
profit = avg+avg*(tp/100)
pause = 0
pause := nz(pause[1])
paused = time < pause

fill = 0.0
fill := nz(fill[1])
count = 0.0
count := nz(fill[1])

filled = count > 0 ? entry > fill-fill/100*dca : 0
signal = testPeriod and notna and not paused and not filled ? 1 : 0

neworder = crossover(signal, signal[1])
moveorder = entry != entry[1] and signal and not neworder ? true : false
cancelorder = crossunder(signal, signal[1]) and not paused
filledorder = crossunder(low[1], entry[1]) and signal[1]

last_profit = 0.0
last_profit := nz(last_profit[1])

if neworder and signal
    strategy.order("New", 1, 0.0001, alert_message='New Order|e=binancefuturestestnet s=btcusdt b=long q=0.0011 fp=' + tostring(entry))
if moveorder
    strategy.order("Move", 1, 0.0001, alert_message='Move Order|e=binancefuturestestnet s=btcusdt b=long c=order|e=binancefuturestestnet s=btcusdt b=long q=0.0011 fp=' + tostring(entry))
if filledorder and size < 1
    fill := entry
    count := count+1
    pause := time + 60000
    p = close+close*(tp/100)
    strategy.entry("Filled", 1, 1,  alert_message='Long Filled|e=binancefuturestestnet s=btcusdt b=short c=order|delay=1|e=binancefuturestestnet s=btcusdt b=long c=position q=100% ro=1 fp=' + tostring(p))
if filledorder and size >= 1
    fill := entry
    count := count+1
    pause := time + 60000
    strategy.entry("Filled", 1, 1,  alert_message='Long Filled|e=binancefuturestestnet s=btcusdt b=short c=order|delay=1|e=binancefuturestestnet s=btcusdt b=long c=position q=100% ro=1 fp=' + tostring(profit))

if cancelorder and not filledorder
    pause := time + 60000
    strategy.order("Cancel", 1, 0.0001,  alert_message='Cancel Order|e=binancefuturestestnet s=btcusdt b=long c=order')

if filledorder
    last_profit := profit

closeit = crossover(high, profit) and size >= 1
if closeit
    strategy.entry("Close ALL", 0, 0, alert_message='Profit')
    count := 0
    fill := 0.0
    last_profit := 0.0

//Plots
bottom = signal ? color.green : filled ? color.red : color.white
plot(entry, "Entry", bottom)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Fibonacci-Retracement-Dynamic-Stop-Loss-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Level Balanced Quantitative Trading StrategyPine Script · Machine learning · 1d
- Multi Indicator Decision Tree Strategy IMACD EMA and IchimokuPine Script · Machine learning · 30m
- Multi indicator Assisted StrategyPine Script · Machine learning · 1d
- Octa EMA and Ichimoku Cloud Quantitative Trading StrategyPine Script · Machine learning · 1d
- EMA Pullback StrategyPine Script · Machine learning · 1h
- Multi factor Quantitative Trading StrategyPine Script · Machine learning · 1d