Fisher Turnaround EMA Multi Take Profit and Multi Stop Strategy
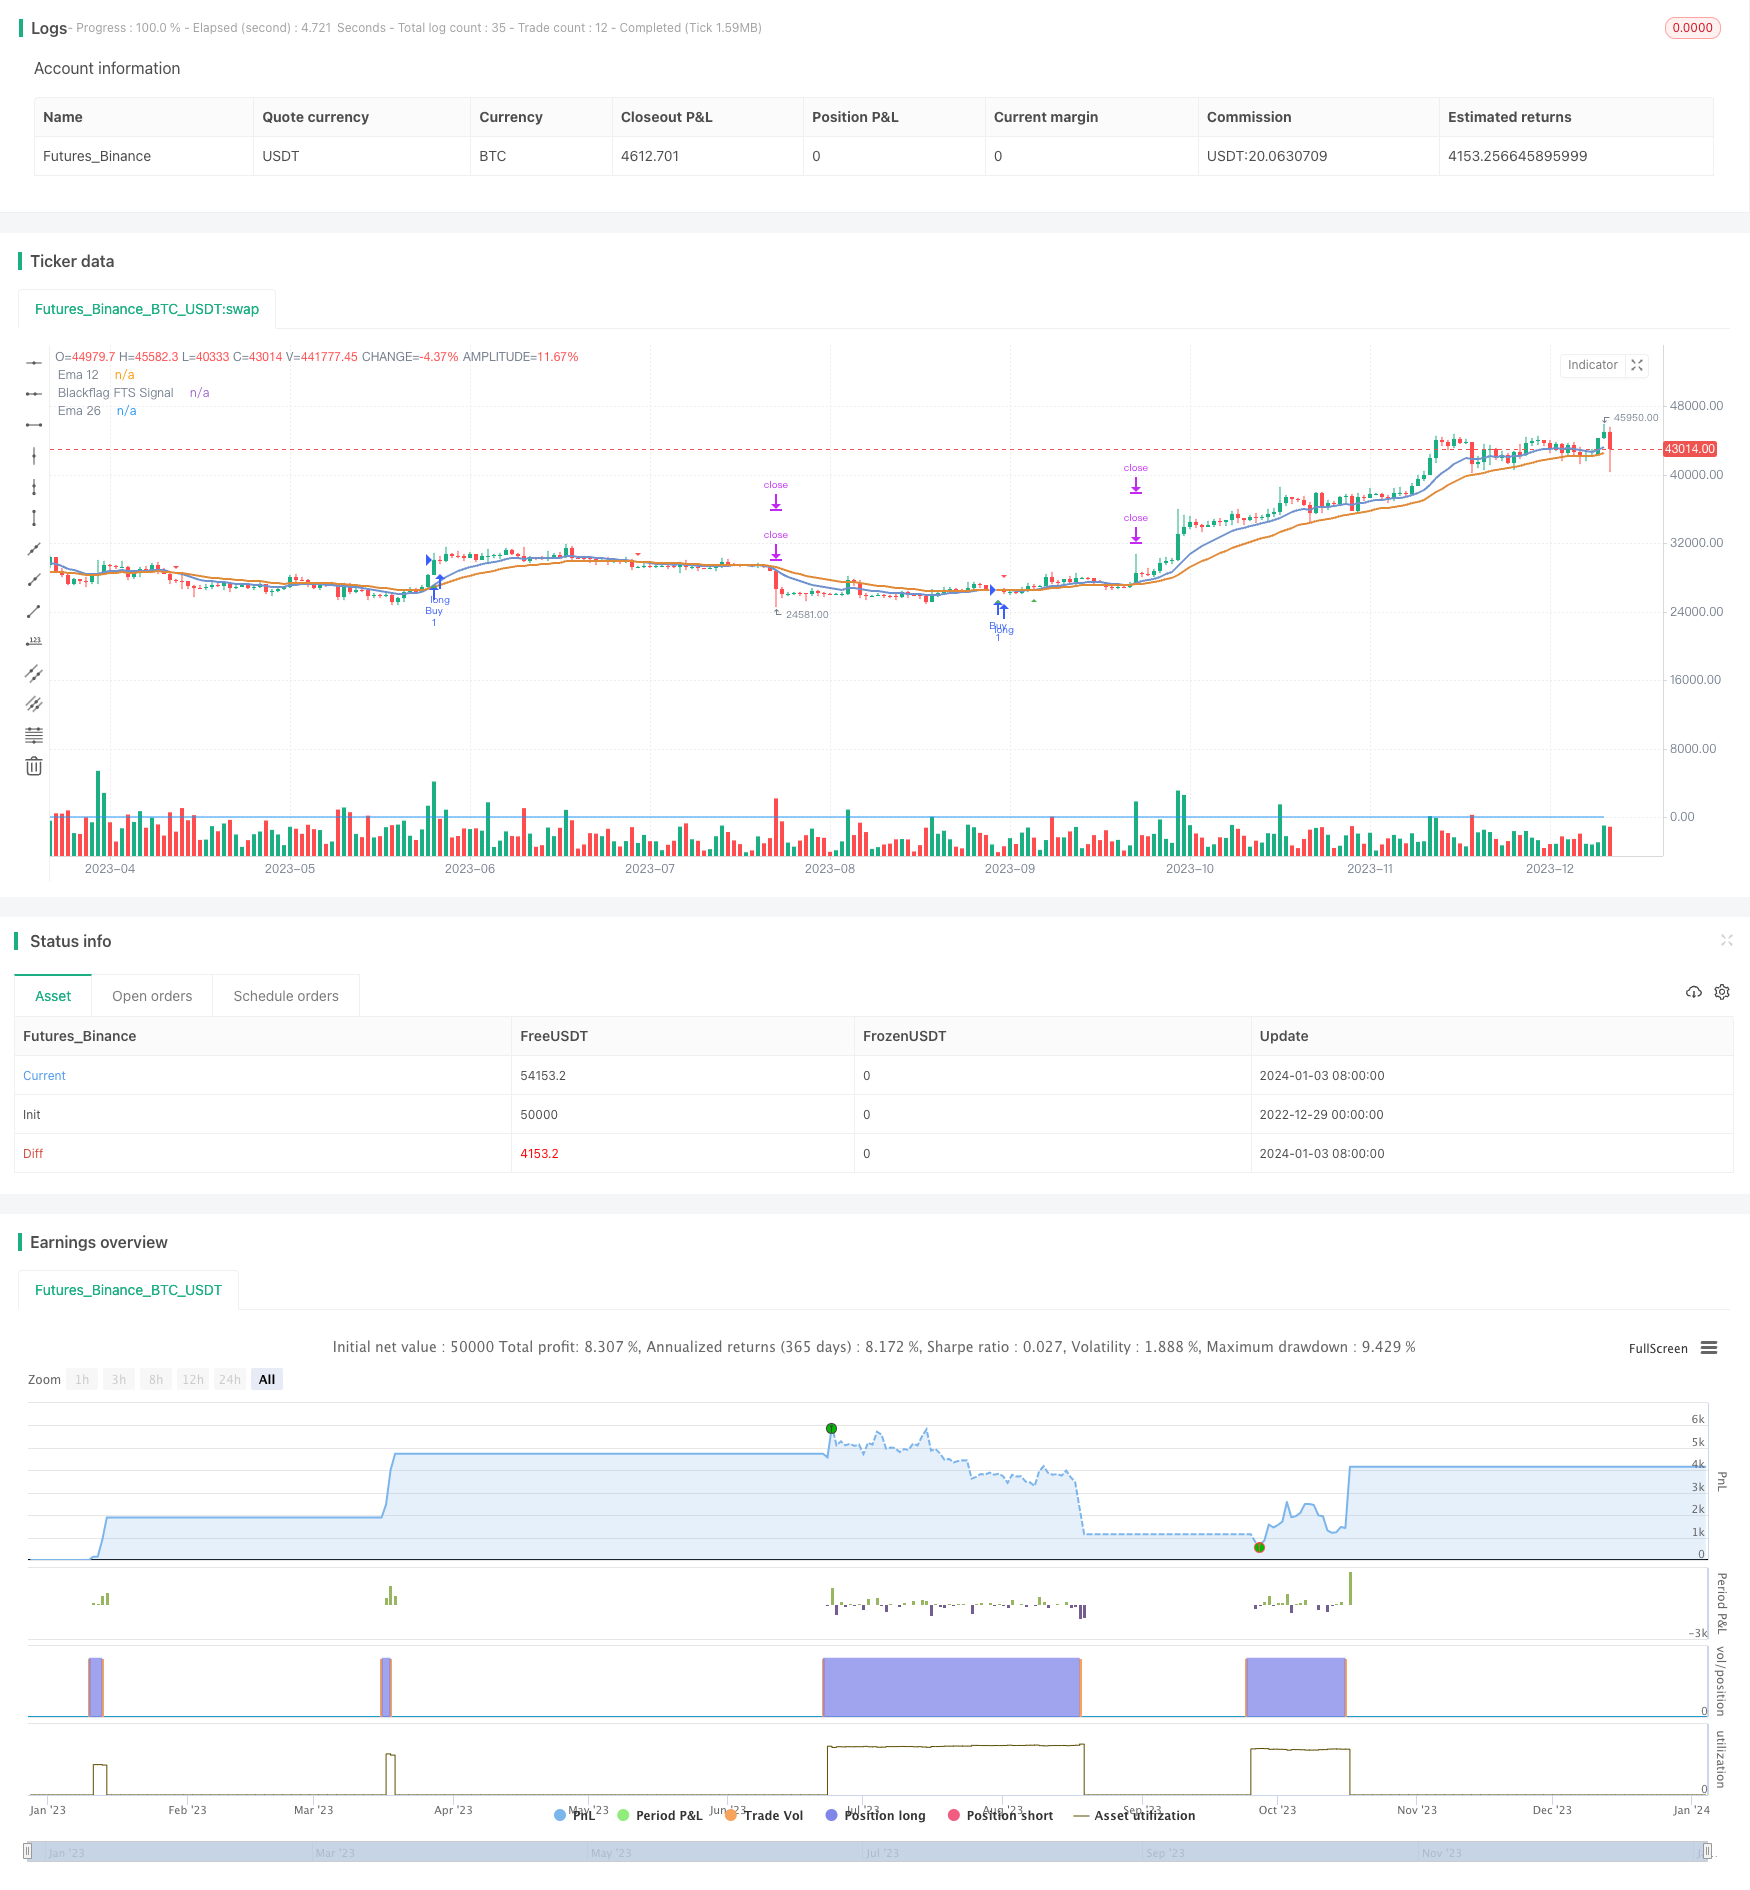
The Fisher Turnaround EMA Multi-Take Profit and Multi-Stop Strategy combines the EMA indicator and a custom Fisher Turn signal to implement trend tracking trades. It generates buy signals when the short period EMA…
Overview
The Fisher Turnaround EMA Multi-Take Profit and Multi-Stop Strategy combines the EMA indicator and a custom Fisher Turn signal to implement trend tracking trades. It generates buy signals when the short period EMA crosses above the long period EMA and the Fisher Turn signal is greater than 0. The strategy sets two take profit levels and one dynamic stop loss to lock in profits and control risks. The first take profit is 2xATR, the second 3xATR, and the stop loss is 1xATR. After the first take profit is triggered, the stop loss will move to the entry price. This strategy is suitable for the GDAX exchange to find potential trend trading opportunities.
Strategy Logic
The strategy is mainly based on two technical indicators:
- EMA: Exponential Moving Average. The strategy uses 12 and 26 period EMAs.
- Custom Fisher Turn signal. This signal is calculated based on the difference between the highs and lows over a certain period.
Buy signals are generated when the short period EMA crosses above the long period EMA. In addition, the Fisher Turn signal line must also be greater than 0, indicating the current uptrend.
The take profit and stop loss rules are as follows:
- First take profit at 2xATR
- Second take profit at 3xATR
- Stop loss at 1xATR
- After the first take profit is triggered, the stop loss will move to the entry price.
The strategy can be optimized by adjusting parameters like EMA periods, Fisher Turn signal periods, and ATR periods.
Advantages
By combining trend tracking indicators and risk management indicators, this strategy has the following advantages:
- Using EMA to capture trend direction
- Custom Fisher Turn signal filters fake breakouts
- Multiple take profit levels to lock in profits
- Dynamic stop loss to control risks
- Adjustable parameters adapt to different market environments
Risks
There are also some risks to this strategy:
- Trend reversal triggers stop loss
- Improper parameter settings cause over-aggressive entries or premature exits
- Custom Fisher Turn signal may fail in certain market environments
These risks can be reduced through parameter optimization, combining other indicators, manual intervention etc.
Optimization Directions
The strategy can be optimized in the following aspects:
- Optimize EMA period parameters to adapt more market environments
- Add other trend indicators to verify buy signals
- Incorporate overall market filters to avoid uncertain environments
- Optimize Fisher Turn signal parameters or try other custom indicators
- Add more take profit levels to lock in more profits
- Integrate auto trailing stop loss function
By testing different parameter settings and indicator combinations, the strategy performance can be continuously improved.
Conclusion
The Fisher Turnaround EMA Multi-Take Profit and Multi-Stop Strategy integrates the strengths of trend tracking and risk management. With great potential for long-term verification and optimization, it is a promising strategy. There is still ample room for optimizing parameters and combining indicators to achieve steady outperformance in live trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | Blackflag FTS Length |
| v_input_2 | 14 | ATR Length |
Source Pine Script
/*backtest
start: 2022-12-29 00:00:00
end: 2024-01-04 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Eliebf13
//@version=4
strategy("GDAX EMA & Blackflag FTS Strategy with Multiple Take Profits and Dynamic Stop Loss", overlay=true)

// Input parameters for Blackflag FTS
fts_length = input(14, title="Blackflag FTS Length")
atr_length = input(14, title="ATR Length")

// GDAX EMA calculation
short = ema(close, 12)
long = ema(close, 26)

// Calculate Blackflag FTS signal line manually
up = 0.0
down = 0.0
for i = 0 to fts_length - 1
    up := up + (high[i] - low[i])
    down := down + (high[i] - low[i])

fts_value = down == 0 ? 100 : 100 - (100 / (1 + (up / down)))

// Buy condition: GDAX EMA crossover and Blackflag FTS signal above zero
buy_condition = crossover(short, long) and fts_value > 0

// ATR calculation
atr_value = atr(atr_length)

// Calculate Stop Loss and Take Profit levels
stop_loss_level = close - atr_value
take_profit_level1 = close + 2 * atr_value
take_profit_level2 = close + 3 * atr_value

// Sell condition: GDAX EMA crossunder or Blackflag FTS signal below zero
sell_condition = crossunder(short, long) or fts_value < 0

// Strategy orders with Multiple Take Profits and Dynamic Stop Loss
strategy.entry("Buy", strategy.long, when = buy_condition)

// Calculate position size for 50% closure at each take profit level
position_size = strategy.position_size
target_position_size1 = position_size * 0.5
target_position_size2 = position_size * 1

strategy.exit("Take Profit 1", from_entry="Buy", loss=close, profit=take_profit_level1, qty=target_position_size1)
strategy.exit("Take Profit 2/Move Stop Loss", from_entry="Buy", loss=close, profit=take_profit_level2, qty=target_position_size2)

// Plot GDAX EMA lines
plot(short, color=#6f92ce, linewidth=2, title="Ema 12")
plot(long, color=#e08937, linewidth=2, title="Ema 26")

// Plot Blackflag FTS signal
plot(fts_value, color=color.blue, title="Blackflag FTS Signal")

// Plot buy and sell signals on the chart
plotshape(series=buy_condition, location=location.belowbar, color=color.green, style=shape.triangleup, title="Buy Signal")
plotshape(series=sell_condition, location=location.abovebar, color=color.red, style=shape.triangledown, title="Sell Signal")Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-05. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Fisher-Turnaround-EMA-Multi-Take-Profit-and-Multi-Stop-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- BB Breakout StrategyPine Script · Breakout · 1d
- Donchian Channel and Larry Williams Large Trade Index StrategyPine Script · Breakout · 1m
- Dual Breakout Volatility Channel StrategyPine Script · Breakout · 1h
- Dual MA Momentum Breakout StrategyPine Script · Breakout · 1h
- Dynamic ATR Trend Following Strategy Based on Support BreakoutPine Script · Breakout · 1d
- Dynamic ATR based Trailing Stop Trading StrategyPine Script · Breakout · 1d