Strategy vault / Trend following
Flexible MA VWAP Crossover Strategy with Stop Loss Take Profit
This strategy identifies crossovers between fast moving average, slow moving average and volume weighted average price (VWAP) to capture potential price movements. It triggers buy signals when fast MA crosses above…
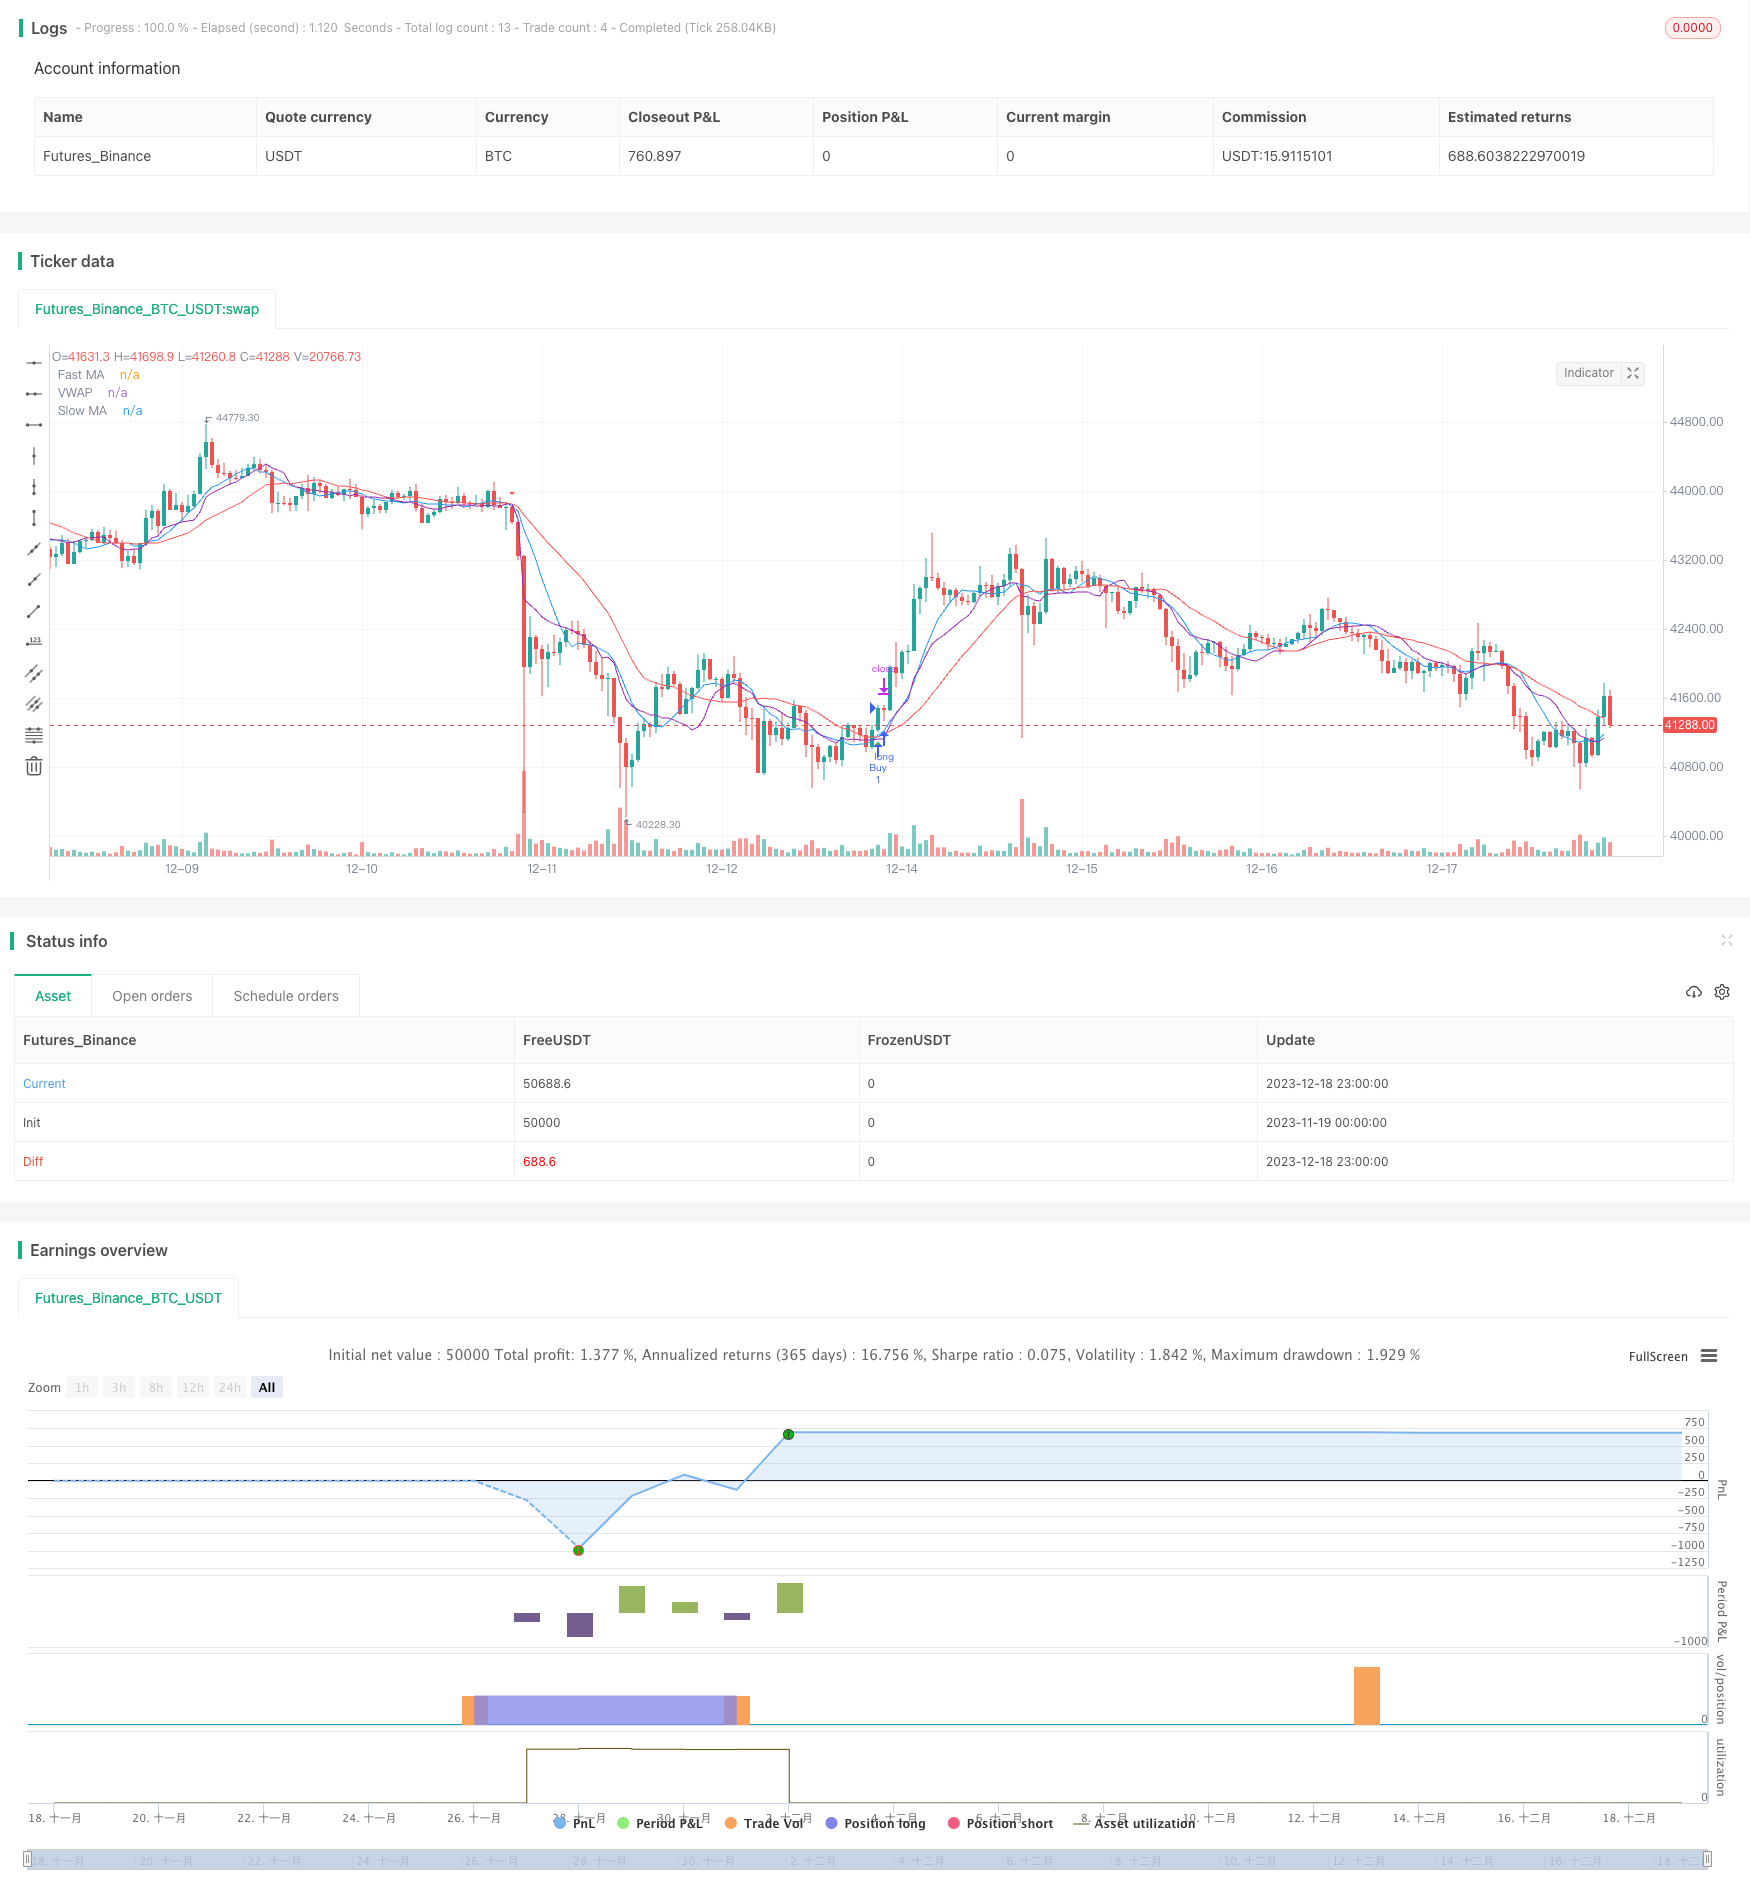
Overview
This strategy identifies crossovers between fast moving average, slow moving average and volume weighted average price (VWAP) to capture potential price movements. It triggers buy signals when fast MA crosses above VWAP and slow MA, and sell signals when fast MA crosses below VWAP and slow MA.
Strategy Logic
The strategy combines the strengths of moving averages and VWAP. Moving averages can effectively filter out market noise and determine trend direction. VWAP reflects intentions of big money more precisely. Fast MA captures short-term trend while slow MA filters out false signals. When fast MA crosses above slow MA and VWAP, it indicates bullish short-term trend and triggers buy signals. Below crossover triggers sell signals.
Advantage Analysis
- Dual MA filter reduces false signals
- VWAP accurately judges intentions of big money
- Flexible MA parameters adapt to different periods
- Effective risk control with stop loss/take profit
Risk Analysis
- Whipsaw markets may generate multiple false signals
- Inaccurate VWAP parameters fail to judge fund intent
- Stop loss too tight unable to trace trends, too loose risks excess
Optimization Directions
- Optimize MA and VWAP parameters for different market conditions
- Additional filter signals with RSI
- Dynamic stop loss/take profit ratios
Conclusion
This strategy integrates the strengths of moving averages and VWAP, identifies crossover signals through dual filtering, and effectively controls risks with flexible stop loss/take profit mechanisms. It is a recommended trend following strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 9 | Fast MA Length |
| v_input_2 | 21 | Slow MA Length |
| v_input_3 | 14 | VWAP Length |
| v_input_4 | true | Stop Loss (%) |
| v_input_5 | 2 | Take Profit (%) |
Source Pine Script
/*backtest
start: 2023-11-19 00:00:00
end: 2023-12-19 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("Flexible MA VWAP Crossover Strategy with SL/TP", shorttitle="MA VWAP Crossover", overlay=true)

// Input parameters
fast_length = input(9, title="Fast MA Length", minval=1)
slow_length = input(21, title="Slow MA Length", minval=1)
vwap_length = input(14, title="VWAP Length", minval=1)

// Stop Loss and Take Profit inputs
stop_loss_percent = input(1.0, title="Stop Loss (%)", minval=0.1, maxval=5.0, step=0.1)
take_profit_percent = input(2.0, title="Take Profit (%)", minval=1.0, maxval=10.0, step=0.1)

// Calculate moving averages
fast_ma = sma(close, fast_length)
slow_ma = sma(close, slow_length)
vwap = sma(close * volume, vwap_length) / sma(volume, vwap_length)

// Buy and sell conditions
buy_condition = crossover(fast_ma, vwap) and crossover(fast_ma, slow_ma)
sell_condition = crossunder(fast_ma, vwap) and crossunder(fast_ma, slow_ma)

// Plot the moving averages
plot(fast_ma, title="Fast MA", color=color.blue)
plot(slow_ma, title="Slow MA", color=color.red)
plot(vwap, title="VWAP", color=color.purple)

// Plot buy and sell signals
plotshape(buy_condition, style=shape.triangleup, location=location.belowbar, color=color.green, title="Buy Signal")
plotshape(sell_condition, style=shape.triangledown, location=location.abovebar, color=color.red, title="Sell Signal")

// Define stop loss and take profit levels
var float stop_loss_price = na
var float take_profit_price = na

if (buy_condition)
    stop_loss_price := close * (1 - stop_loss_percent / 100)
    take_profit_price := close * (1 + take_profit_percent / 100)

// Strategy entry and exit with flexible SL/TP
strategy.entry("Buy", strategy.long, when = buy_condition)

if (sell_condition)
    strategy.exit("SL/TP", from_entry = "Buy", stop = stop_loss_price, limit = take_profit_price)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Flexible-MA-VWAP-Crossover-Strategy-with-Stop-Loss-Take-Profit.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Trend StrategyPine Script · Trend following · 1m
- Trend Following Quant Trading Strategy Based on Moving AveragePine Script · Trend following · 1h
- Multi Period Trend Confirmation Dynamic Risk Control Quantitative Trading StrategyPine Script · Trend following · 1h
- MOST Indicator Dual Position Adaptive StrategyPine Script · Trend following · 4h
- Multi Timeframe Volume and Trend Confluence Trading StrategyPine Script · Trend following · 1d