Futures Candlestick Size Threshold Trading Strategy
This strategy identifies and trades significant price movements based on candlestick size. It achieves precise control through specific tick thresholds, trading time windows, and daily trade frequency limits. The…
Overview
This strategy identifies and trades significant price movements based on candlestick size. It achieves precise control through specific tick thresholds, trading time windows, and daily trade frequency limits. The strategy is specifically optimized for the futures market and can capture significant price movements during high liquidity periods.
Strategy Principle
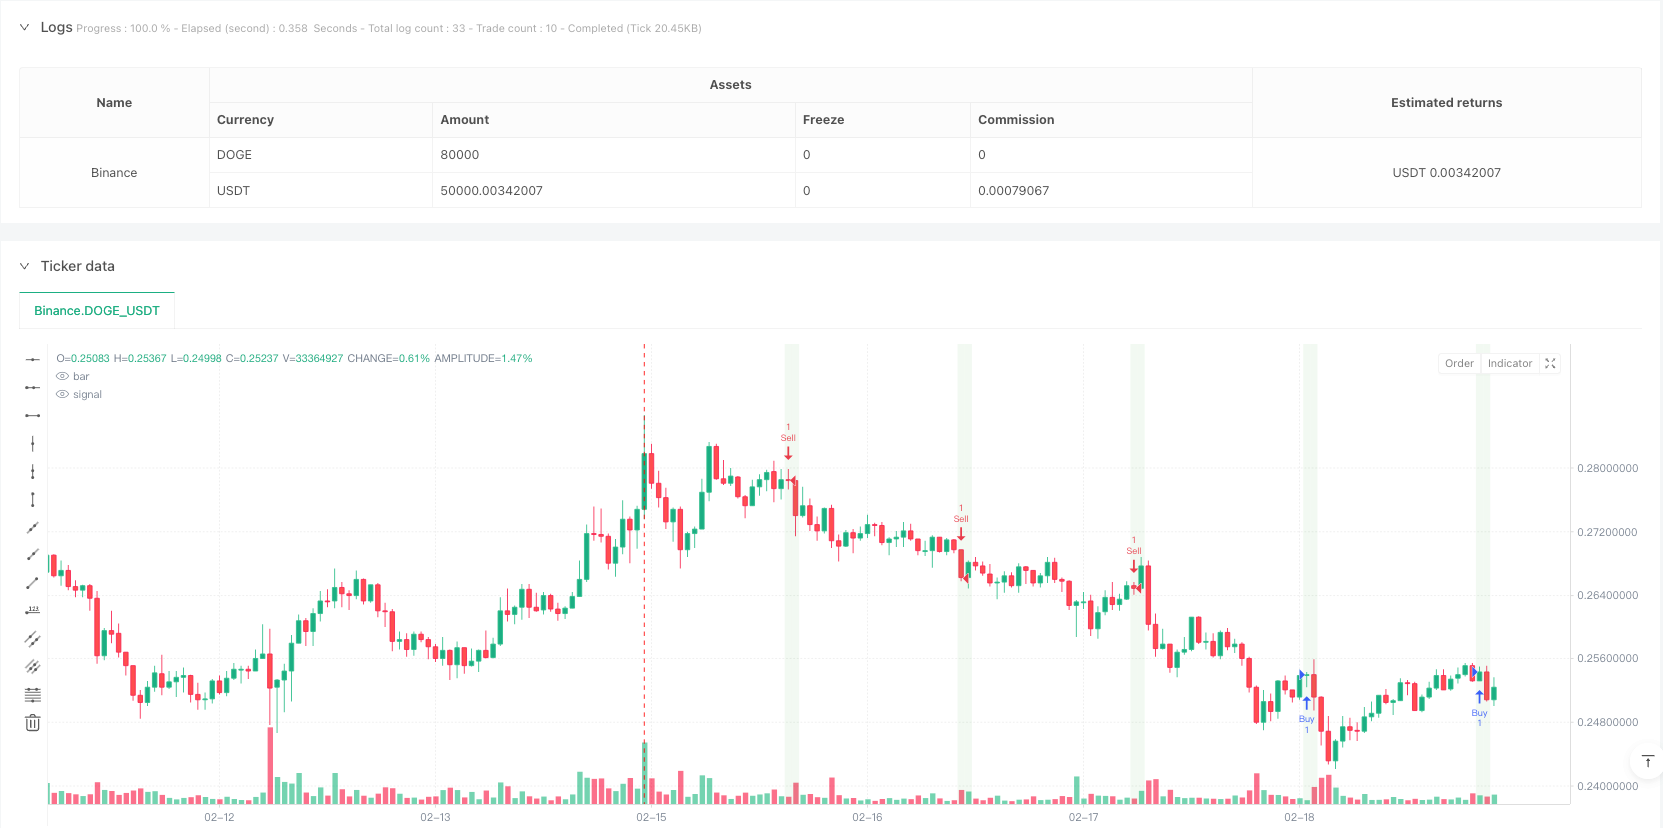
The core logic of the strategy is to calculate the high-low range of each candlestick (in ticks) and compare it with a preset threshold. When the candlestick size exceeds the threshold within the specified trading window (default 7:00-9:15 CST), the system triggers long or short trading signals based on the candlestick direction. To control risk, the strategy limits execution to one trade per day and sets take-profit and stop-loss levels.
Strategy Advantages
- Precise Tick Control - Ensures trading execution accuracy through tick-level calculations
- Time Filtering - Focuses on trading during periods of highest market activity
- Risk Management - Sets clear take-profit and stop-loss levels to protect capital
- Trade Frequency Control - Daily trade limit prevents overtrading
- Visual Alerts - Triggered candlesticks are highlighted for easy analysis
- Backtesting Compatibility - Includes date filtering and time execution features for historical testing
Strategy Risks
- Market Volatility Risk - May trigger false signals during periods of extreme volatility
- Slippage Risk - High-speed trading in futures markets may lead to execution price deviation
- Opportunity Cost - Daily trade limit may miss other good trading opportunities
- Time Dependency - Strategy effectiveness highly depends on chosen trading window
Strategy Optimization Directions
- Dynamic Threshold - Automatically adjust candlestick size threshold based on market volatility
- Multiple Timeframes - Add confirmation signals from multiple timeframes
- Volume Filter - Incorporate volume indicators as auxiliary judgment
- Market Sentiment Indicators - Integrate volatility indicators to assess market conditions
- Adaptive Take-Profit/Stop-Loss - Set dynamic exit levels based on market volatility
Summary
This strategy provides a reliable trading system for futures through precise tick control and strict time filtering. Its strengths lie in execution accuracy and risk control, but traders need to optimize parameters based on specific instruments and market conditions. Through the suggested optimization directions, the strategy can further enhance its adaptability and stability.
Source Pine Script
/*backtest
start: 2025-02-15 01:00:00
end: 2025-02-20 00:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Binance","currency":"DOGE_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © omnipadme

//@version=5
strategy("Futures Candle Size Strategy (Start Trading on Jan 1, 2025)", overlay=true)

// Input for candle size threshold in ticks
candleSizeThresholdTicks = input.float(25, title="Candle Size Threshold (Ticks)", minval=1)

// Input for take profit and stop loss in ticks
takeProfitTicks = input.float(50, title="Take Profit (Ticks)", minval=1)
stopLossTicks = input.float(40, title="Stop Loss (Ticks)", minval=1)

// Time filter for trading (e.g., 7:00 AM to 9:15 AM CST)
startHour = input.int(7, title="Start Hour (CST)", minval=0, maxval=23)
startMinute = input.int(0, title="Start Minute (CST)", minval=0, maxval=59)
endHour = input.int(9, title="End Hour (CST)", minval=0, maxval=23)
endMinute = input.int(15, title="End Minute (CST)", minval=0, maxval=59)

// Tick size of the instrument (e.g., ES = 0.25)
tickSize = syminfo.mintick

// Convert tick inputs to price levels
candleSizeThreshold = candleSizeThresholdTicks * tickSize
takeProfit = takeProfitTicks * tickSize
stopLoss = stopLossTicks * tickSize

// Time range calculation
startTime = timestamp("GMT-6", year(timenow), month(timenow), dayofmonth(timenow), startHour, startMinute)
endTime = timestamp("GMT-6", year(timenow), month(timenow), dayofmonth(timenow), endHour, endMinute)
inTimeRange = (time >= startTime and time <= endTime)

// Filter to start trading only from January 1, 2025
startTradingDate = timestamp("GMT-6", 2025, 1, 1, 0, 0)
isValidStartDate = time >= startTradingDate

// Calculate the candle size for the current candle
candleSize = math.abs(high - low)

// Track whether a trade has been executed for the day
var hasTradedToday = false
isNewDay = dayofweek != dayofweek[1]  // Detect new day

// Reset `hasTradedToday` at the start of a new day
if isNewDay
    hasTradedToday := false

// Trigger condition for futures trading (only if no trade has been executed today)
triggerCondition = isValidStartDate and inTimeRange and candleSize >= candleSizeThreshold and not hasTradedToday

// Entry logic: If condition is met, enter a trade
if triggerCondition
    hasTradedToday := true  // Mark as traded for the day
    if close > open  // Bullish candle
        strategy.entry("Buy", strategy.long)
    if close < open  // Bearish candle
        strategy.entry("Sell", strategy.short)

// Set take profit and stop loss
strategy.exit("Exit Long", from_entry="Buy", limit=close + takeProfit, stop=close - stopLoss)
strategy.exit("Exit Short", from_entry="Sell", limit=close - takeProfit, stop=close + stopLoss)

// Alerts for triggered condition
if triggerCondition
    alert("Candle size is " + str.tostring(candleSizeThresholdTicks) + " ticks or greater. Trade initiated.", alert.freq_once_per_bar)

// Color the alert candle white
barcolor(triggerCondition ? color.white : na)

// Visual aids for backtesting
bgcolor(isValidStartDate and inTimeRange ? color.new(color.green, 90) : na, title="Time and Date Range Highlight")
Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Futures-Candlestick-Size-Threshold-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Volatility Trading RSI EMA ATR StrategyPine Script · Volatility · 3m
- Bullish Engulfing Quantitative Trading System with Bollinger Bands Risk ManagementPine Script · Volatility · 1d
- Multi Indicator Dynamic Adaptive Position Sizing with ATR Volatility StrategyPine Script · Volatility · 2h
- Dual Bollinger Band Volatility Tracking StrategyPine Script · Volatility · 1d
- Dual EMA Volatility Adaptive Trading Strategy with Multi Tiered Profit Optimization SystemPine Script · Volatility · 1d
- Dual Moving Average Volatility Tracking StrategyPine Script · Volatility · 1h