Strategy vault / Trend following
Galileo Galileis Moving Average Crossover Strategy
Galileo Galilei's moving average crossover strategy is a trading strategy based on moving averages. It generates trading signals by calculating the exponential moving average (EMA) over a specified period and…
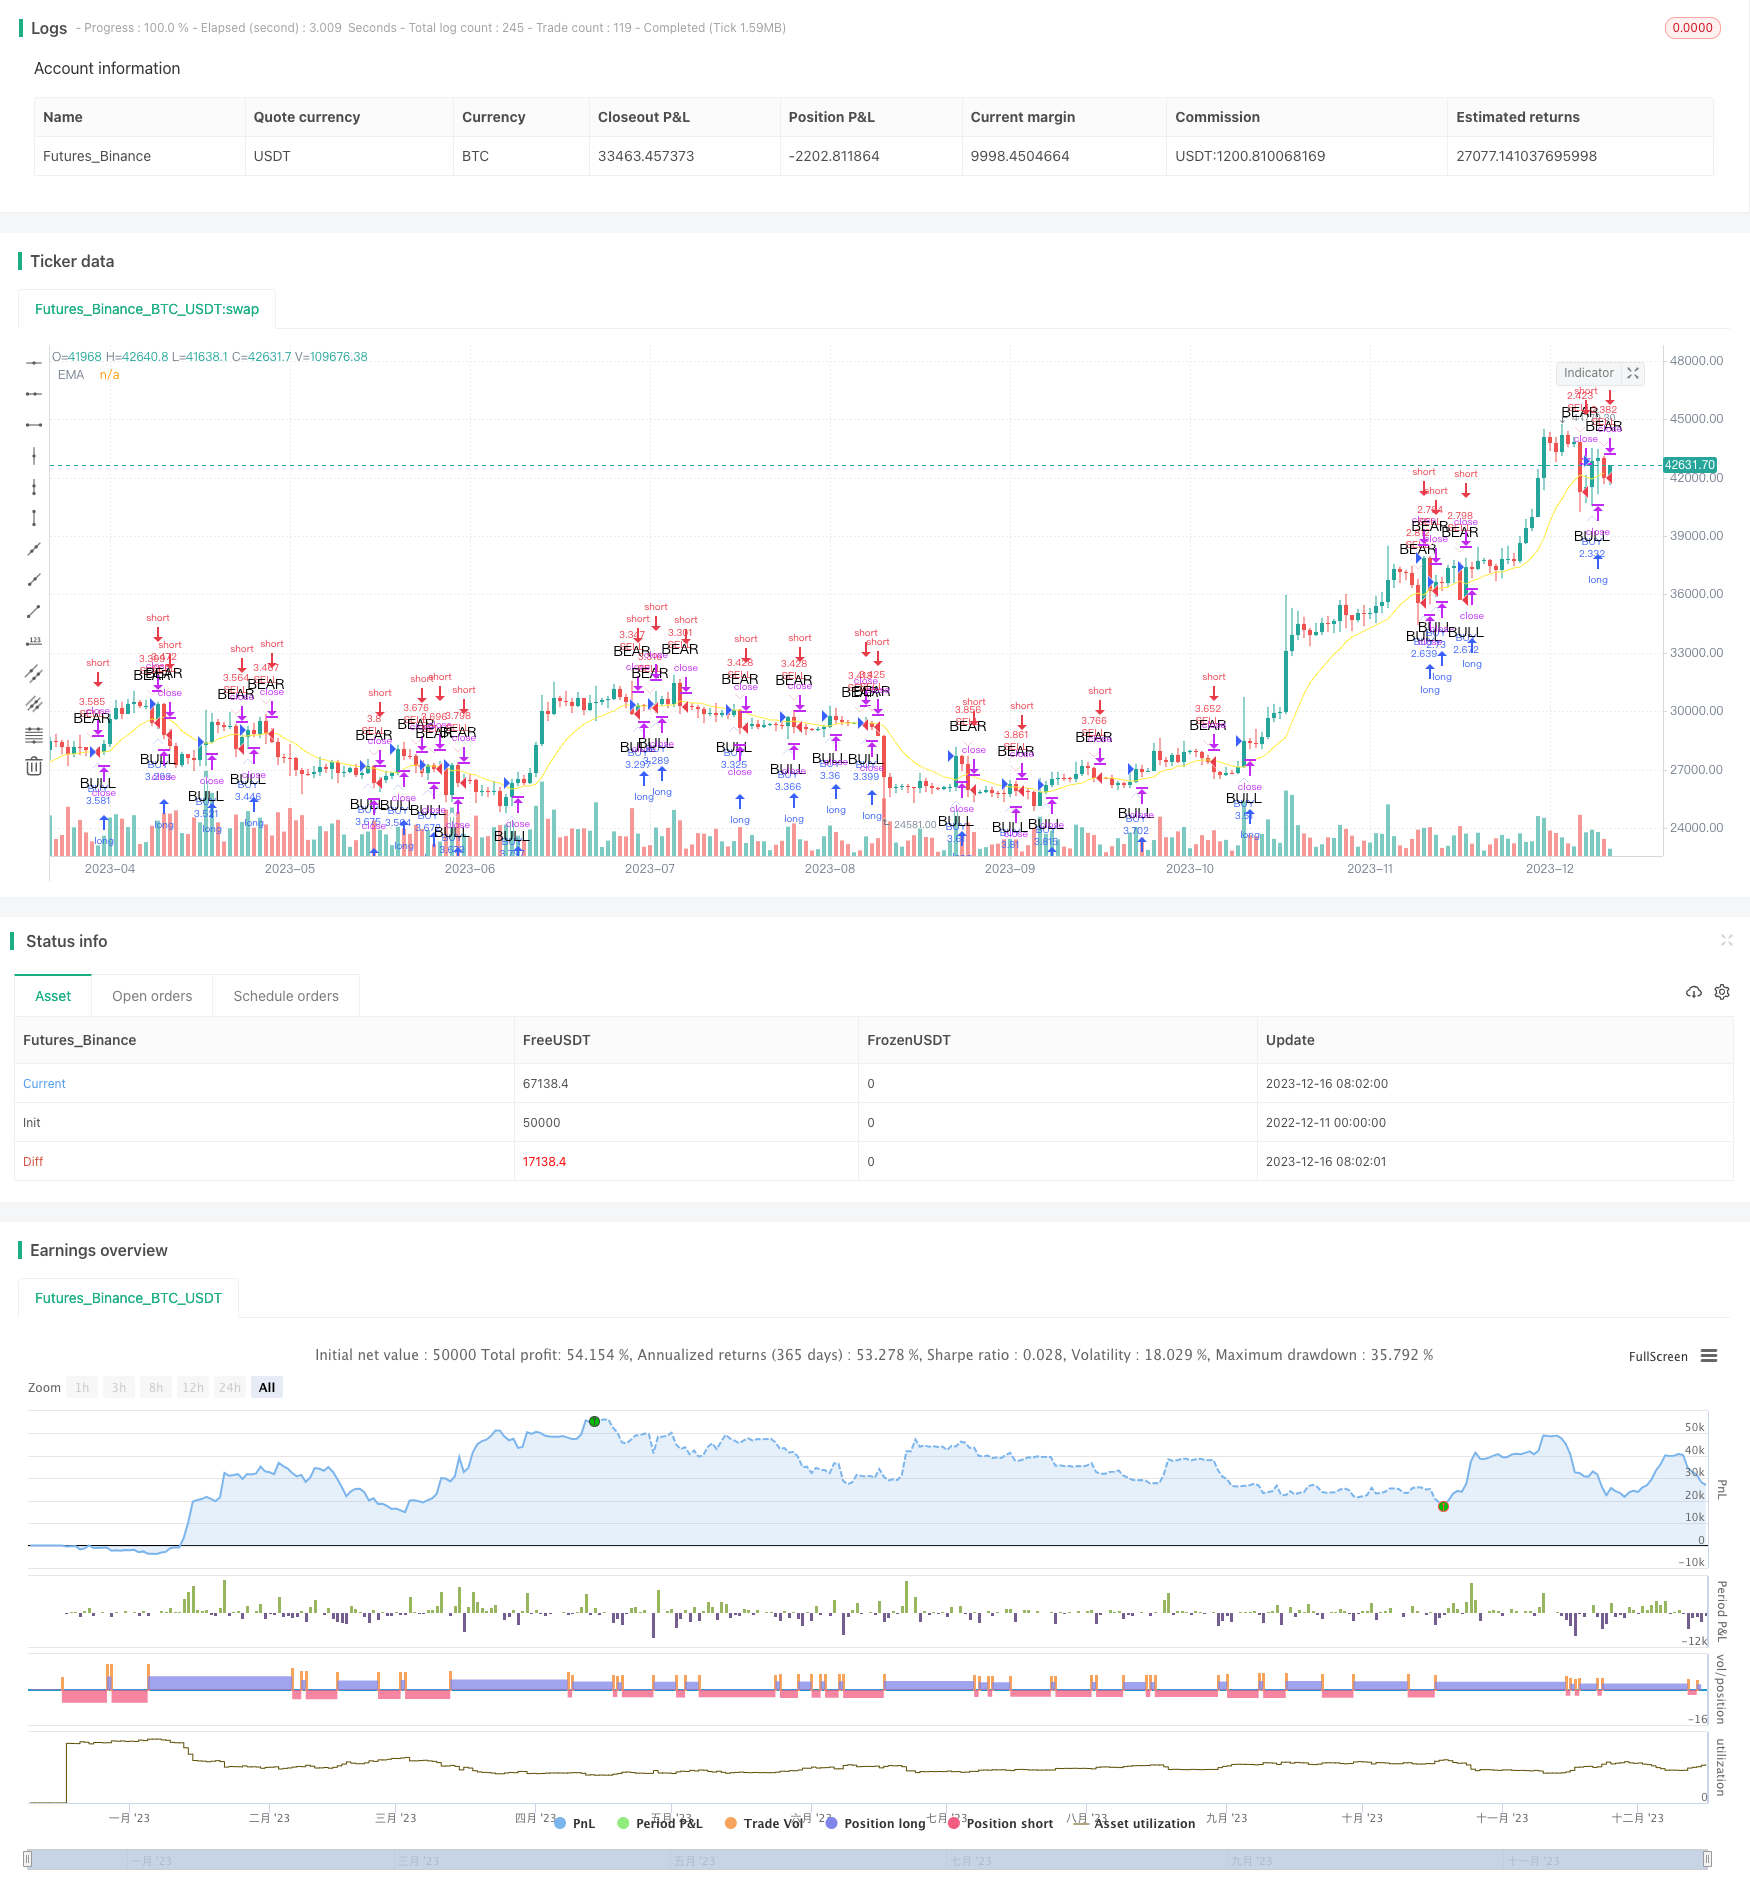
Overview
Galileo Galilei's moving average crossover strategy is a trading strategy based on moving averages. It generates trading signals by calculating the exponential moving average (EMA) over a specified period and comparing crossovers between the EMA and price. Sell signals are generated when the price drops below the EMA from the top down, while buy signals occur when the price breaks above the EMA from the bottom up.
Strategy Logic
The core of Galileo Galilei's strategy lies in the exponential moving average (EMA). EMA is a type of moving average that places more weight on recent prices. Its calculation formula is:
EMA today = (Closing price today × Smoothing factor) + (EMA yesterday × (1 − Smoothing factor))
Where the smoothing factor α = (2/(number of periods + 1))
The strategy dynamically calculates the EMA based on user input period parameters. It then compares the crossovers between price and EMA to determine trading signals:
When price drops below the EMA from the top down, a sell signal is generated for short trading.
When price breaks above the EMA from below, a buy signal is triggered for long trading.
The strategy also plots the EMA line on the chart, along with arrow markers indicating buy and sell signals.
Advantage Analysis
Galileo Galilei's moving average crossover strategy has the following advantages:
- Simple logic that is easy to understand and implement, suitable for beginners.
- Faster response to price changes through the use of EMA.
- Clear crossover signals without excessive whipsaws.
- Flexibility to adapt to different market environments by adjusting EMA parameters.
- Defined entry and exit signals provide risk control.
Risk Analysis
Potential risks of this strategy include:
- More false signals may occur during high price volatility. A stop loss strategy could help optimize.
- Reliance on a single indicator makes it vulnerable to price manipulation. Additional indicators may improve robustness.
- Lagging effect, especially after sudden events. Shortening EMA periods could help.
- Unable to adapt to prolonged one-sided price trends, a common limitation among moving average strategies.
Optimization Directions
Some ways to optimize the strategy:
Incorporate other indicators to construct a composite strategy for increased robustness against false signals. Examples include volume, trend indicators etc.
Add stop loss mechanisms like trailing stop loss or percentage-based stop loss to control single-trade loss amount.
Test EMAs with different parameter combinations to find optimal settings. Other moving average types could also be evaluated.
Assess re-entry logic to capture rebounds after initial price reversals, improving profitability.
Conclusion
Galileo Galilei's moving average crossover is a simple yet practical strategy with clear logic and easy operability. It is suitable for novice quant traders. With continuous improvements, its performance could become increasingly superior over time.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 11 | Length |
| v_input_2_open | 0 | Source: open | high | low | close | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_3 | true | From Day |
| v_input_4 | true | From Month |
| v_input_5 | 2020 | From Year |
| v_input_6 | true | To Day |
| v_input_7 | 12 | To Month |
| v_input_8 | 2021 | To Year |
Source Pine Script
/*backtest
start: 2022-12-11 00:00:00
end: 2023-12-17 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © armigoldman

//@version=3
strategy(title="Galileo Galilei", shorttitle="Galileo Galilei", overlay=true, initial_capital = 100000, default_qty_type=strategy.cash, default_qty_value = 100000)
len = input(11, minval=1, title="Length")
src = input(open, title="Source")
out = ema(src, len)
plot(out, title="EMA", color=yellow)
//last8h = highest(close, 8)
//lastl8 = lowest(close, 8)

//plot(last8h, color=red, linewidth=2)
//plot(lastl8, color=green, linewidth=2)

////////////////////////////////////////////////////////////////////////////////
// BACKTESTING RANGE

// From Date Inputs
fromDay = input(defval=1, title="From Day", minval=1, maxval=31)
fromMonth = input(defval=1, title="From Month", minval=1, maxval=12)
fromYear = input(defval=2020, title="From Year", minval=1970)

// To Date Inputs
toDay = input(defval=1, title="To Day", minval=1, maxval=31)
toMonth = input(defval=12, title="To Month", minval=1, maxval=12)
toYear = input(defval=2021, title="To Year", minval=1970)

// Calculate start/end date and time condition
startDate = timestamp(fromYear, fromMonth, fromDay, 00, 00)
finishDate = timestamp(toYear, toMonth, toDay, 00, 00)
time_cond = true


bearish = cross(close, out) == 1 and close[1] > close
bullish = cross(close, out) == 1 and close[1] < close

plotshape(bearish, color=white, style=shape.arrowdown, text="BEAR", location=location.abovebar)
plotshape(bullish, color=white, style=shape.arrowup, text="BULL", location=location.belowbar)

buy = if cross(close, out) == 1 and close[1] < close
    strategy.entry("BUY", strategy.long, when=time_cond)
        //strategy.close_all(when=bearish)
        // strategy.exit("exit", "Long", profit =, loss = 35)


sell = if cross(close, out) == 1 and close[1] > close
    strategy.entry("SELL", strategy.short, when=time_cond)
        //sell = if bearish
        //strategy.close_all(when=bullish)
        // strategy.exit("exit", "Long", profit = bullish, loss = 100)

profit = strategy.netprofit
if not time_cond
    strategy.close_all()

//plotshape(true, style=shape.triangleup, location=location.abovebar)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Galileo-Galileis-Moving-Average-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- ATR and T3 Moving Average StrategyPine Script · Trend following · 5m