Strategy vault / Mean reversion
Gaussian Channel with Stochastic RSI Quantitative Trading Strategy Optimization System
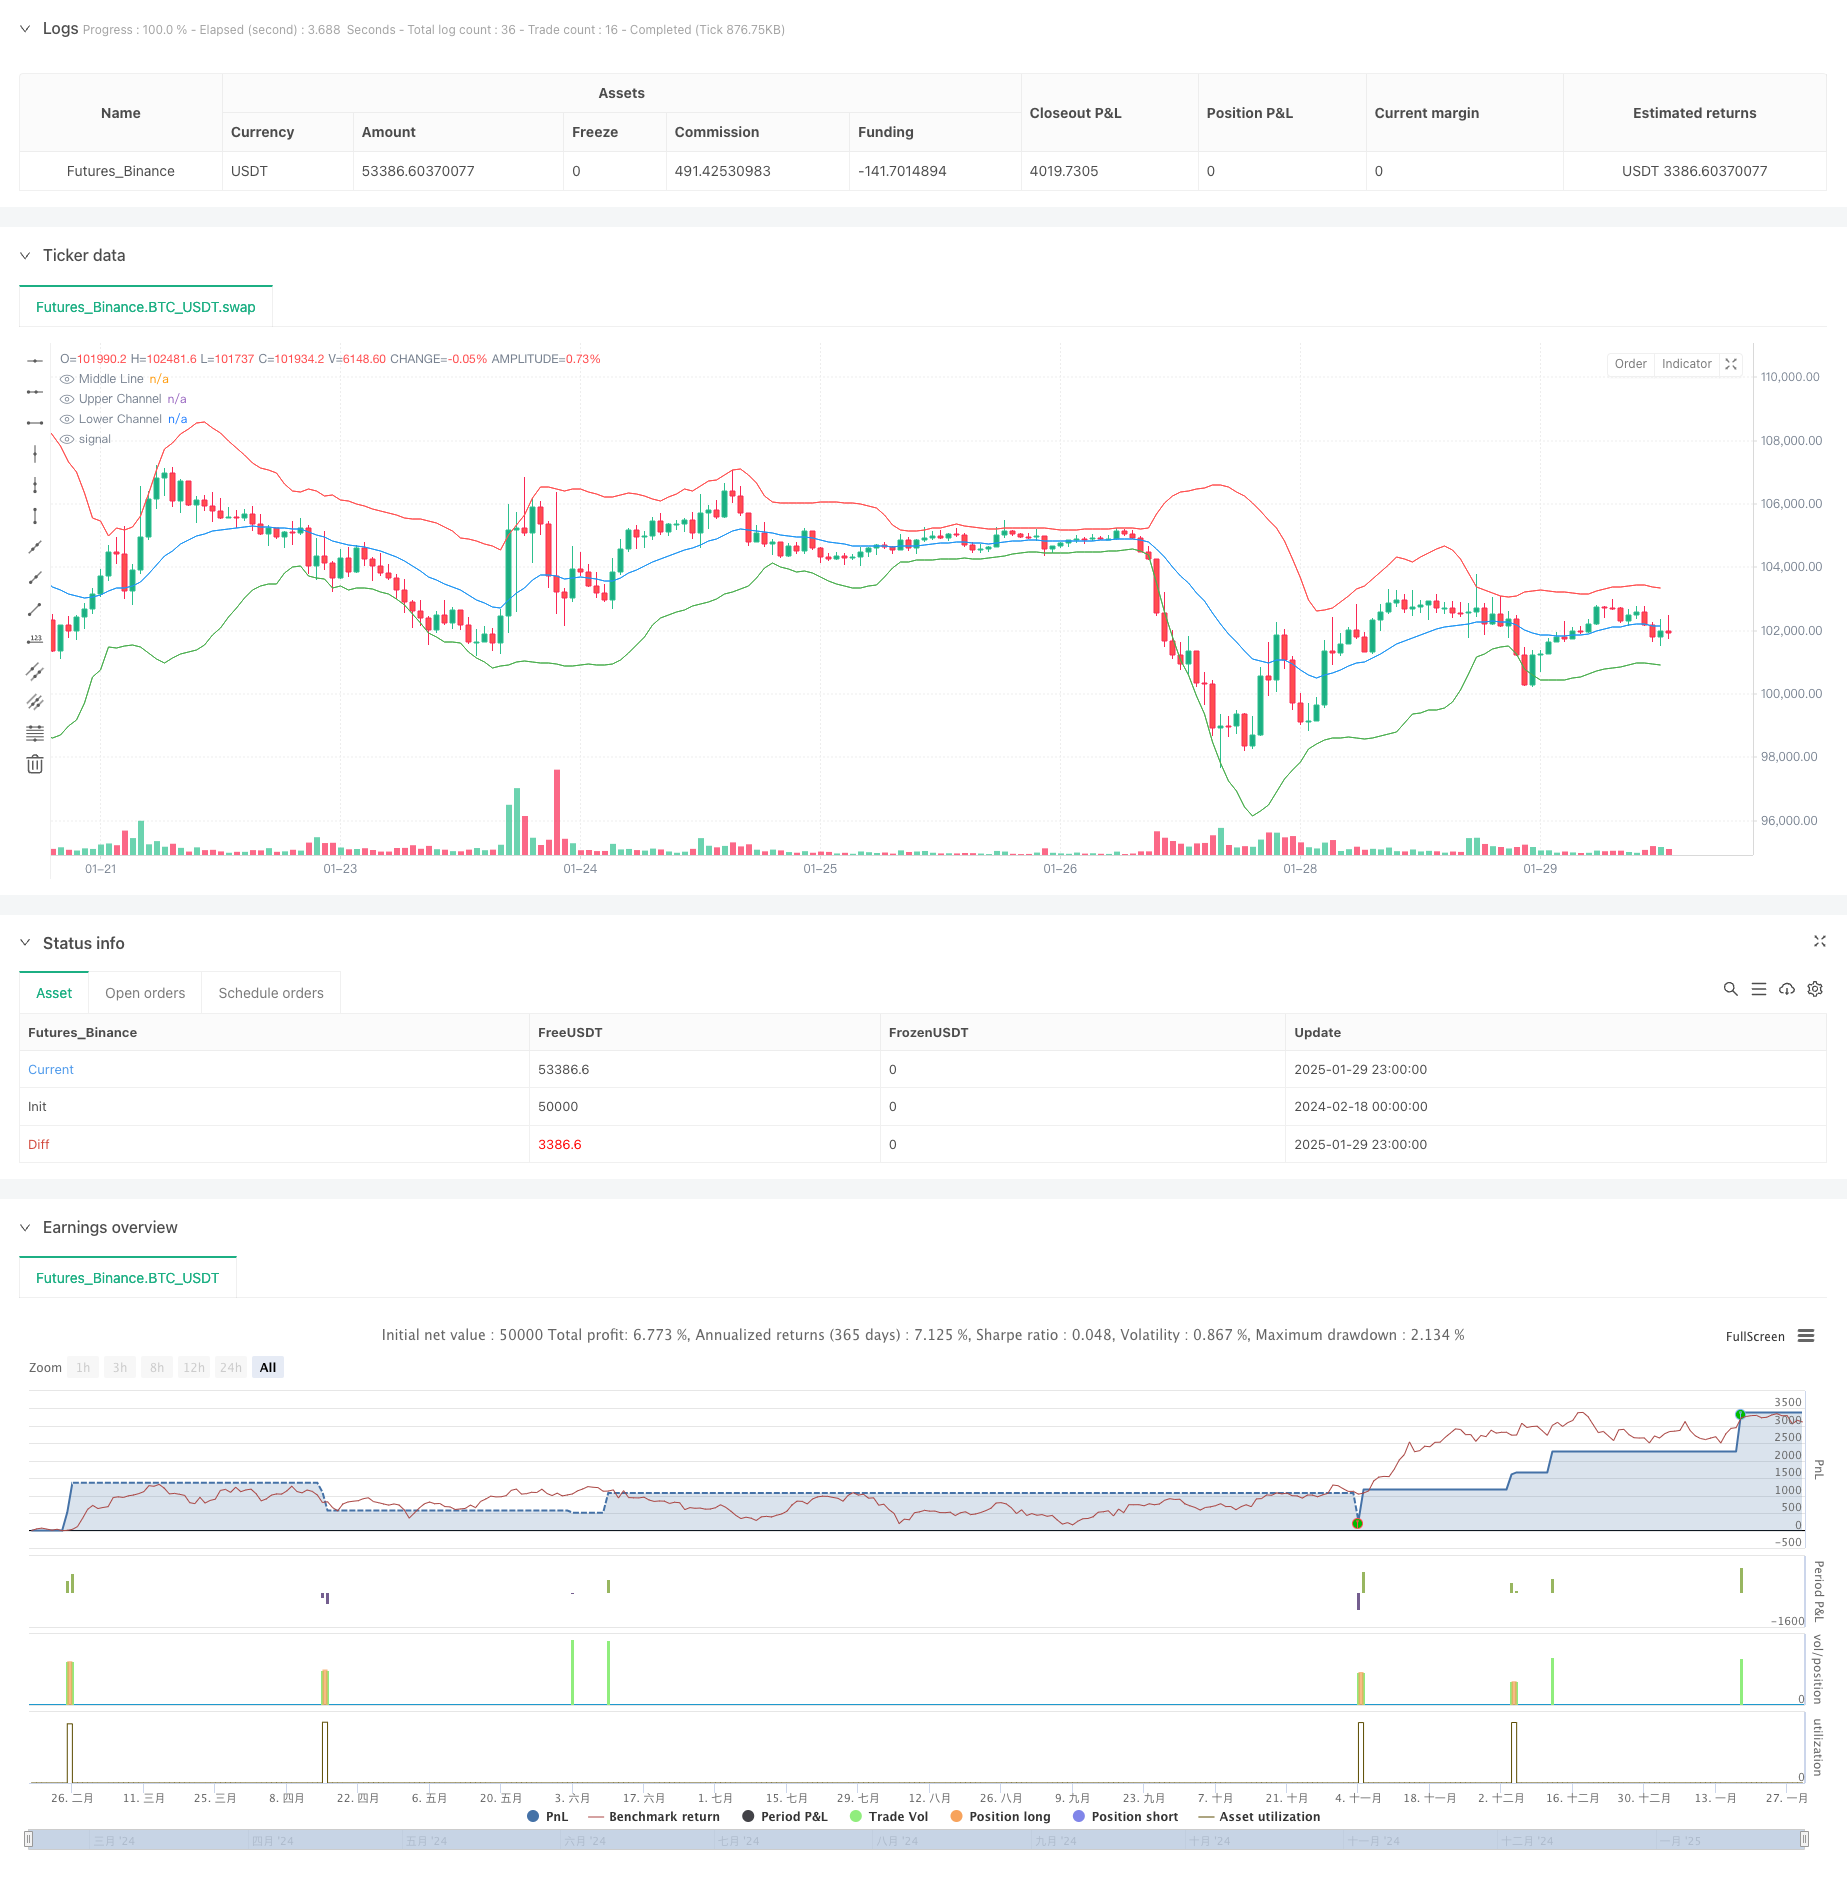
This strategy is a quantitative trading system based on the Gaussian Channel and Stochastic RSI indicator. It combines mean reversion and momentum principles from technical analysis, entering long positions when…
Overview
This strategy is a quantitative trading system based on the Gaussian Channel and Stochastic RSI indicator. It combines mean reversion and momentum principles from technical analysis, entering long positions when price touches the lower channel and Stochastic RSI shows oversold signals, and exiting when price touches the upper channel or Stochastic RSI shows overbought signals. The strategy is designed for long-only trading.
Strategy Principles
The core logic is based on the following key calculations:
- Gaussian Channel construction: Using EMA as the middle line, with channel width calculated as 2 times the standard deviation.
- Stochastic RSI calculation: First calculating 14-period RSI, then computing RSI's highest and lowest values within 14 periods, finally determining current RSI's relative position within this range.
- Entry signals: Price breaks above the lower channel while Stochastic RSI breaks above 20.
- Exit signals: Price breaks above the upper channel or Stochastic RSI breaks below 80.
Strategy Advantages
- Dual confirmation mechanism: Combining price channel and momentum indicators reduces false signals.
- Comprehensive risk control: Implements percentage-based position management and considers transaction costs and slippage.
- Mean reversion characteristics: Gaussian Channel effectively captures price volatility range, improving trading accuracy.
- Strong dynamic adaptability: Strategy parameters can be optimized for different market conditions.
Strategy Risks
- Trend market risk: May exit positions too early in strong trend markets, missing major moves.
- Parameter sensitivity: Channel multiplier and RSI parameters significantly impact strategy performance.
- Market environment dependency: Strategy performs better in ranging markets but may underperform in trending markets.
- Calculation delay risk: Technical indicators have inherent calculation delays that may affect trading timing.
Strategy Optimization Directions
- Introduce adaptive parameters: Dynamically adjust channel multiplier based on market volatility.
- Add market environment recognition: Include trend strength indicators to use different parameter settings in different market conditions.
- Optimize money management: Adjust position size dynamically based on signal strength.
- Improve stop-loss mechanism: Add trailing stop-loss functionality to better protect profits.
Summary
The strategy combines Gaussian Channel and Stochastic RSI indicators to create a relatively robust trading system. Its strengths lie in the dual confirmation mechanism and comprehensive risk control, though attention must be paid to adaptability in different market environments. Strategy performance can be further enhanced through the introduction of adaptive parameters and market environment recognition.
Source Pine Script
/*backtest
start: 2024-02-18 00:00:00
end: 2025-01-30 00:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Gaussian Channel with Stochastic RSI", overlay=true, initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=200, commission_type=strategy.commission.percent, commission_value=0.1, slippage=0)

// Gaussian Channel Parameters
gc_length = input.int(20, "Gaussian Channel Length", minval=1)
gc_mult = input.float(2.0, "Gaussian Channel Multiplier", minval=0.1)

middle = ta.ema(close, gc_length)
stdev = ta.stdev(close, gc_length)
upper = middle + gc_mult * stdev
lower = middle - gc_mult * stdev

// Plot Channels
plot(middle, "Middle Line", color=color.blue)
plot(upper, "Upper Channel", color=color.red)
plot(lower, "Lower Channel", color=color.green)

// Stochastic RSI Parameters
rsi_length = input.int(14, "RSI Length", minval=1)
stoch_length = input.int(14, "Stochastic Length", minval=1)
smooth_k = input.int(3, "Smooth %K", minval=1)
oversold = input.int(20, "Oversold Level", minval=0, maxval=100)
overbought = input.int(80, "Overbought Level", minval=0, maxval=100)

// Calculate Stochastic RSI
rsi = ta.rsi(close, rsi_length)
lowest_rsi = ta.lowest(rsi, stoch_length)
highest_rsi = ta.highest(rsi, stoch_length)
stoch_rsi = highest_rsi != lowest_rsi ? (rsi - lowest_rsi) / (highest_rsi - lowest_rsi) * 100 : 0
k = ta.sma(stoch_rsi, smooth_k)

// Entry/Exit Conditions
enterLong = ta.crossover(close, lower) and ta.crossover(k, oversold)
exitLong = ta.crossover(close, upper) or ta.crossunder(k, overbought)

// Strategy Execution
if (time >= timestamp(2018, 01, 01, 0, 0) and time < timestamp(2069, 01, 01, 0, 0))
    if enterLong
        strategy.entry("Long", strategy.long)
    if exitLong
        strategy.close("Long")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-02-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Gaussian-Channel-with-Stochastic-RSI-Quantitative-Trading-Strategy-Optimization-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- Oma and Apollo Dual Rail Trading StrategyPine Script · Mean reversion · 5m
- 3EMA with Stochastic RSI StrategyPine Script · Mean reversion · 1h
- Dual Reversal Overlap Selective StrategyPine Script · Mean reversion · 1h
- Market Cypher Wave B Automated Trading StrategyPine Script · Mean reversion · 1h